Delete Negative Items Off Your Credit Report With The Furnisher Verification Protocol
The Legal Process That Makes Credit Agencies Prove Every Item... Or DELETE It.
Collections, charge-offs, late payments, repossessions and medical bills reported on your credit must be 100% accurate and 100% complete. They NEVER actually are.
What happens when the companies reporting on you have to prove it
They thought their score was a life sentence
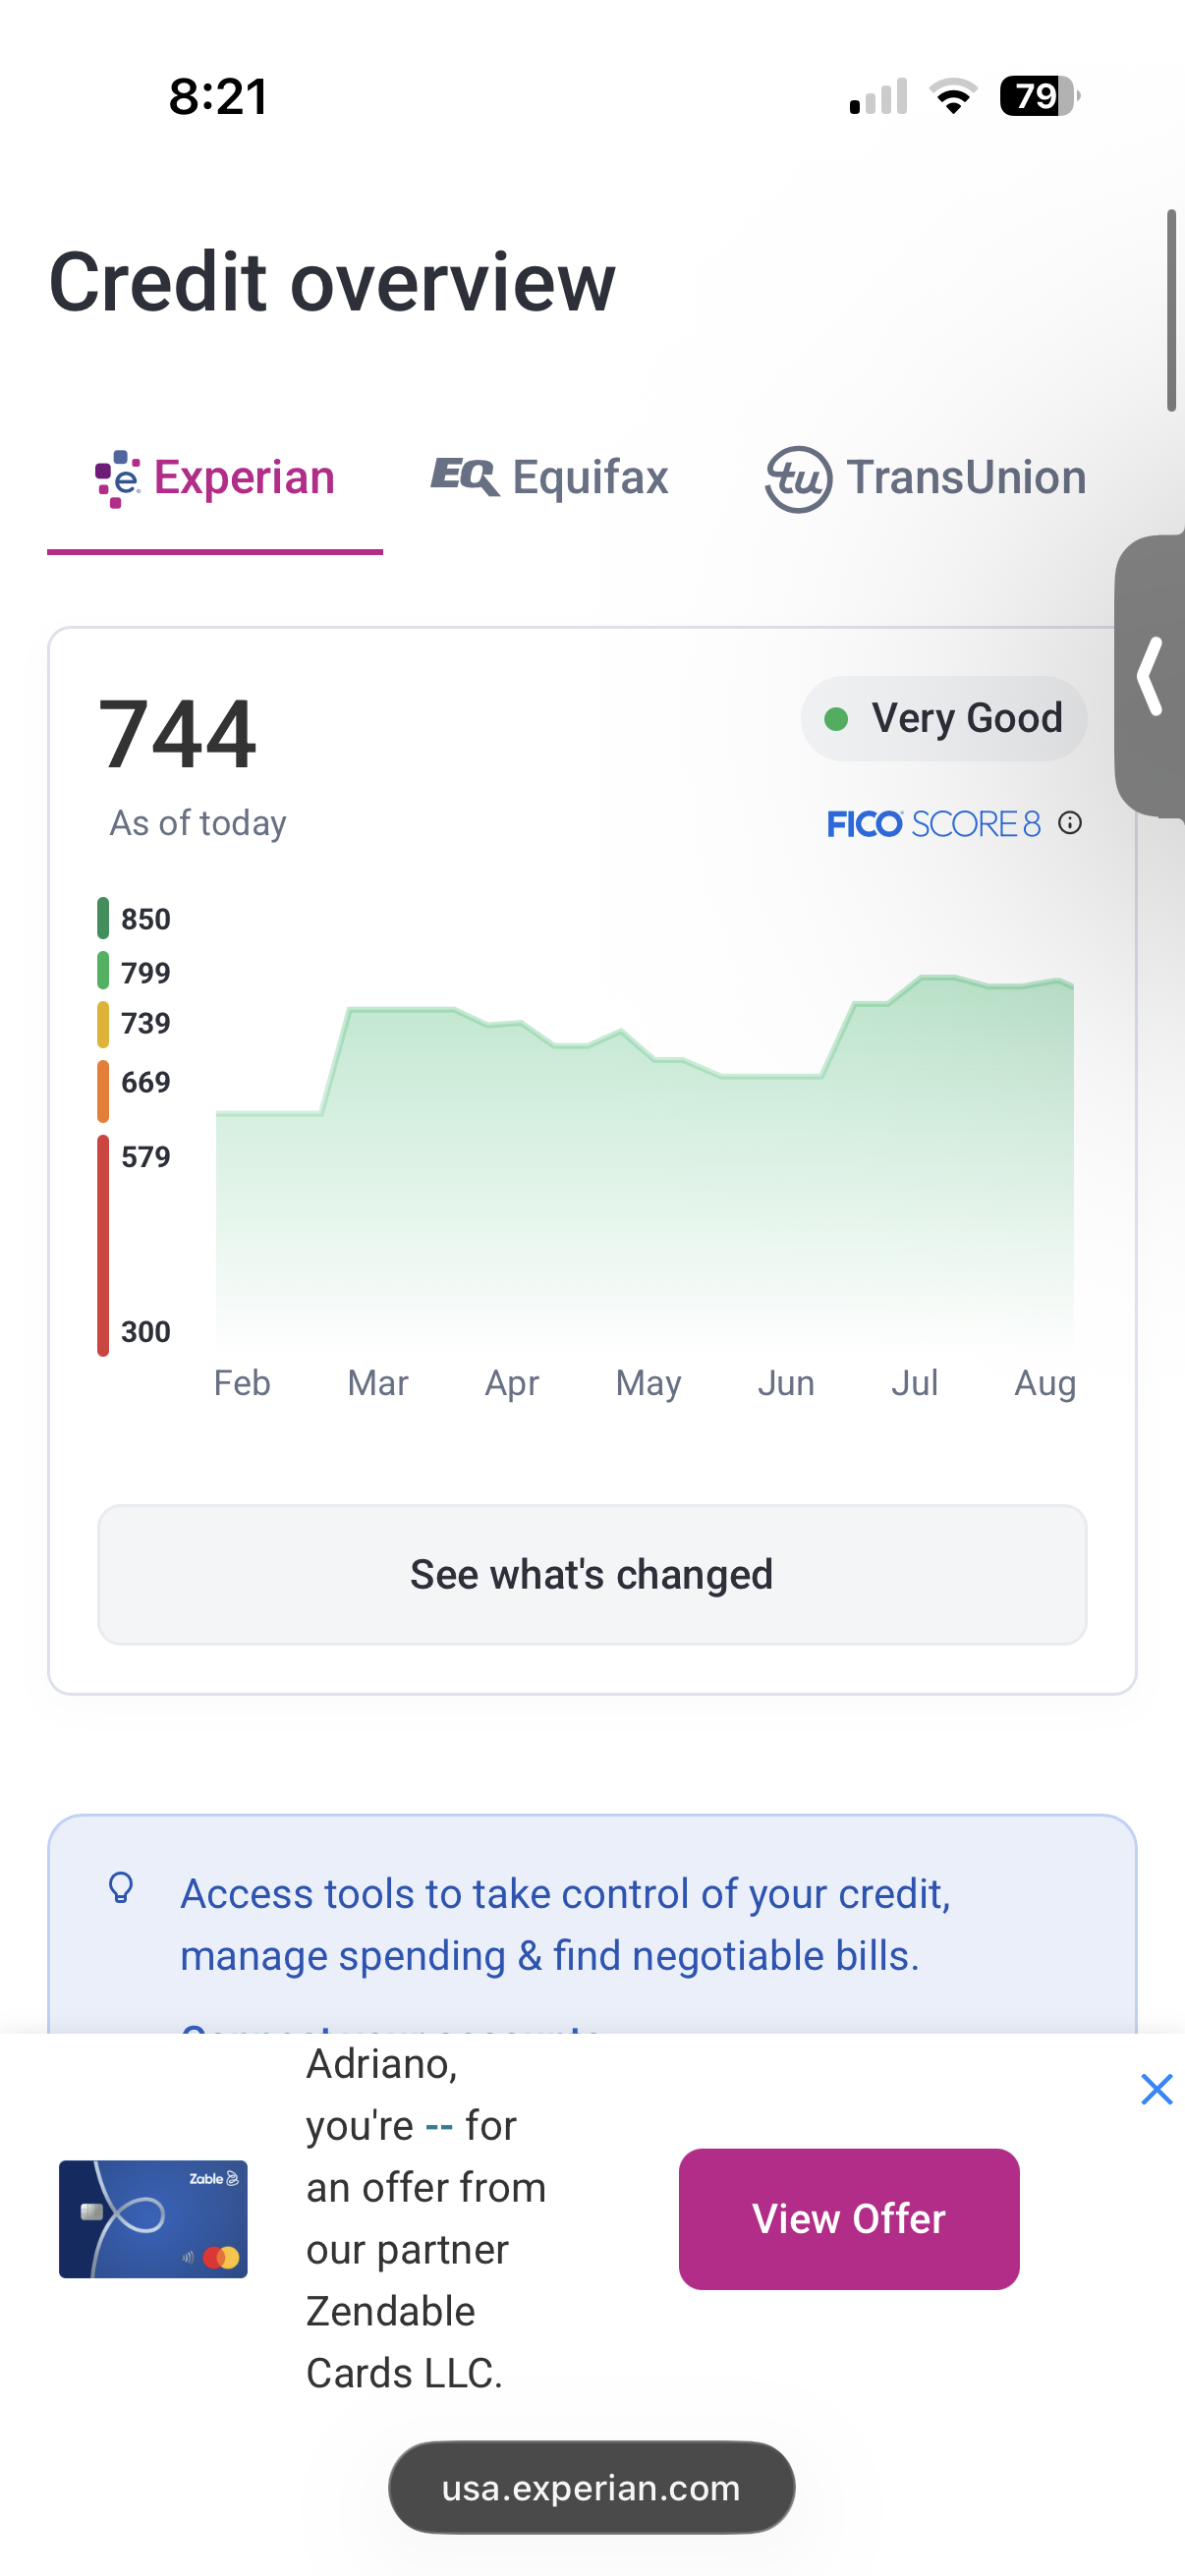
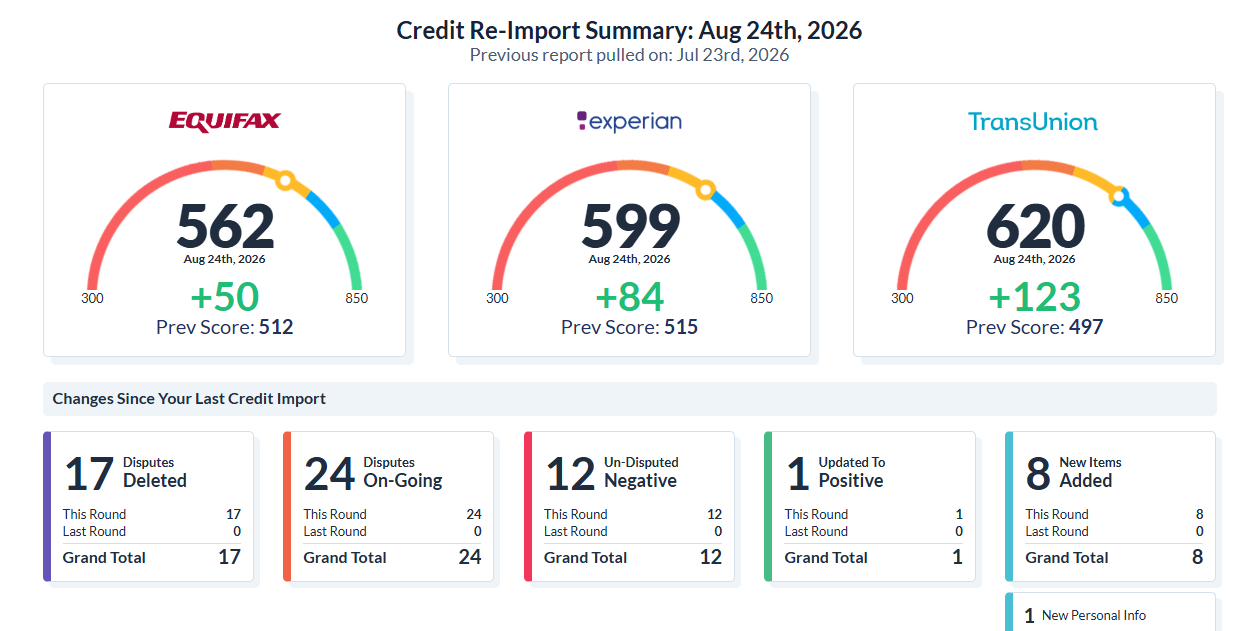
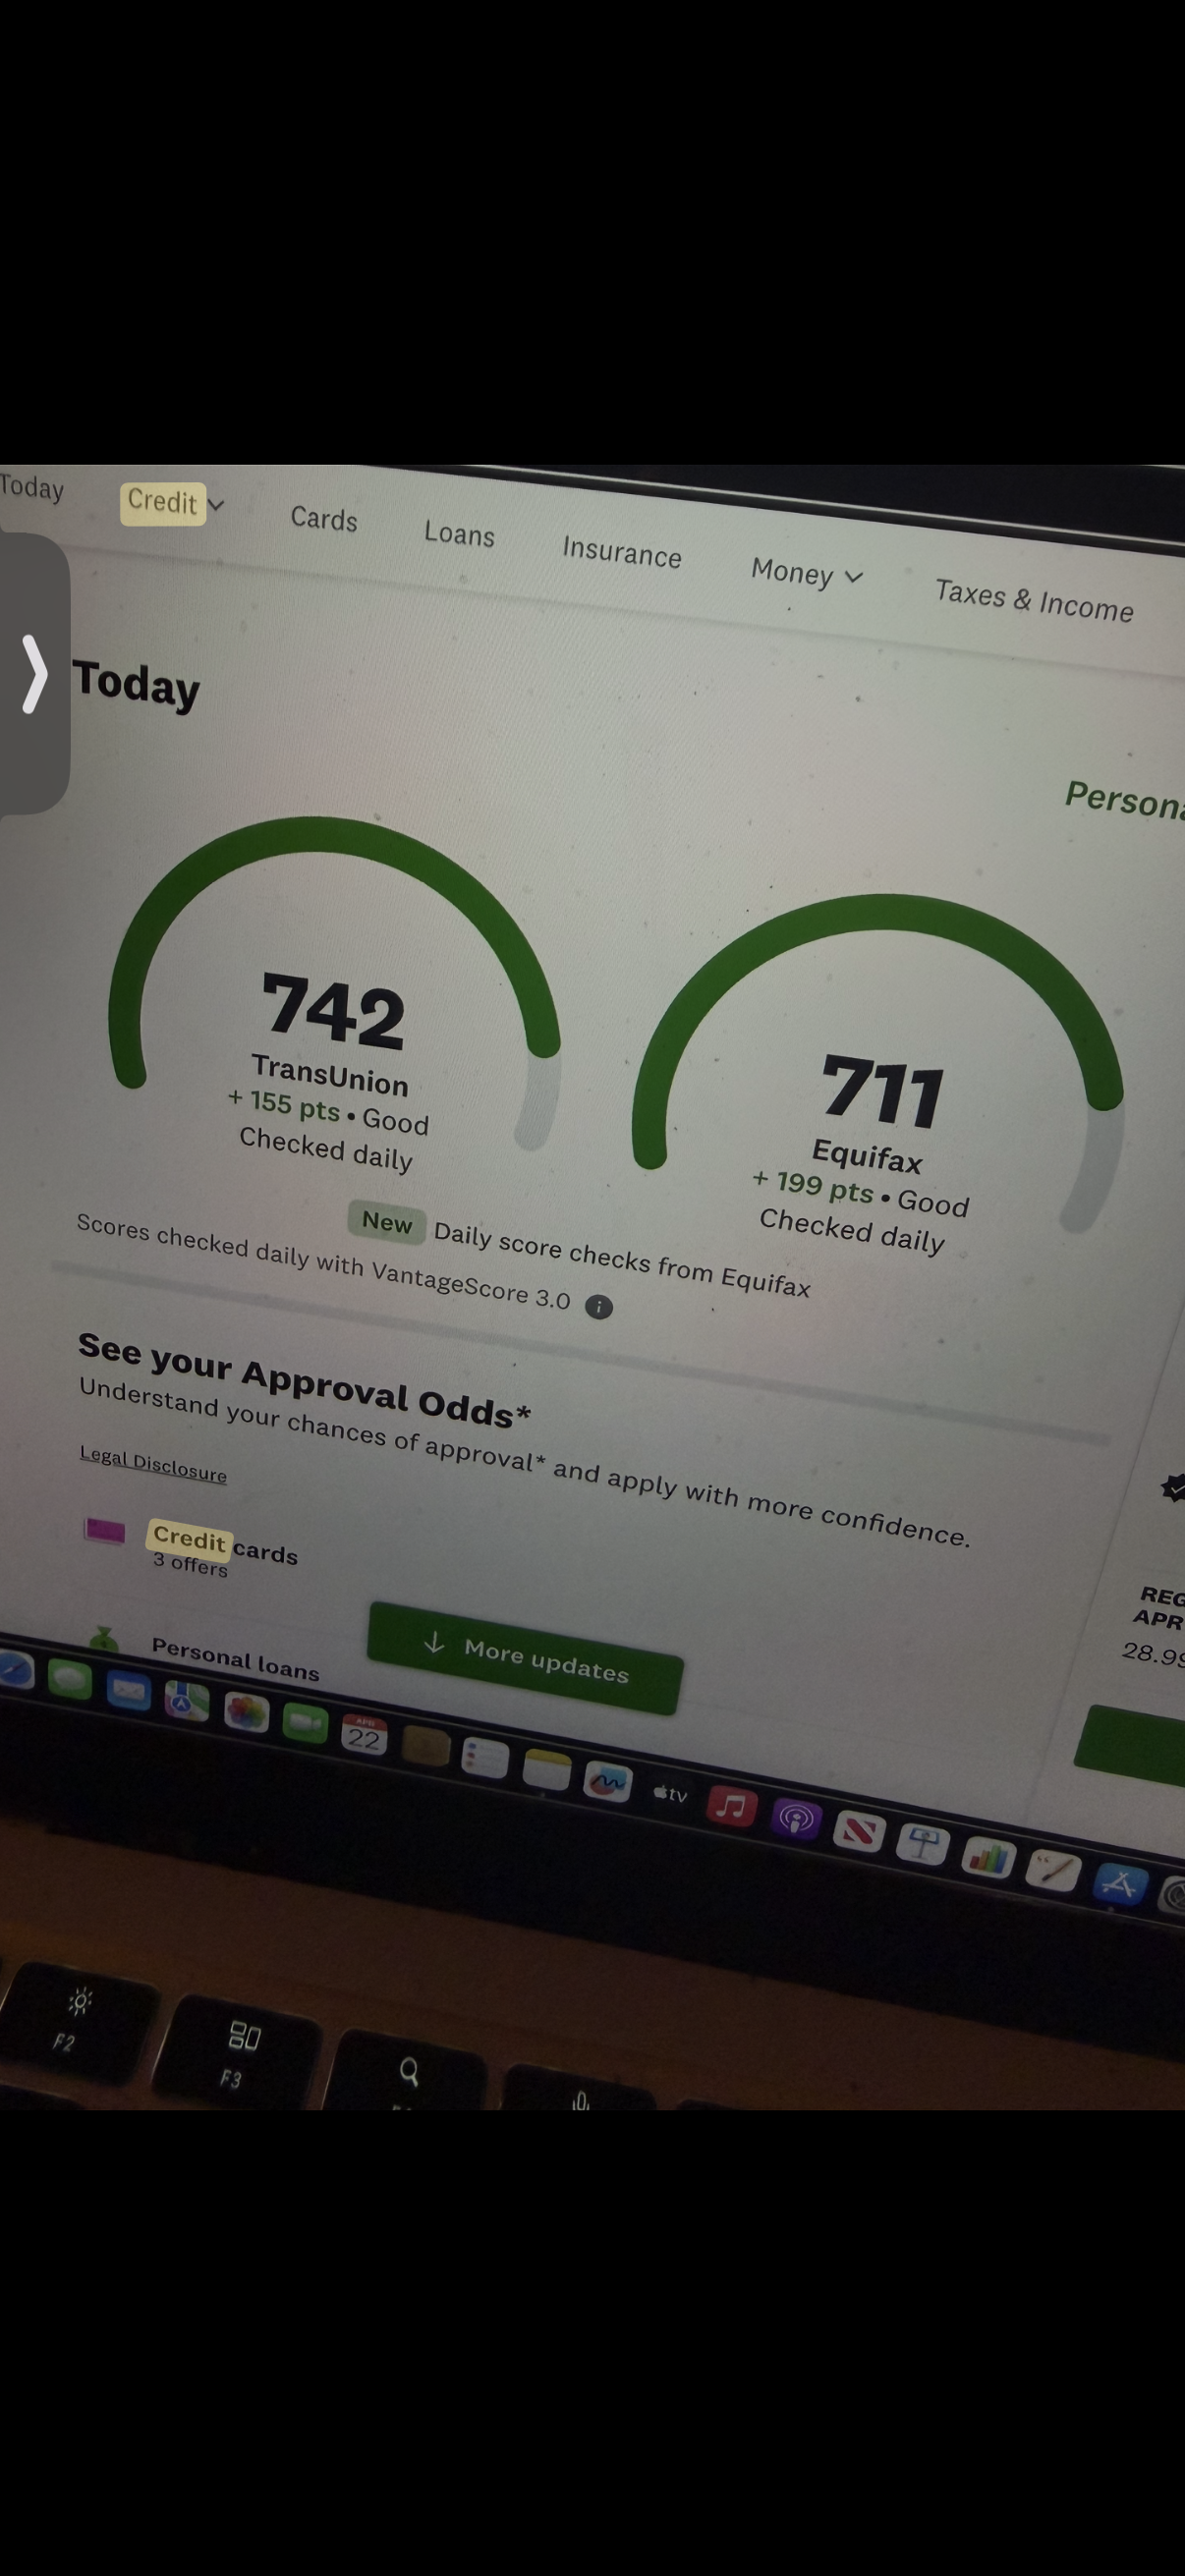
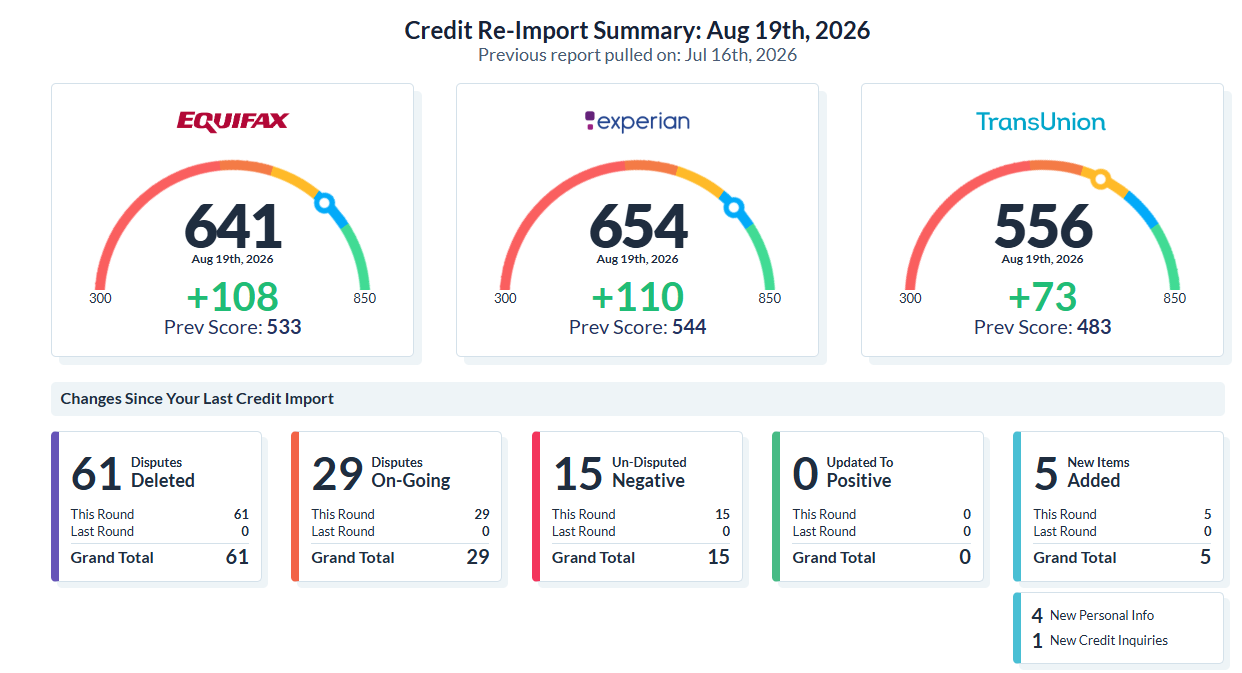
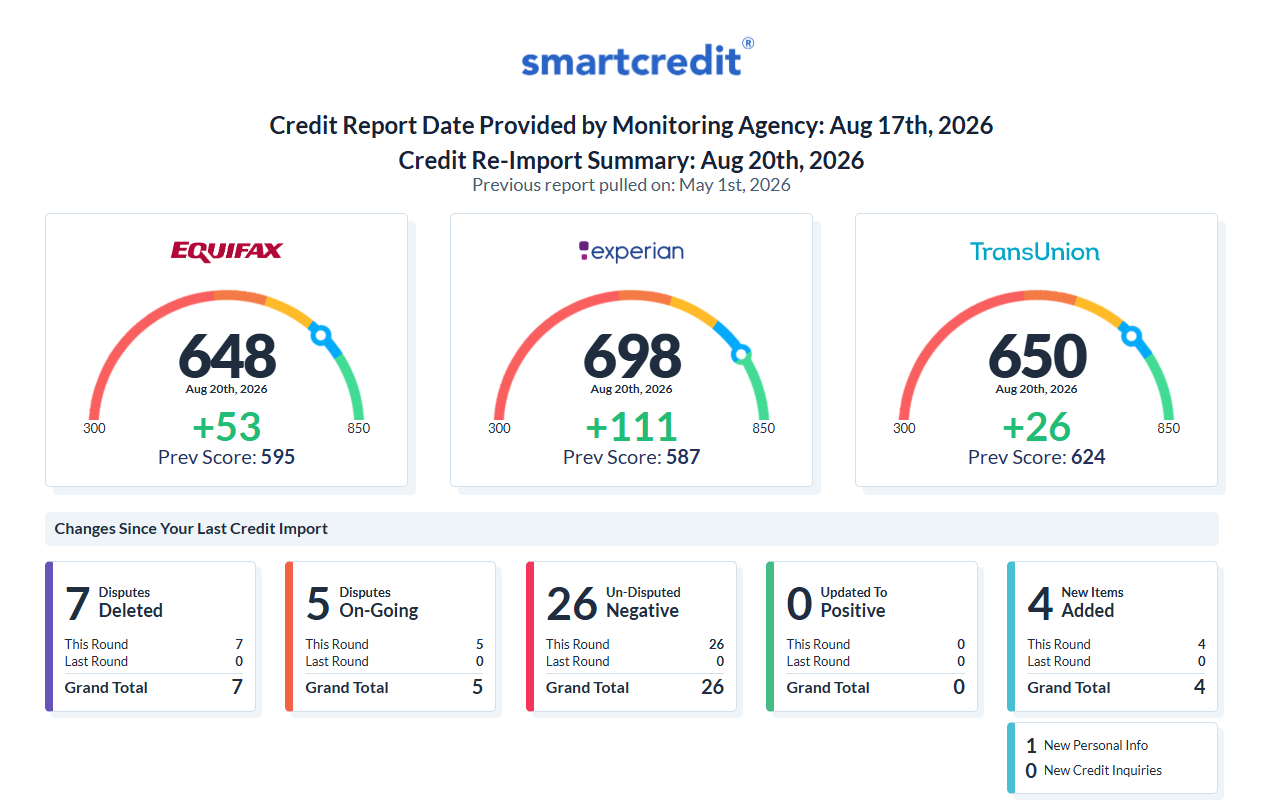
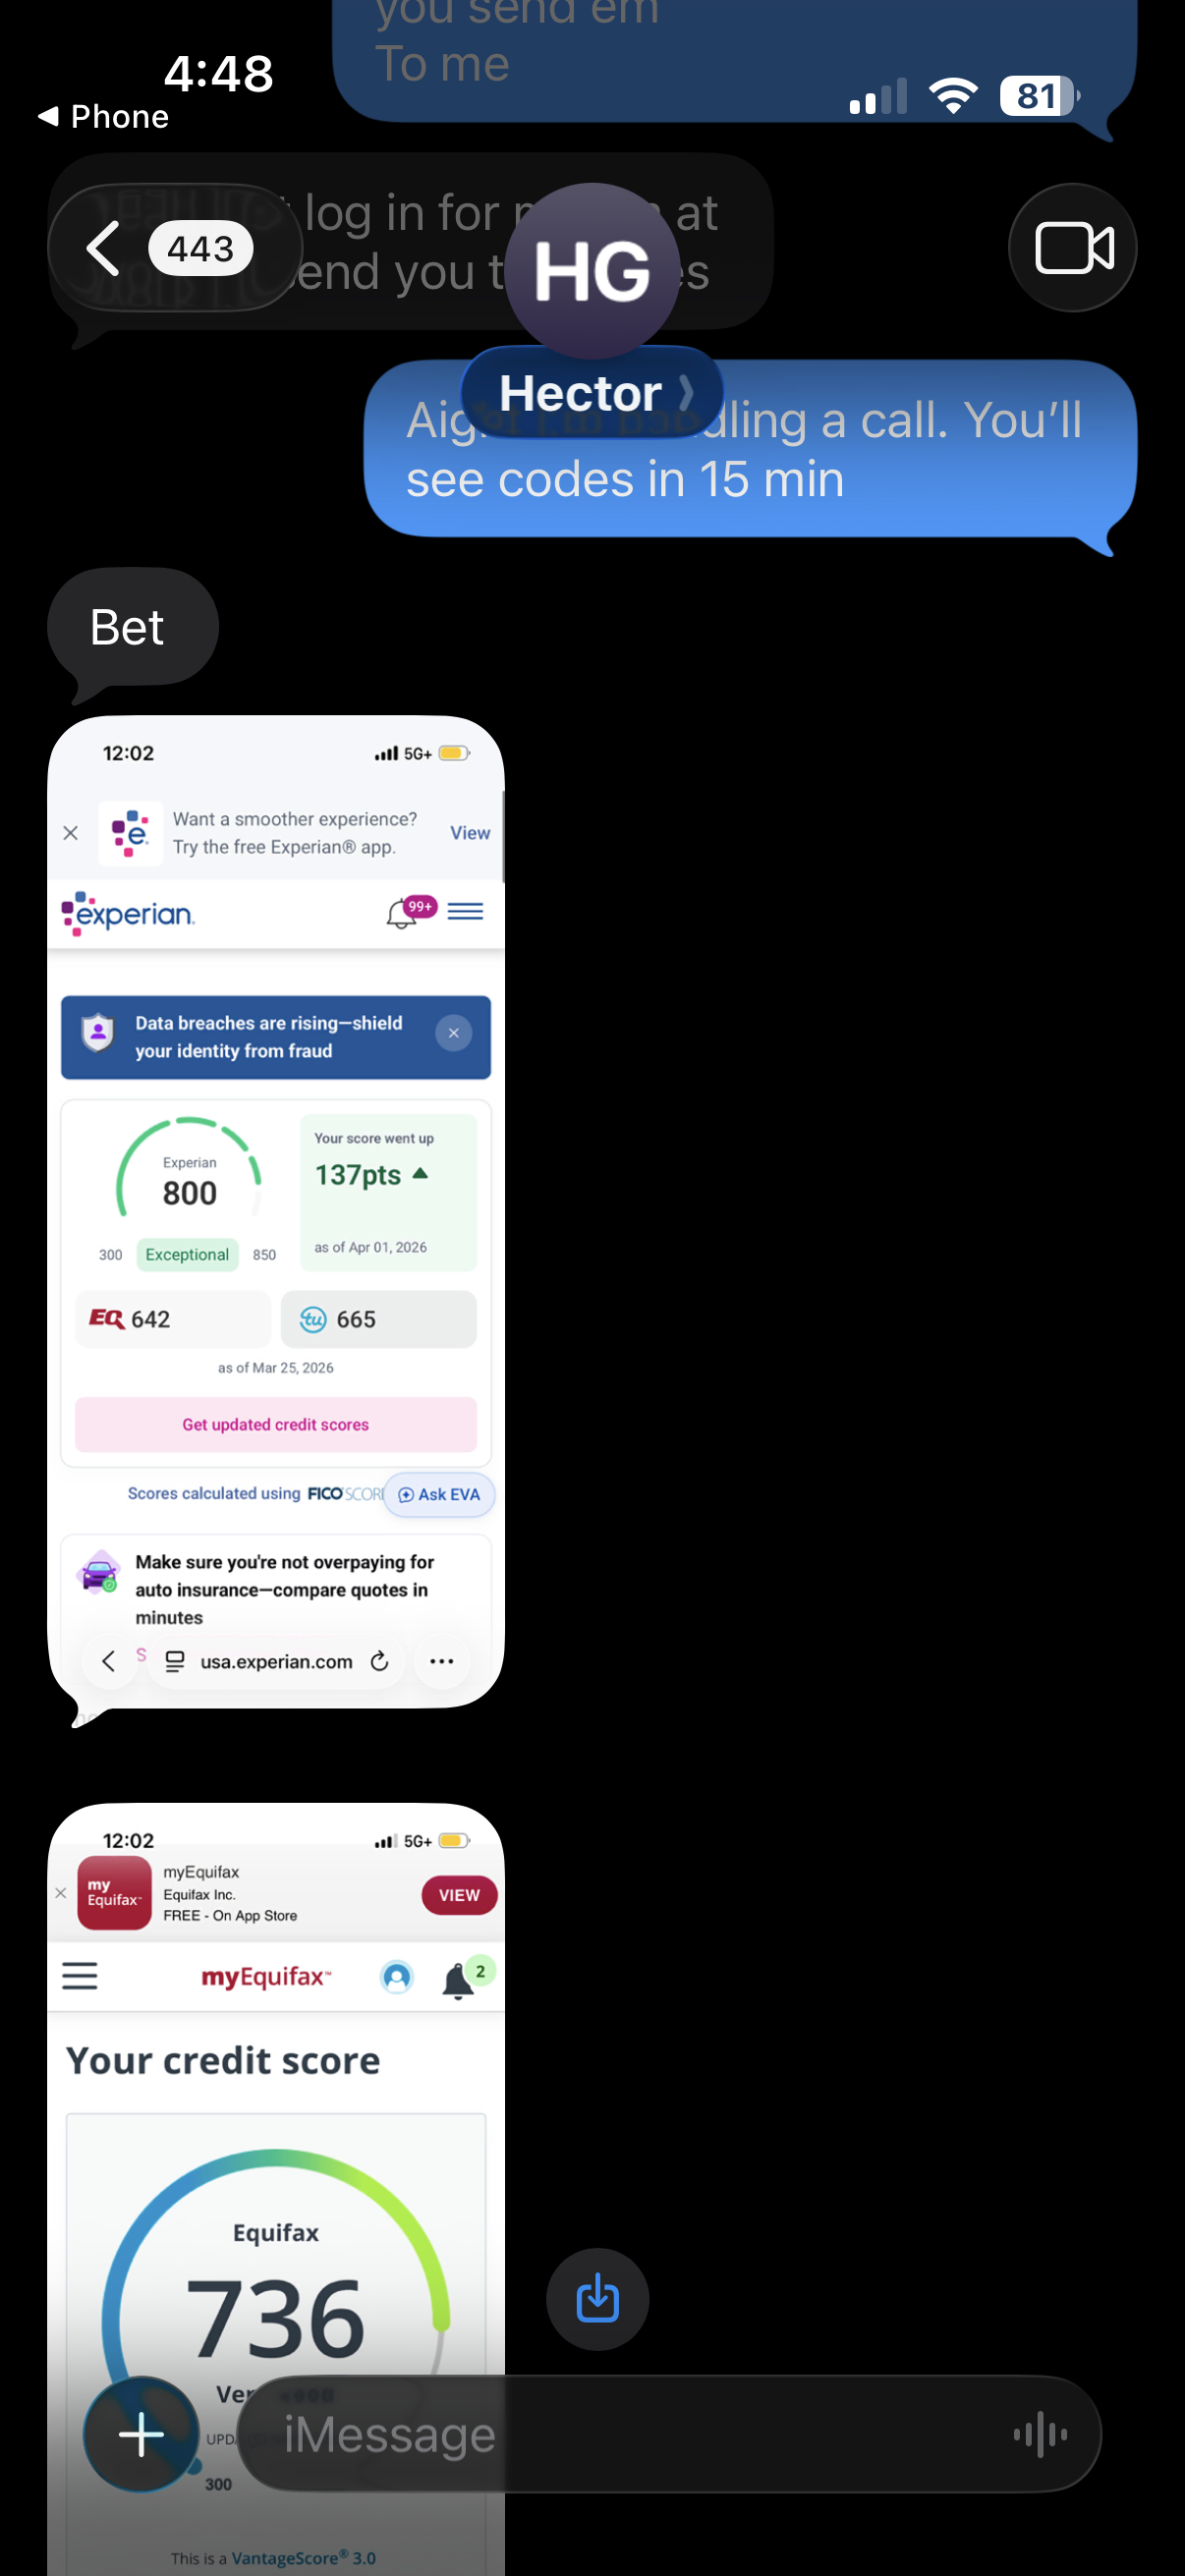
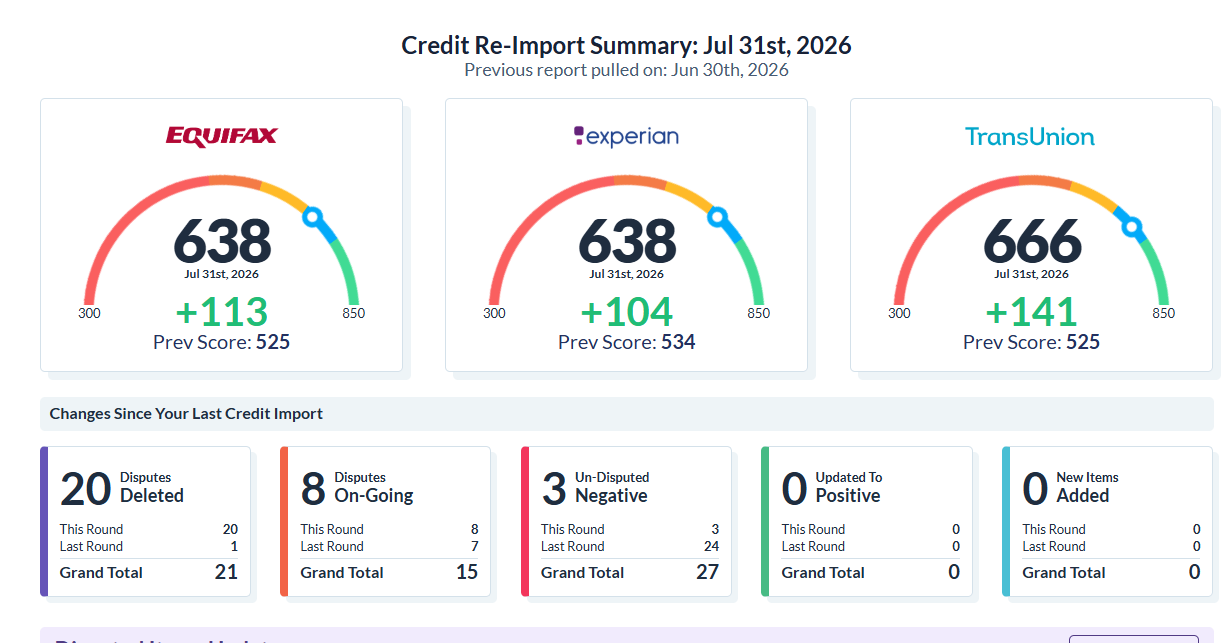
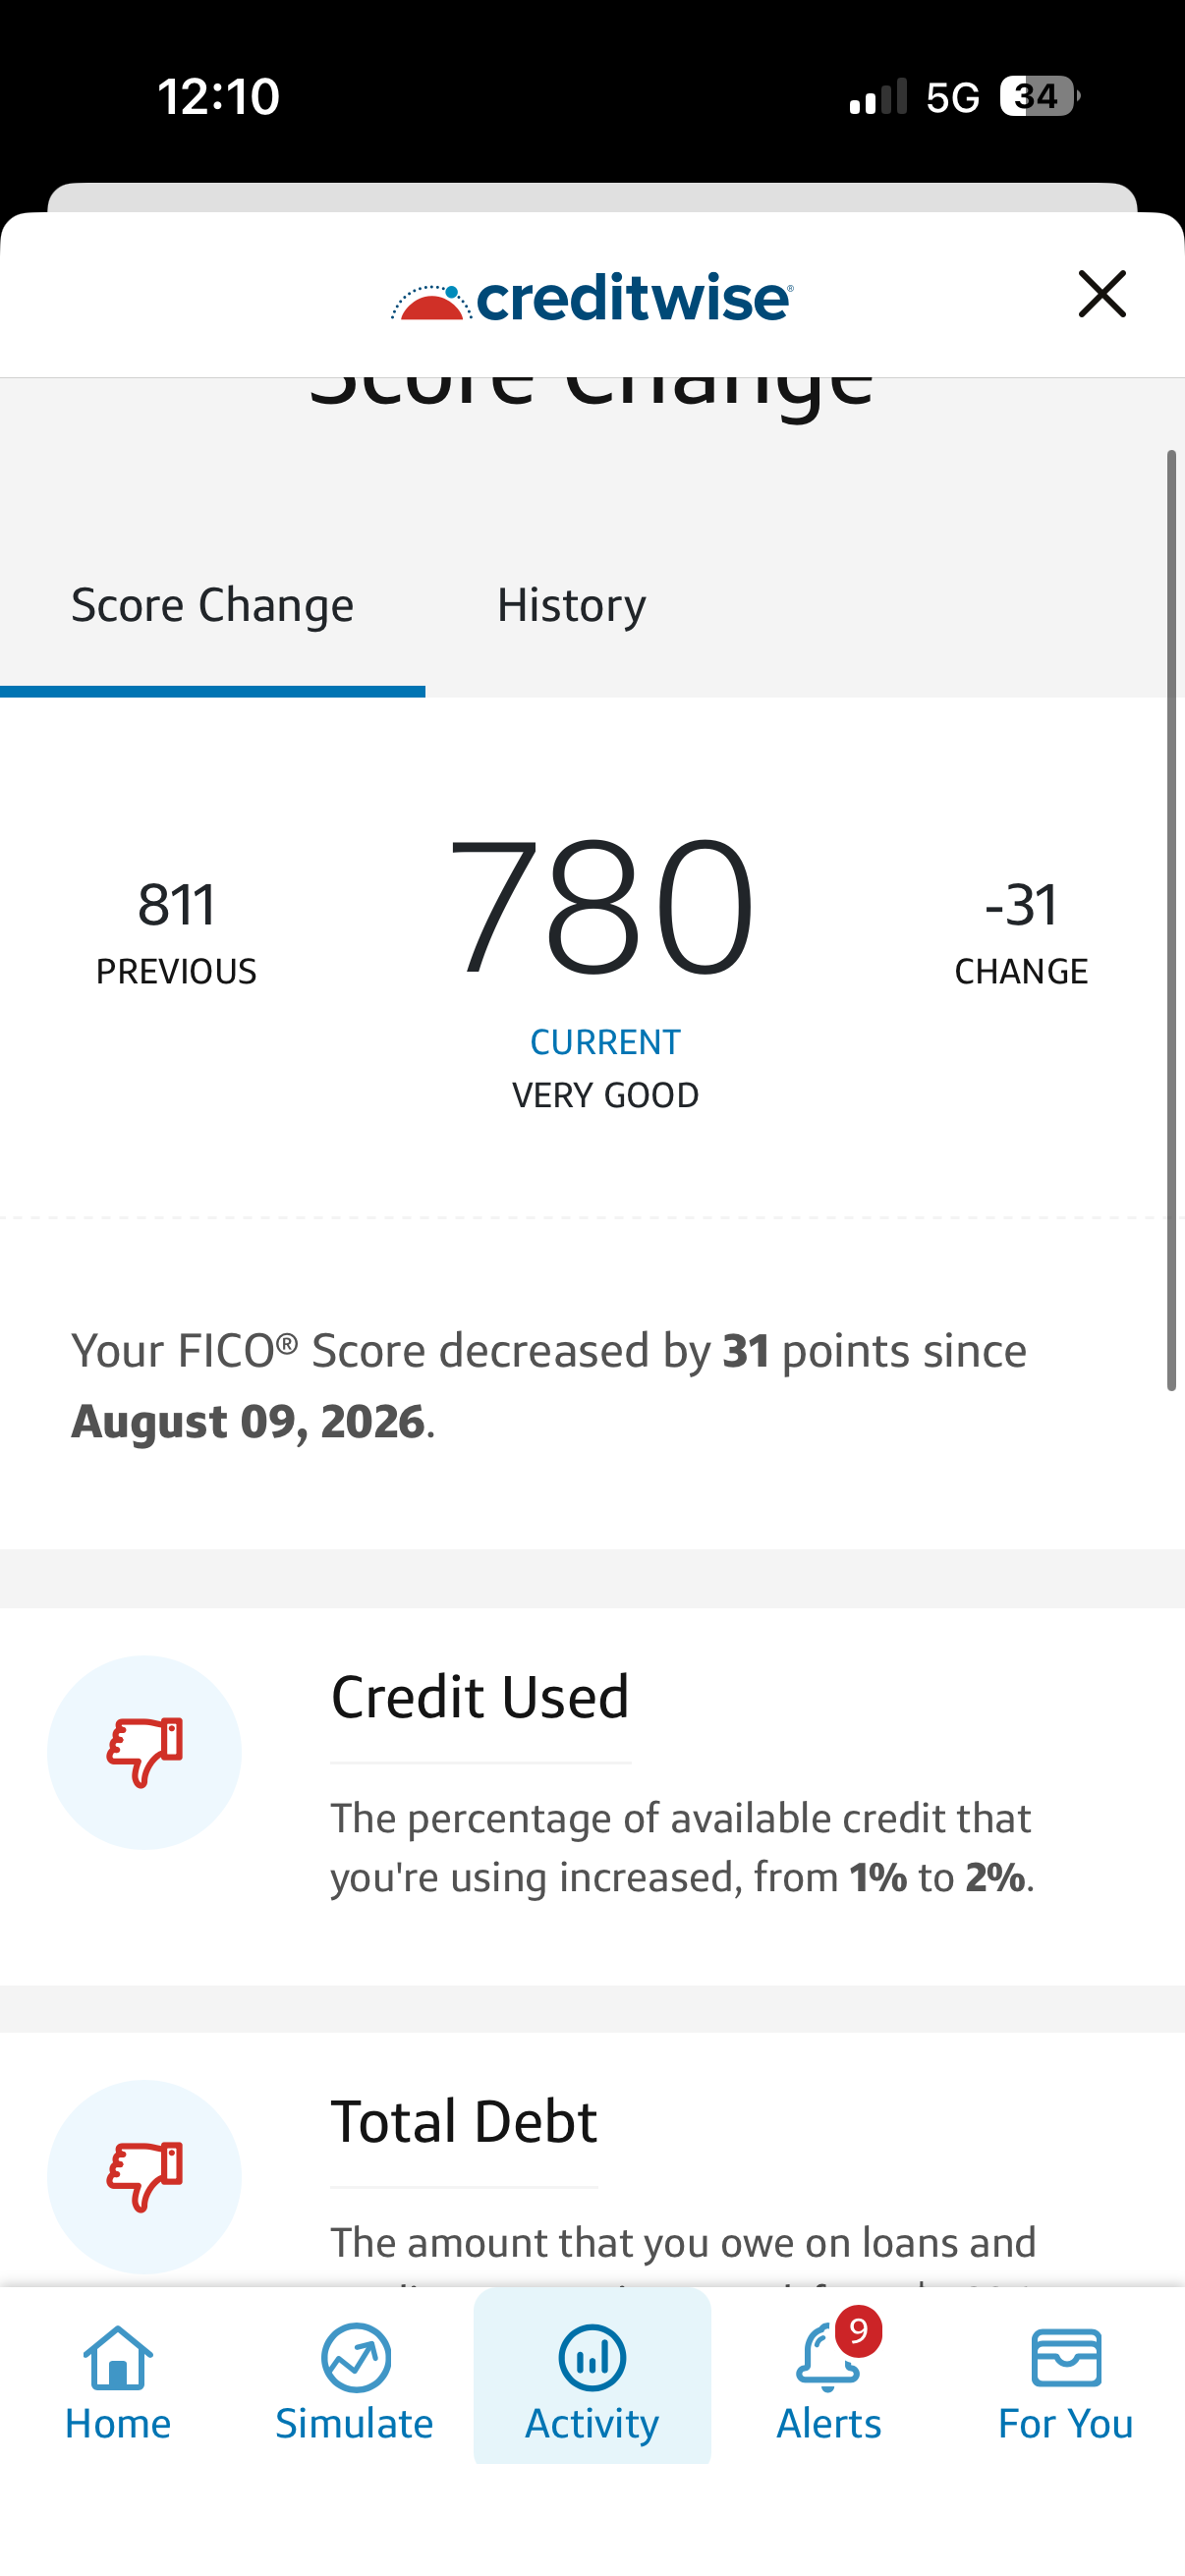
Screenshots our clients sent us after the denials stopped
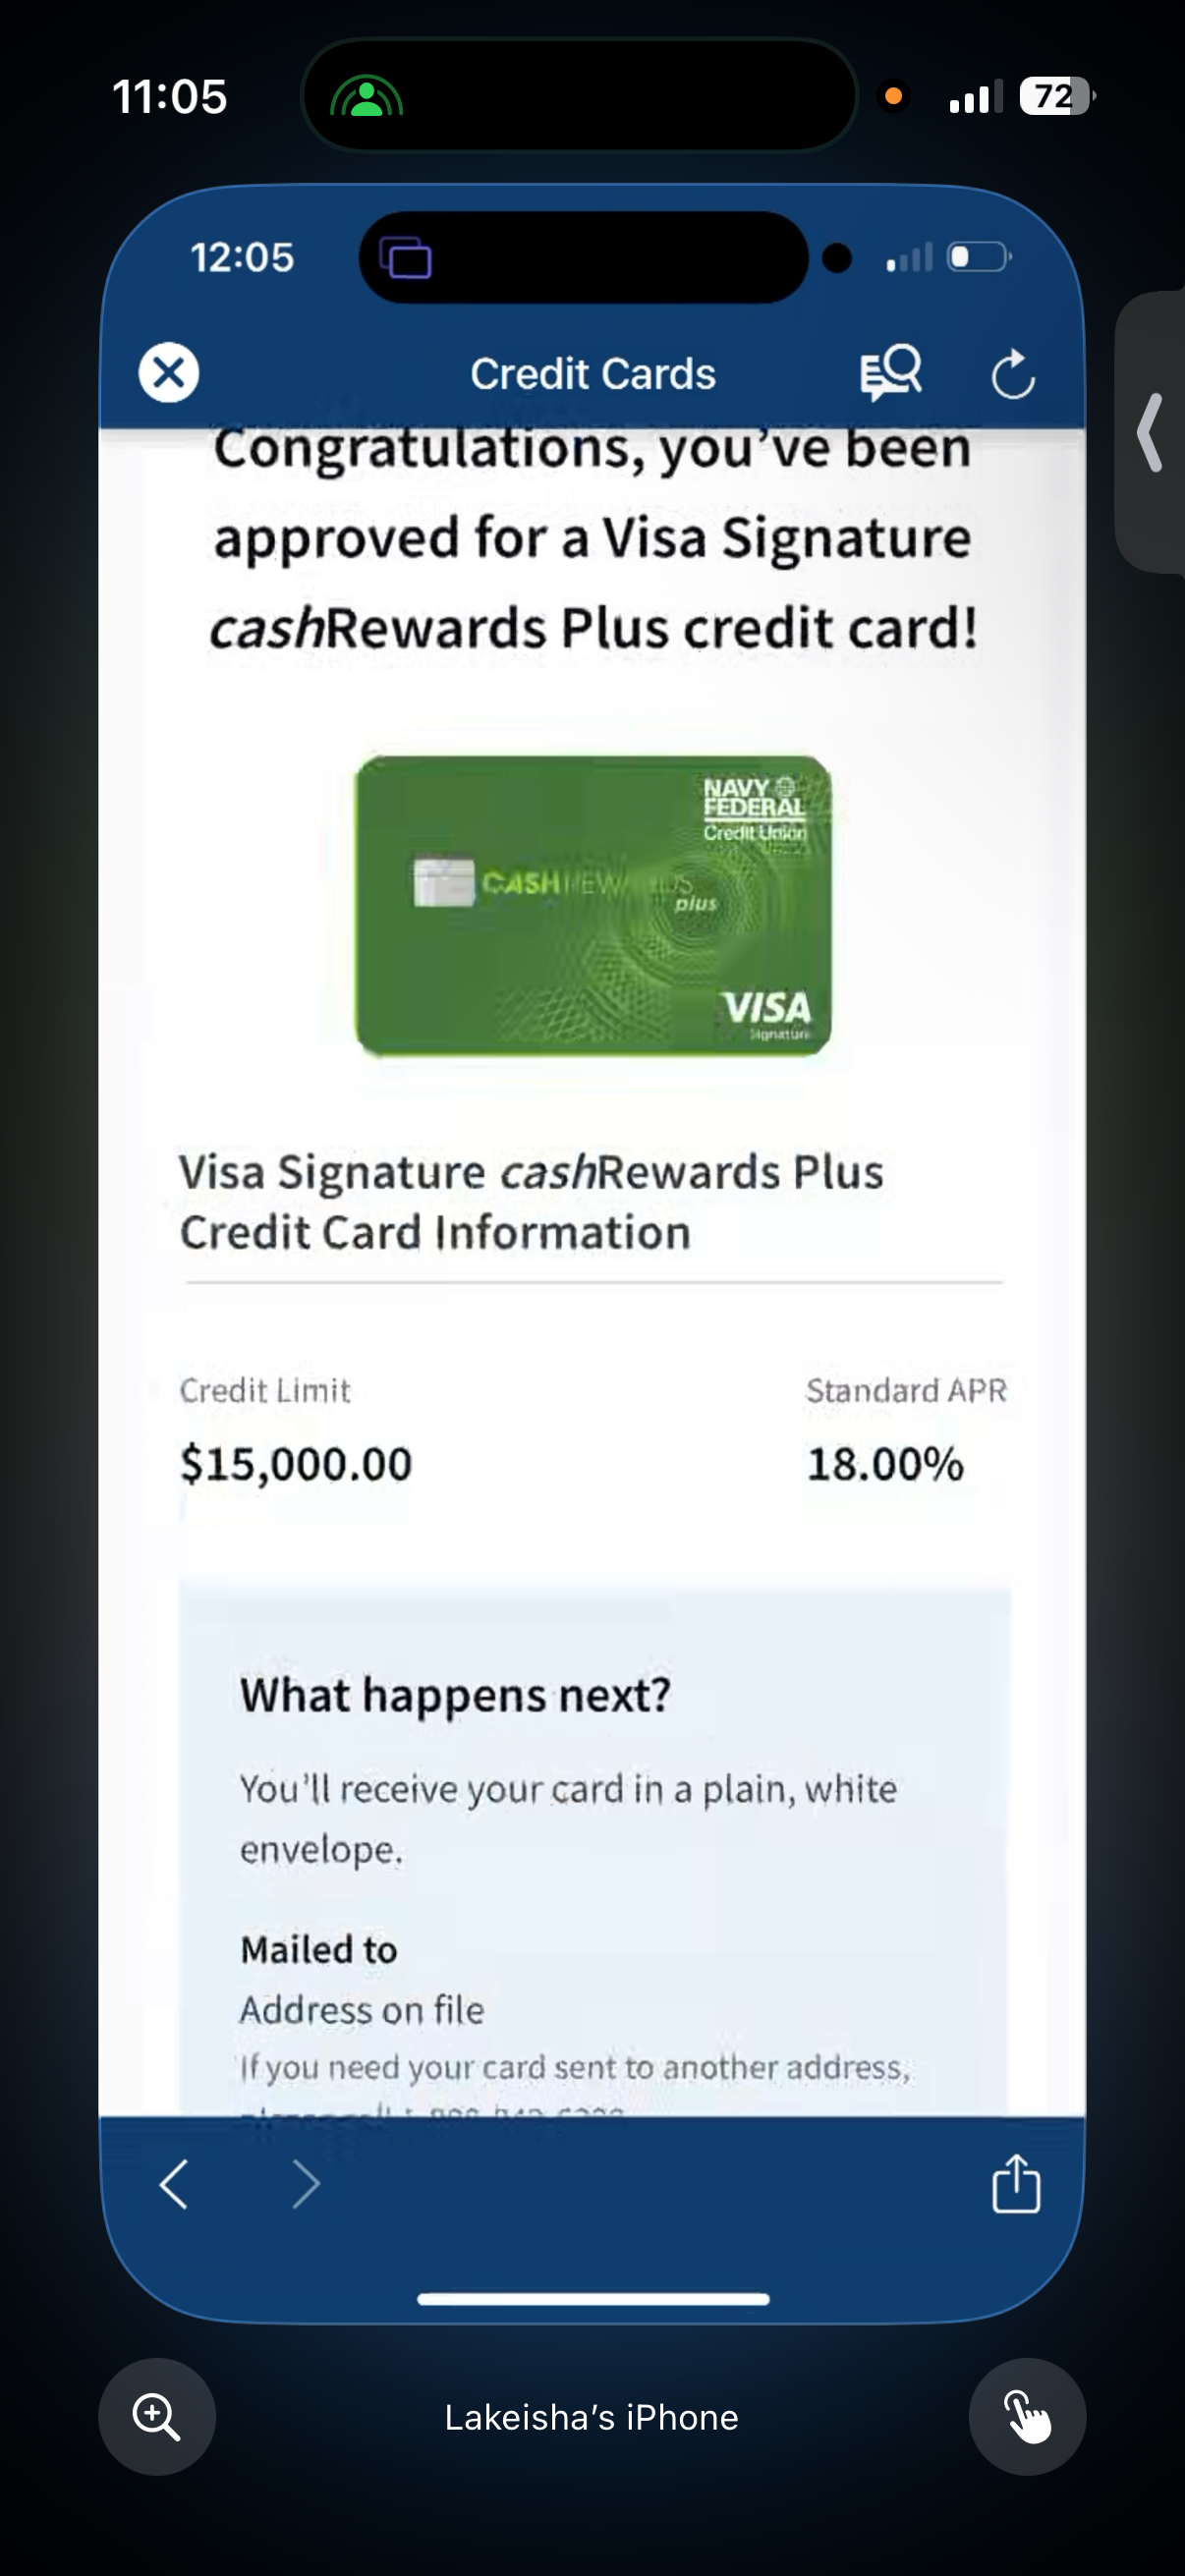
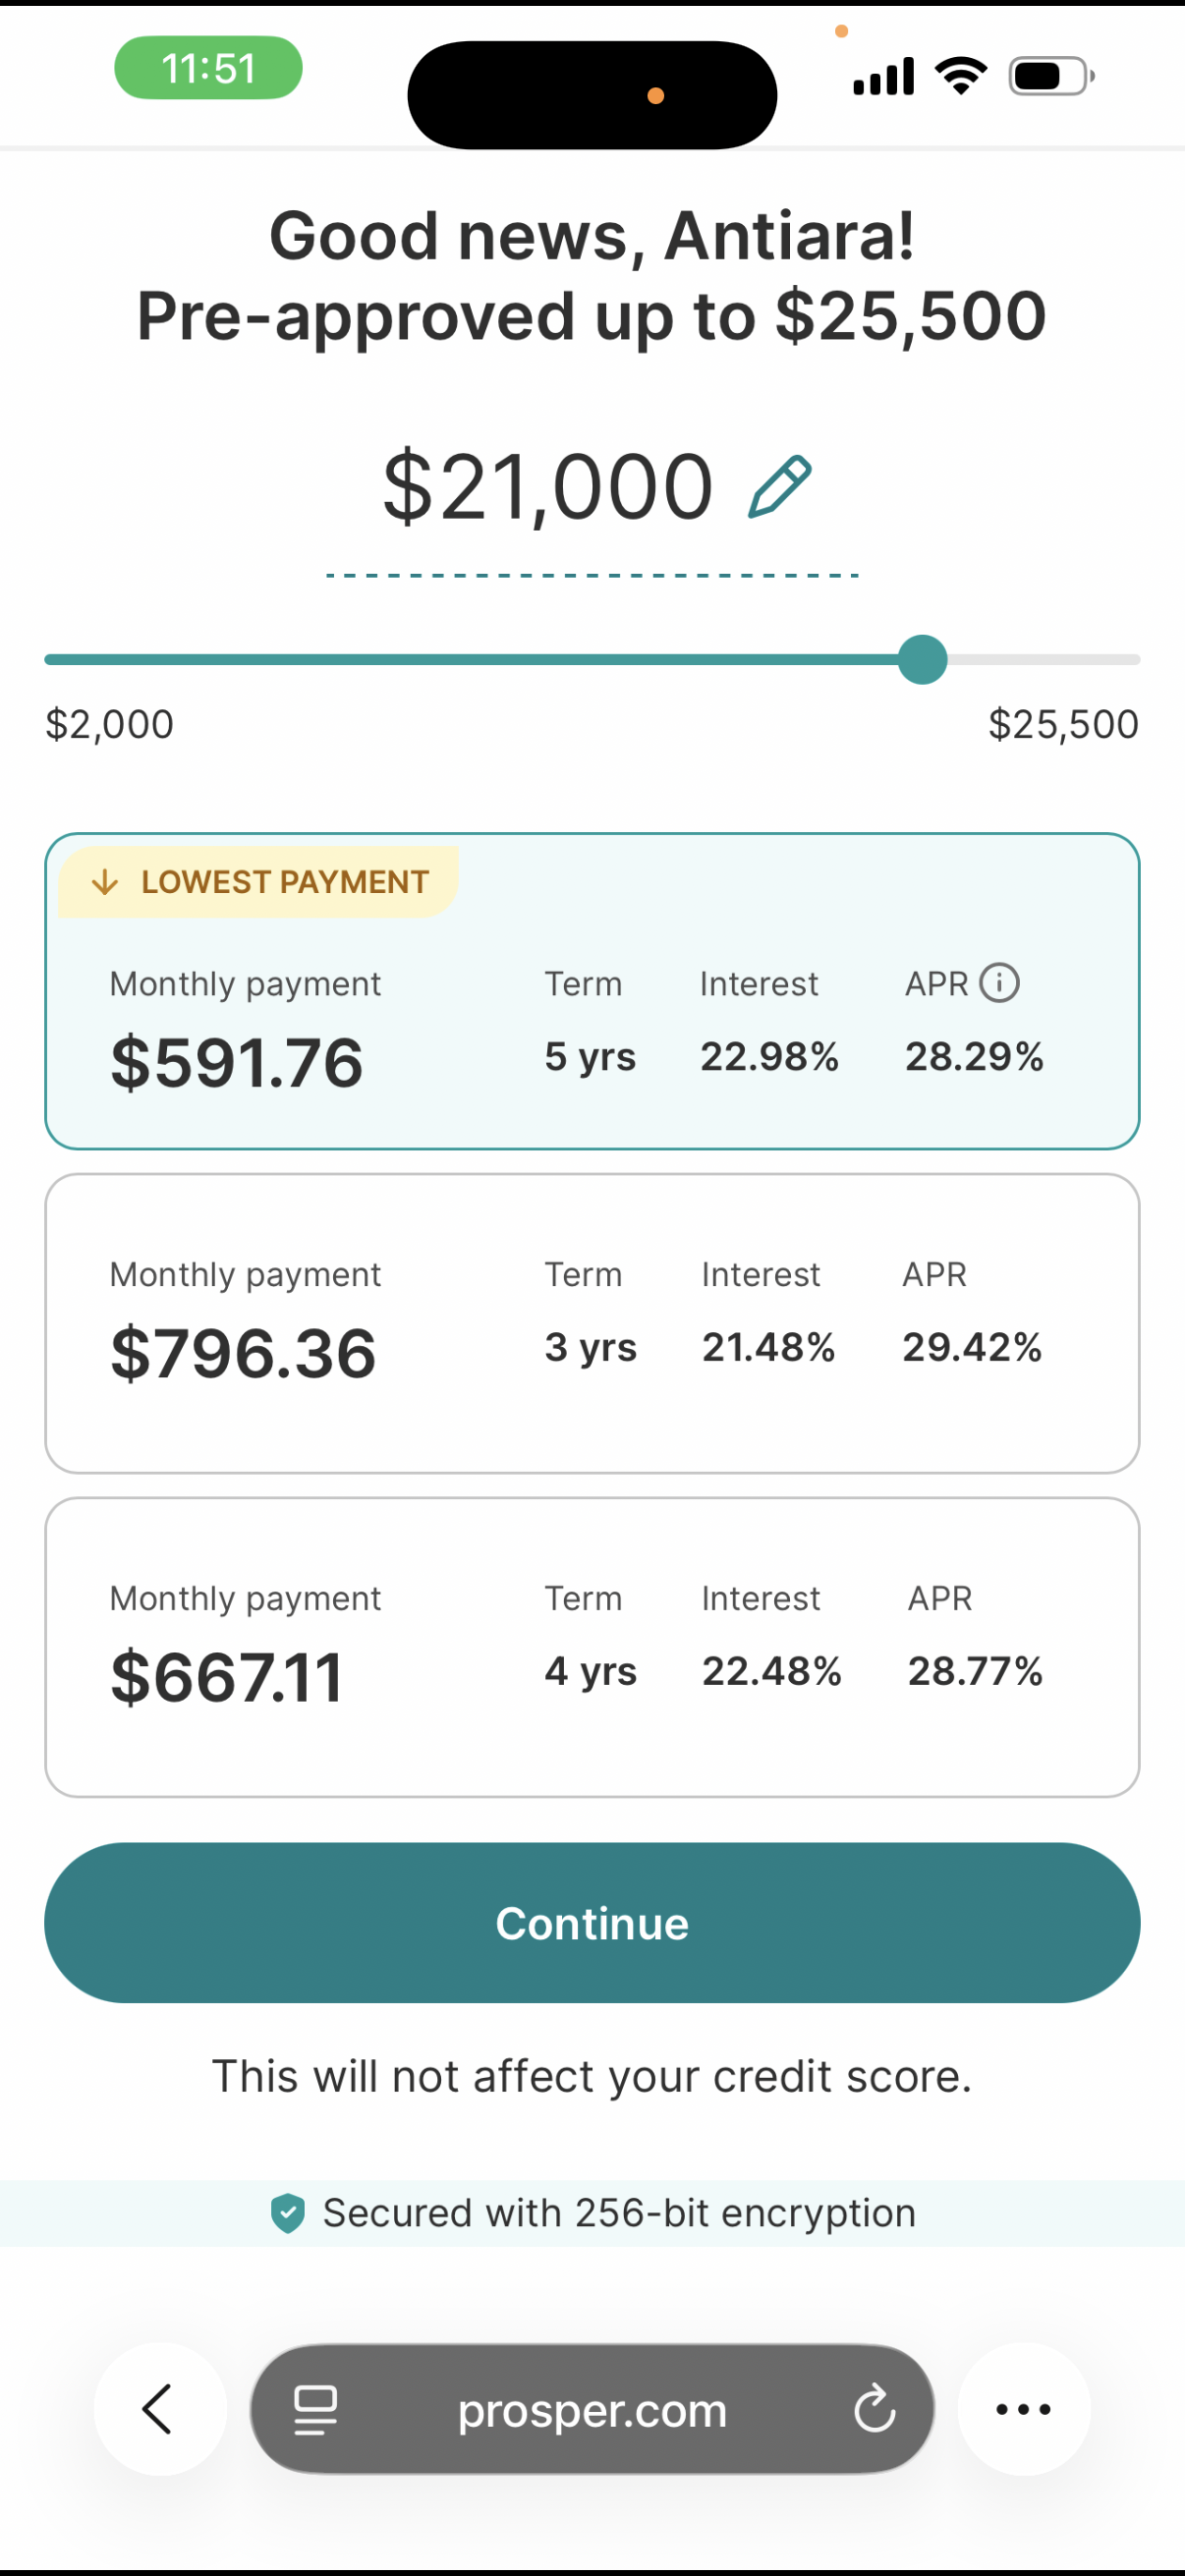
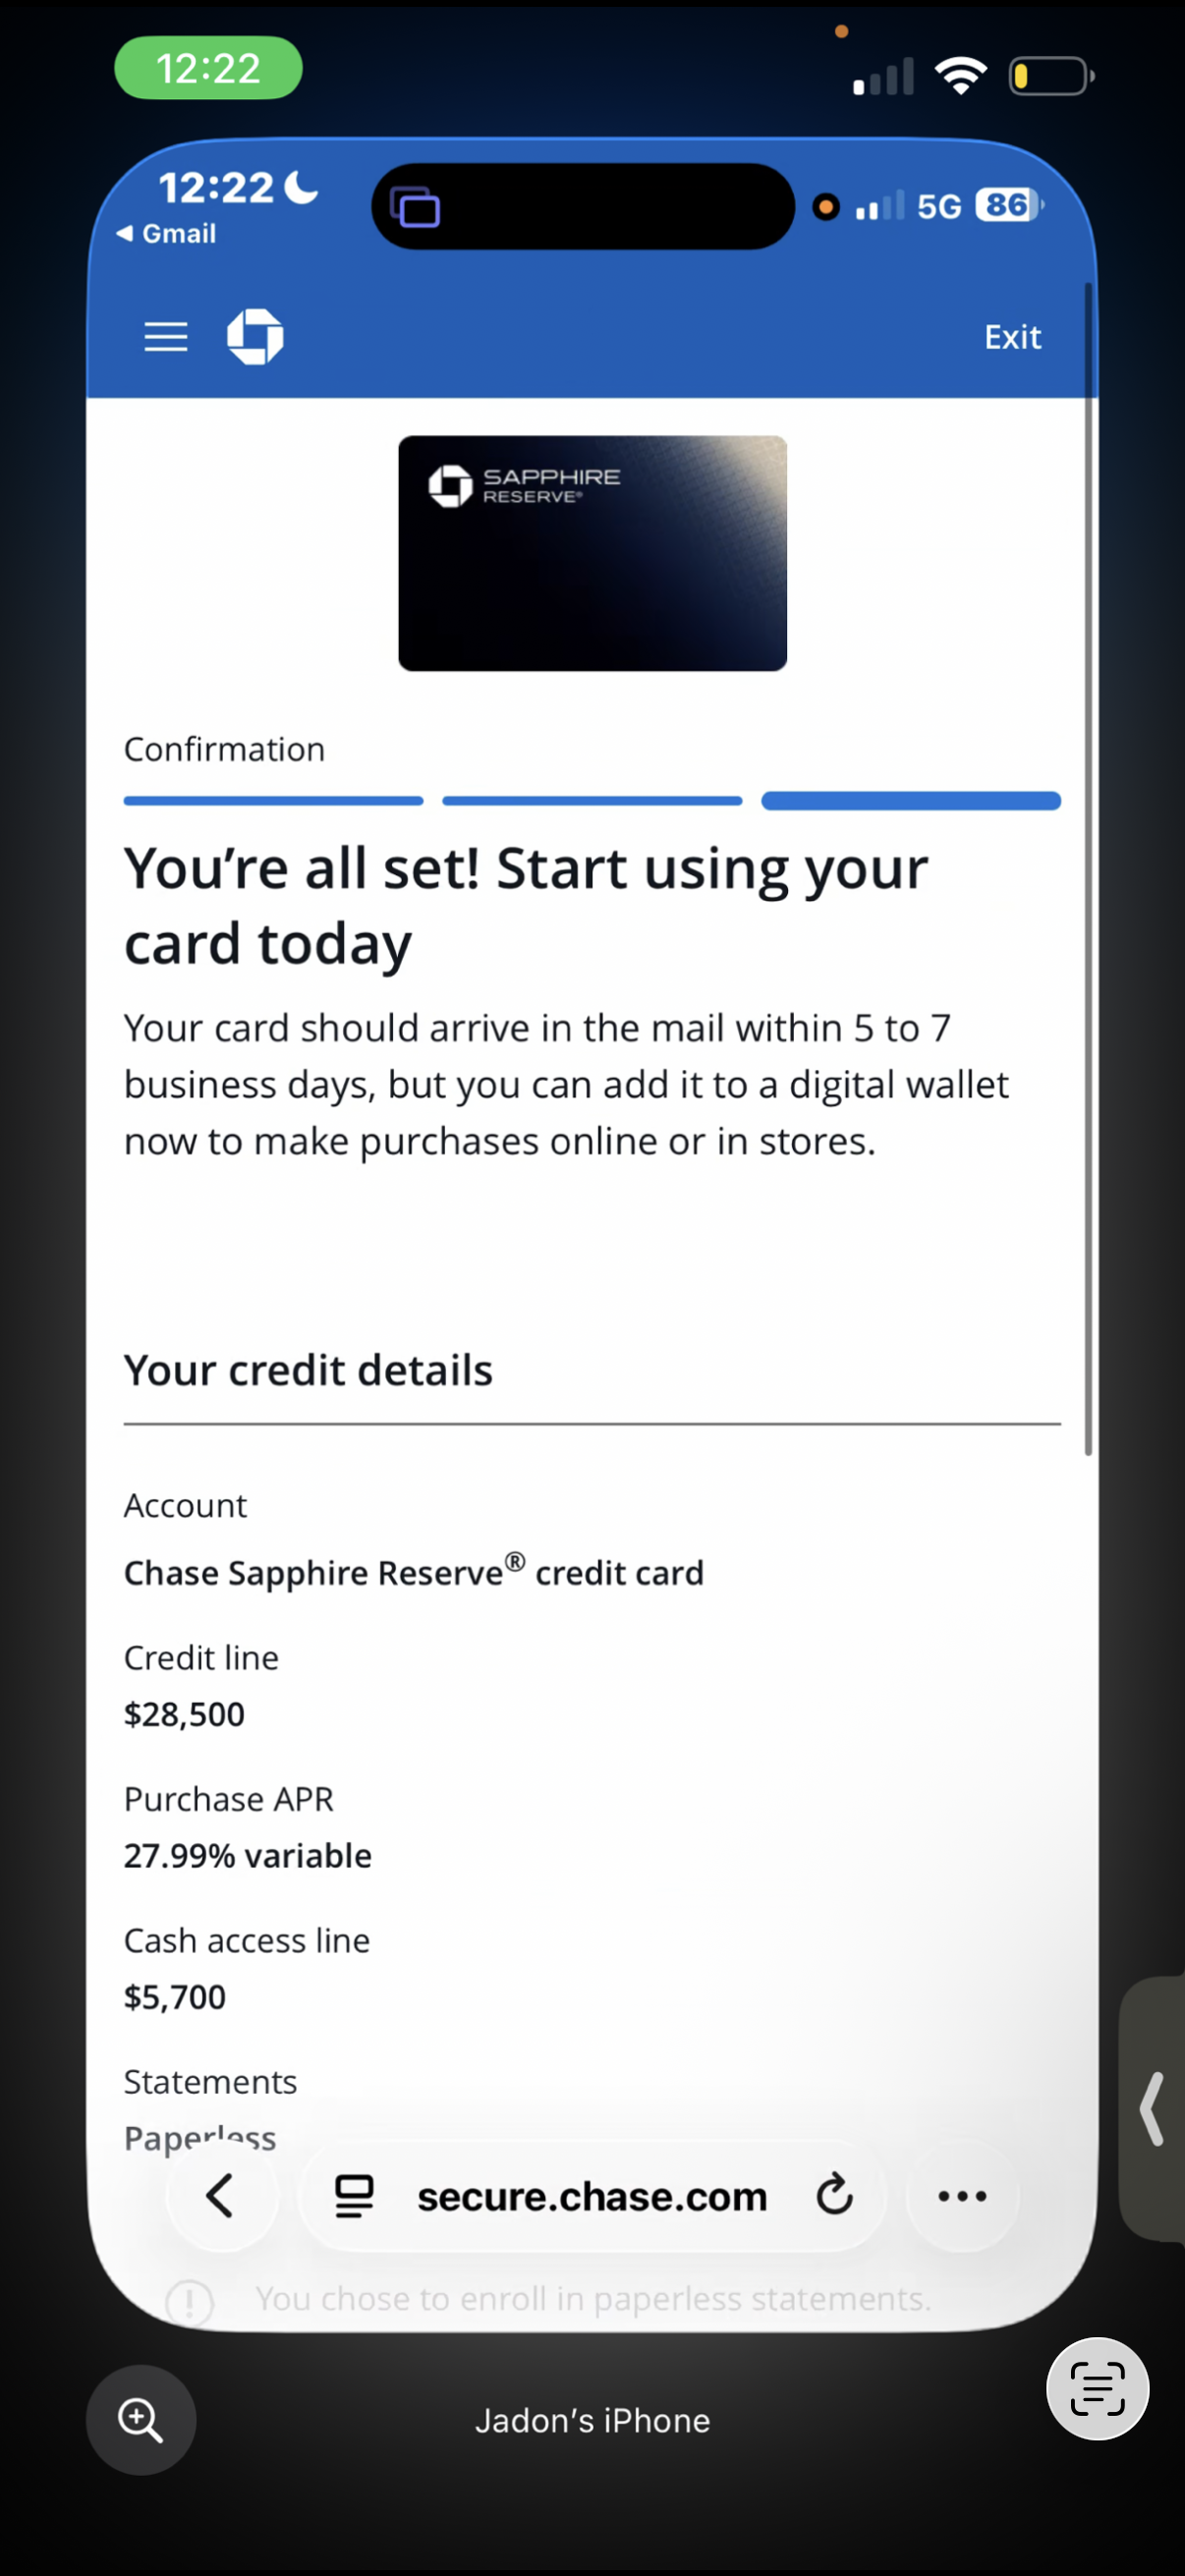
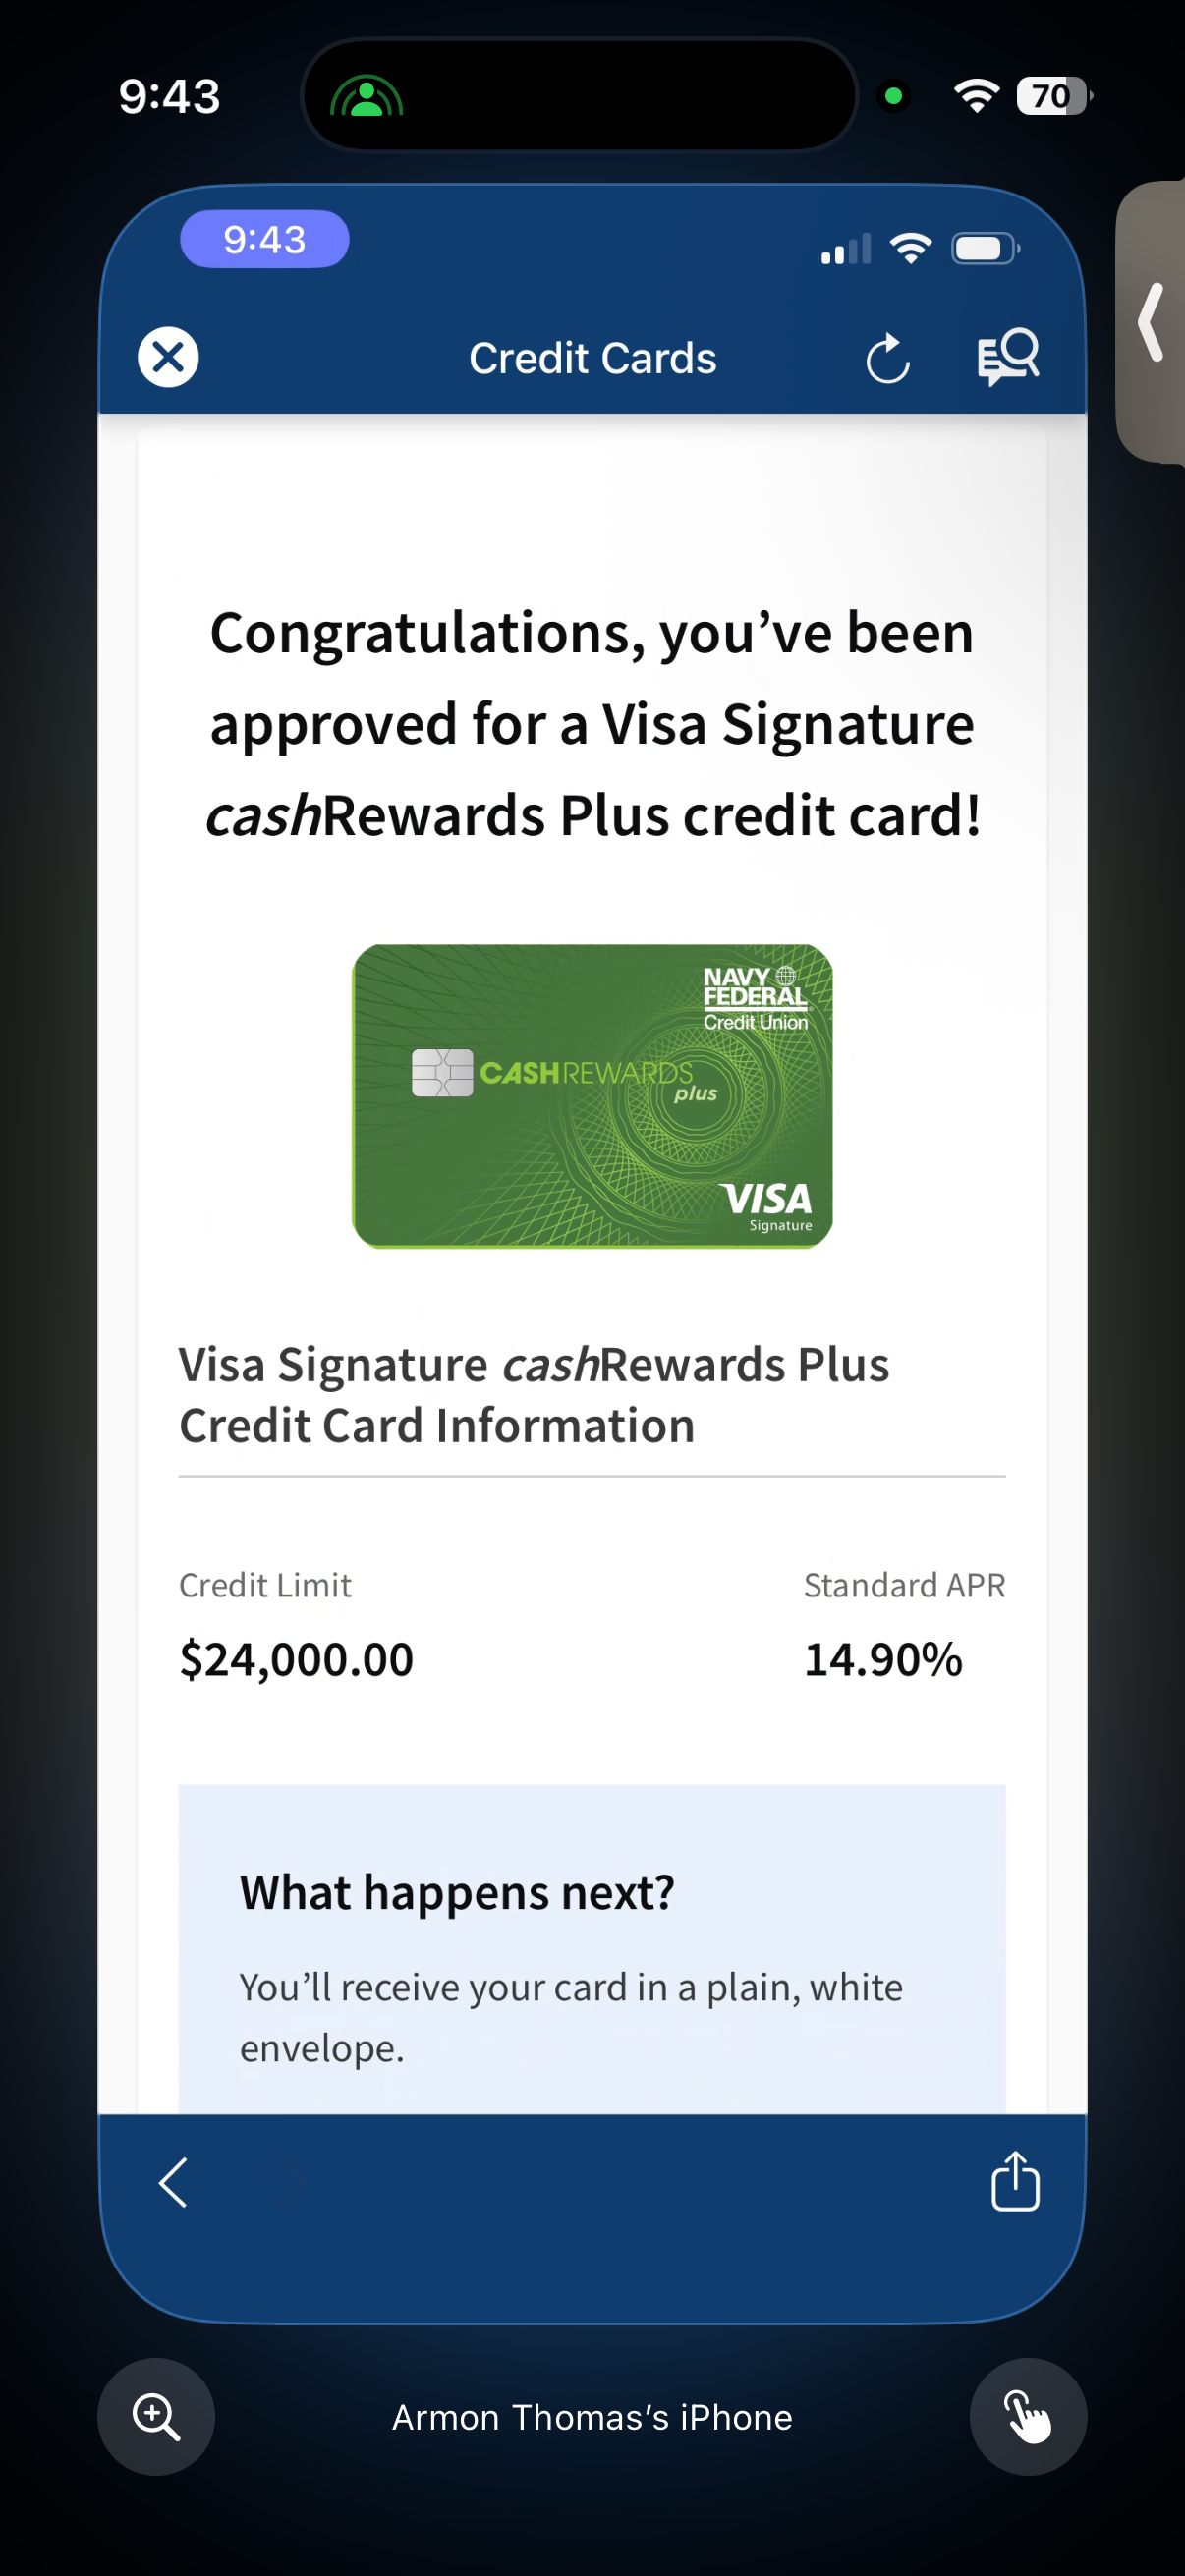
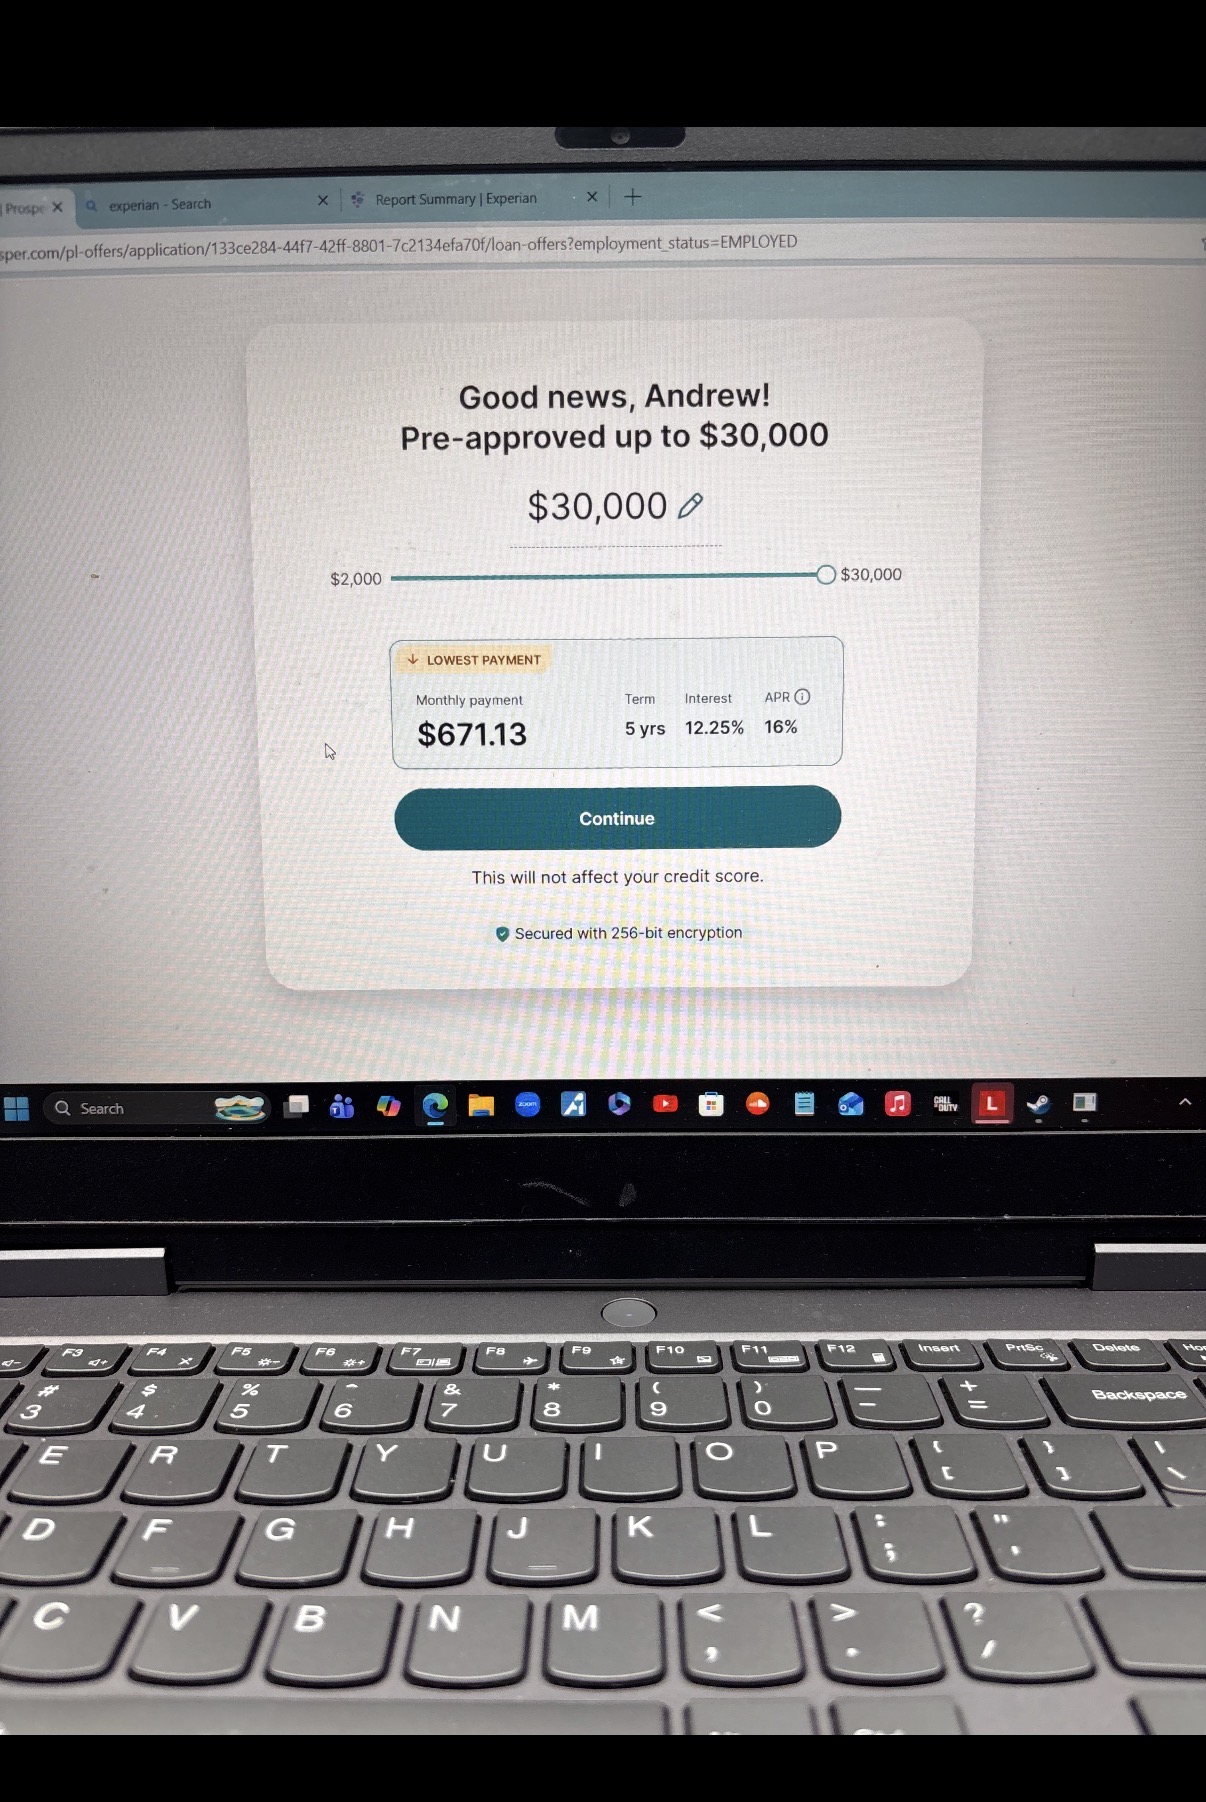
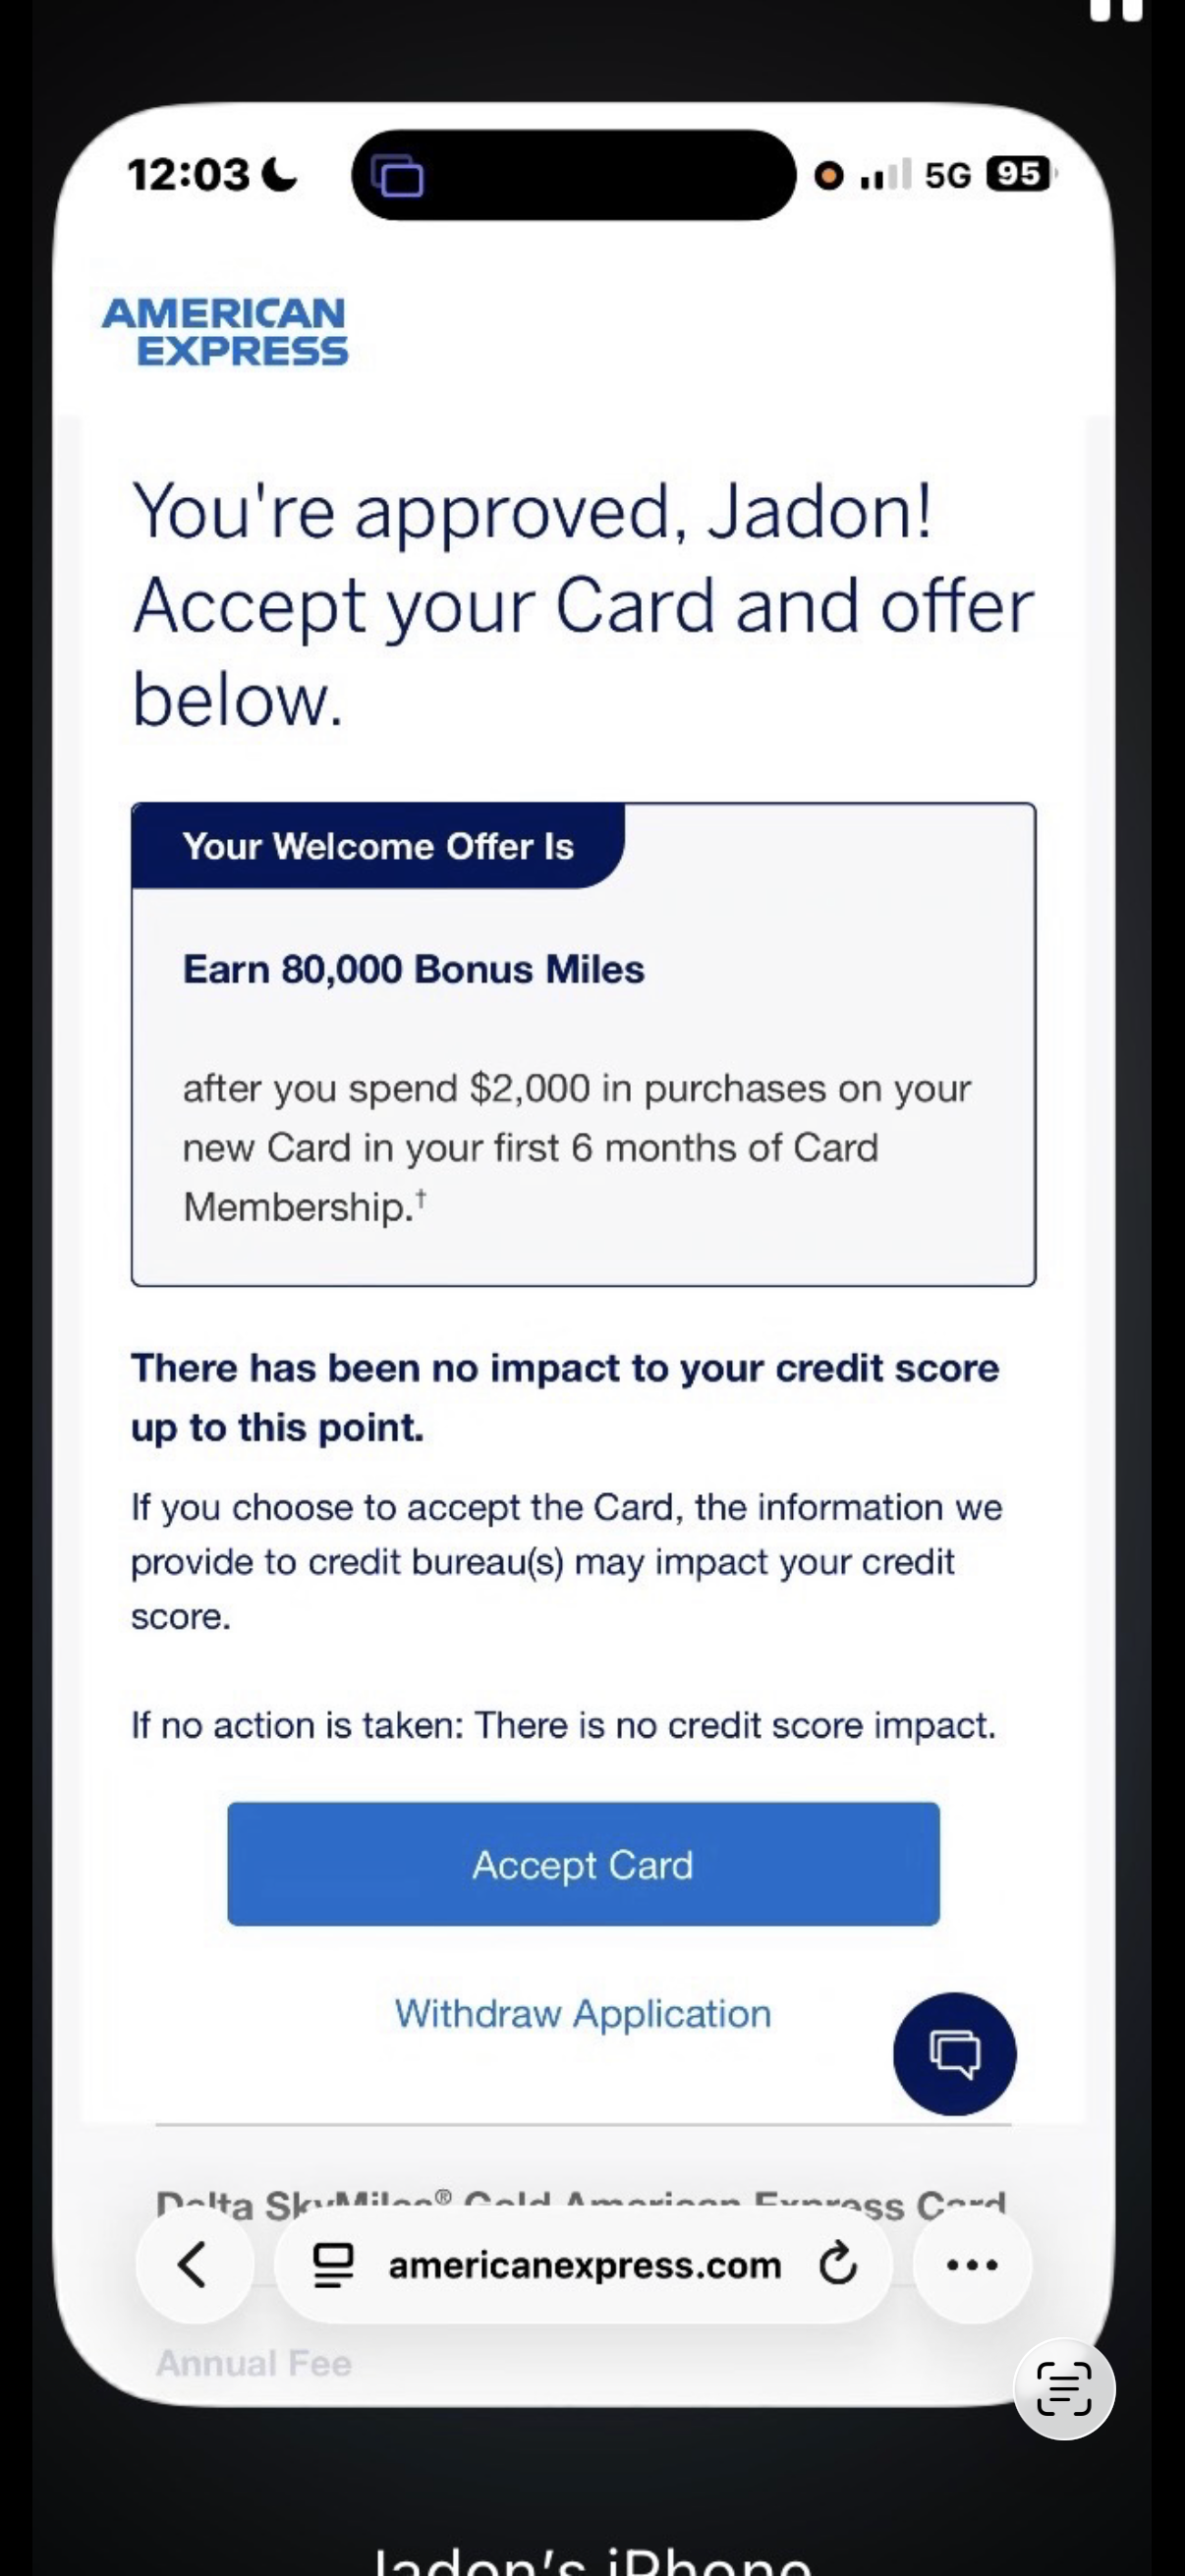
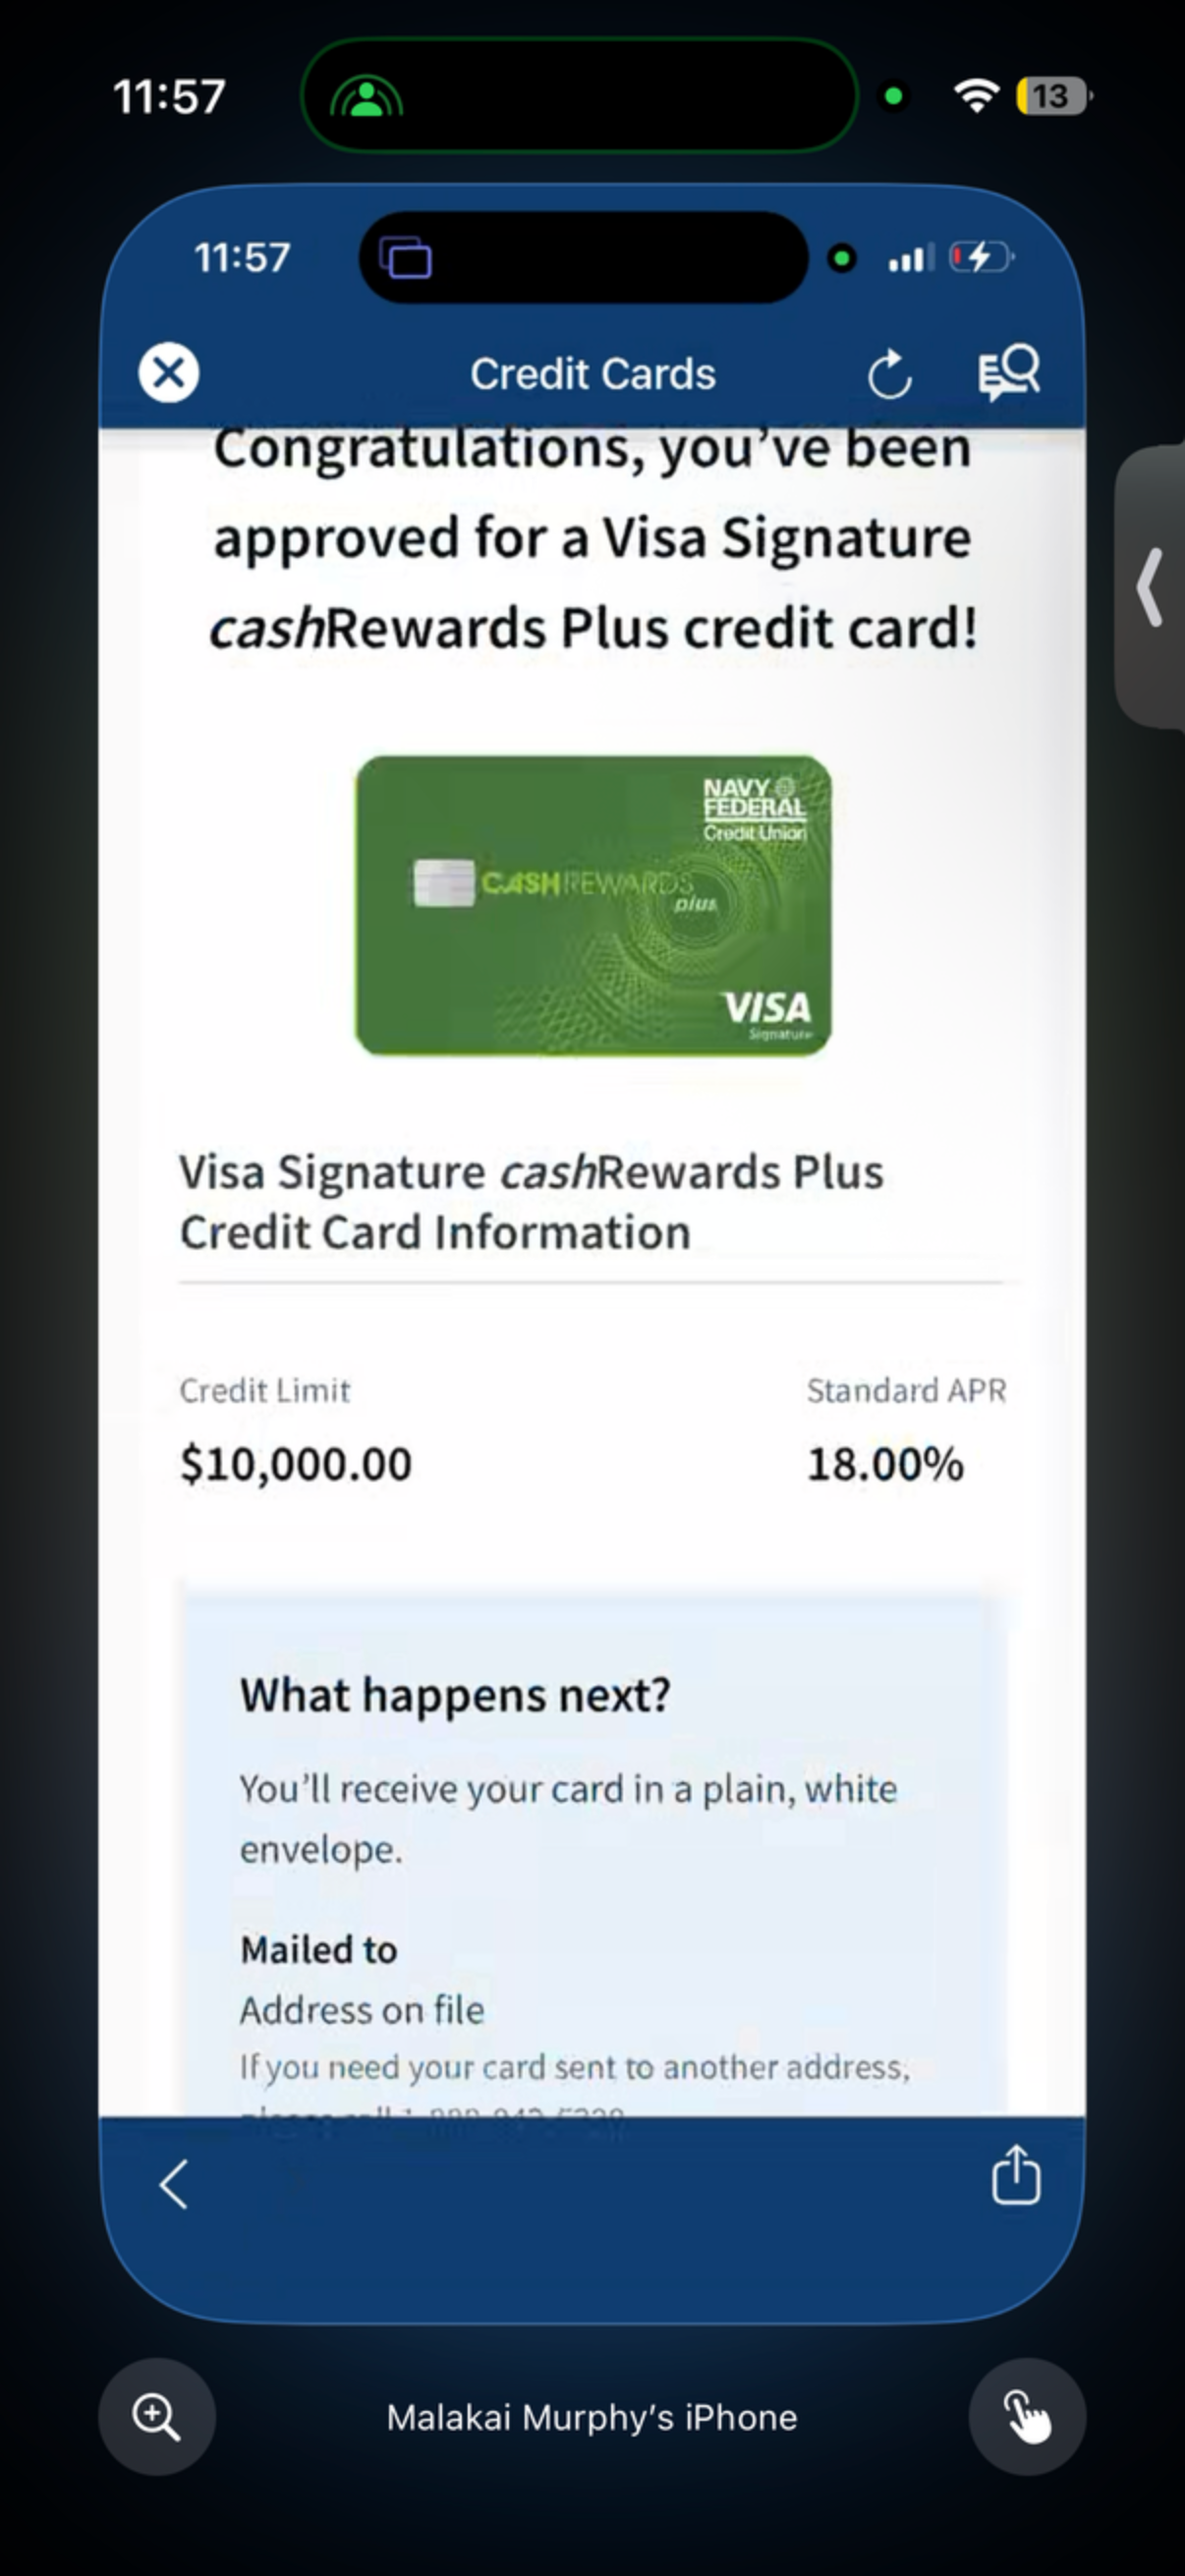
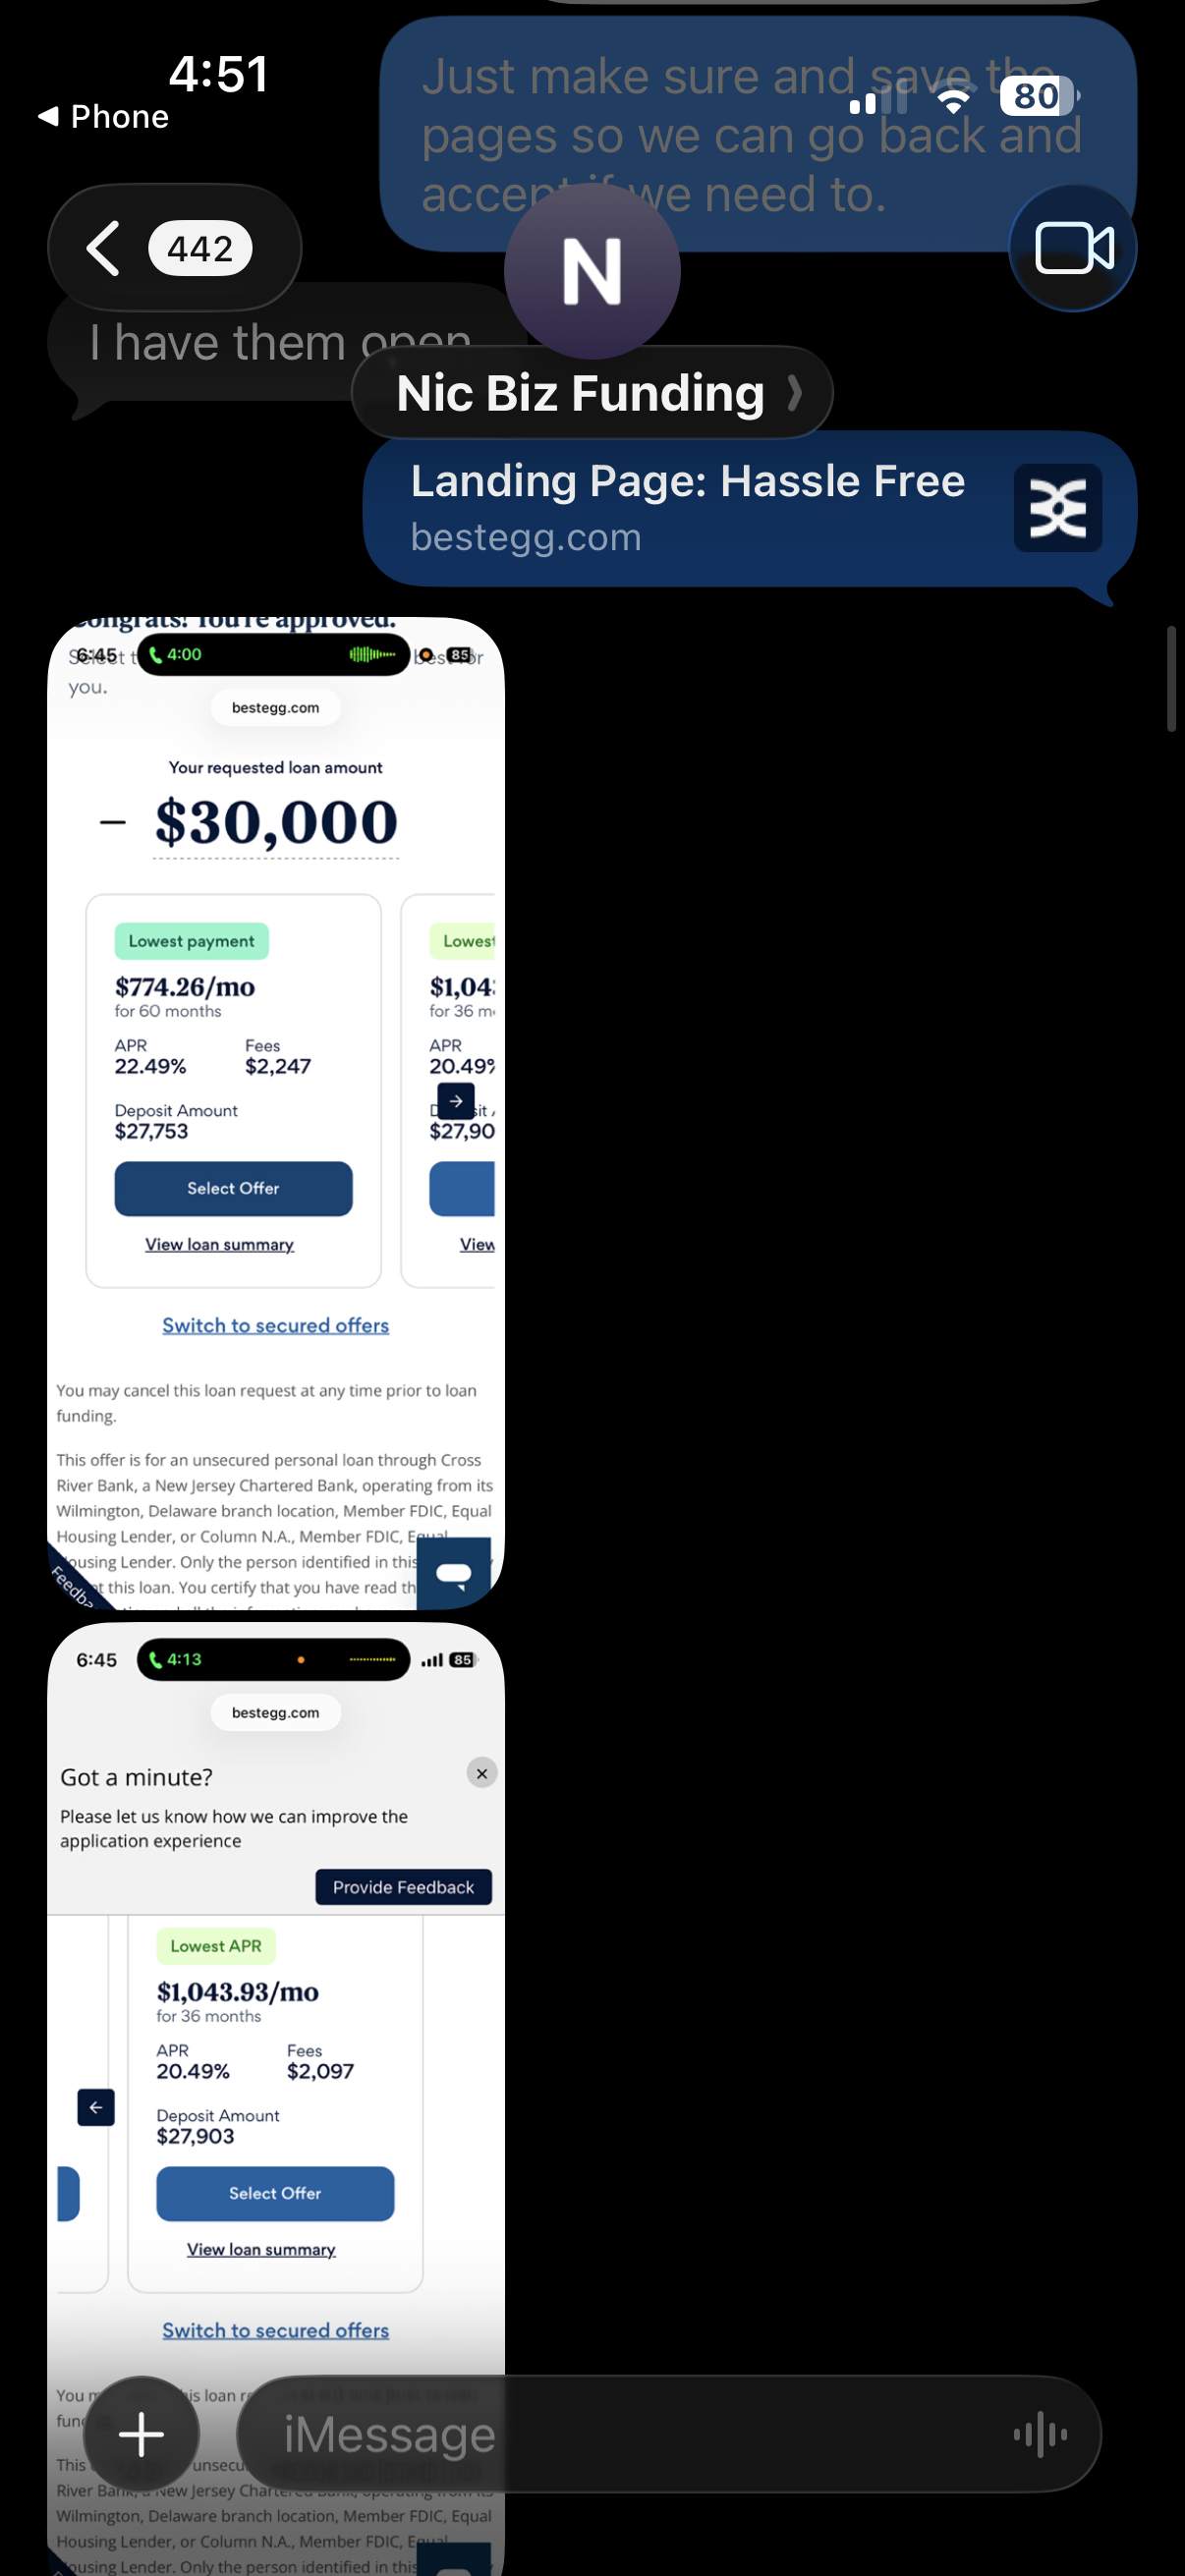
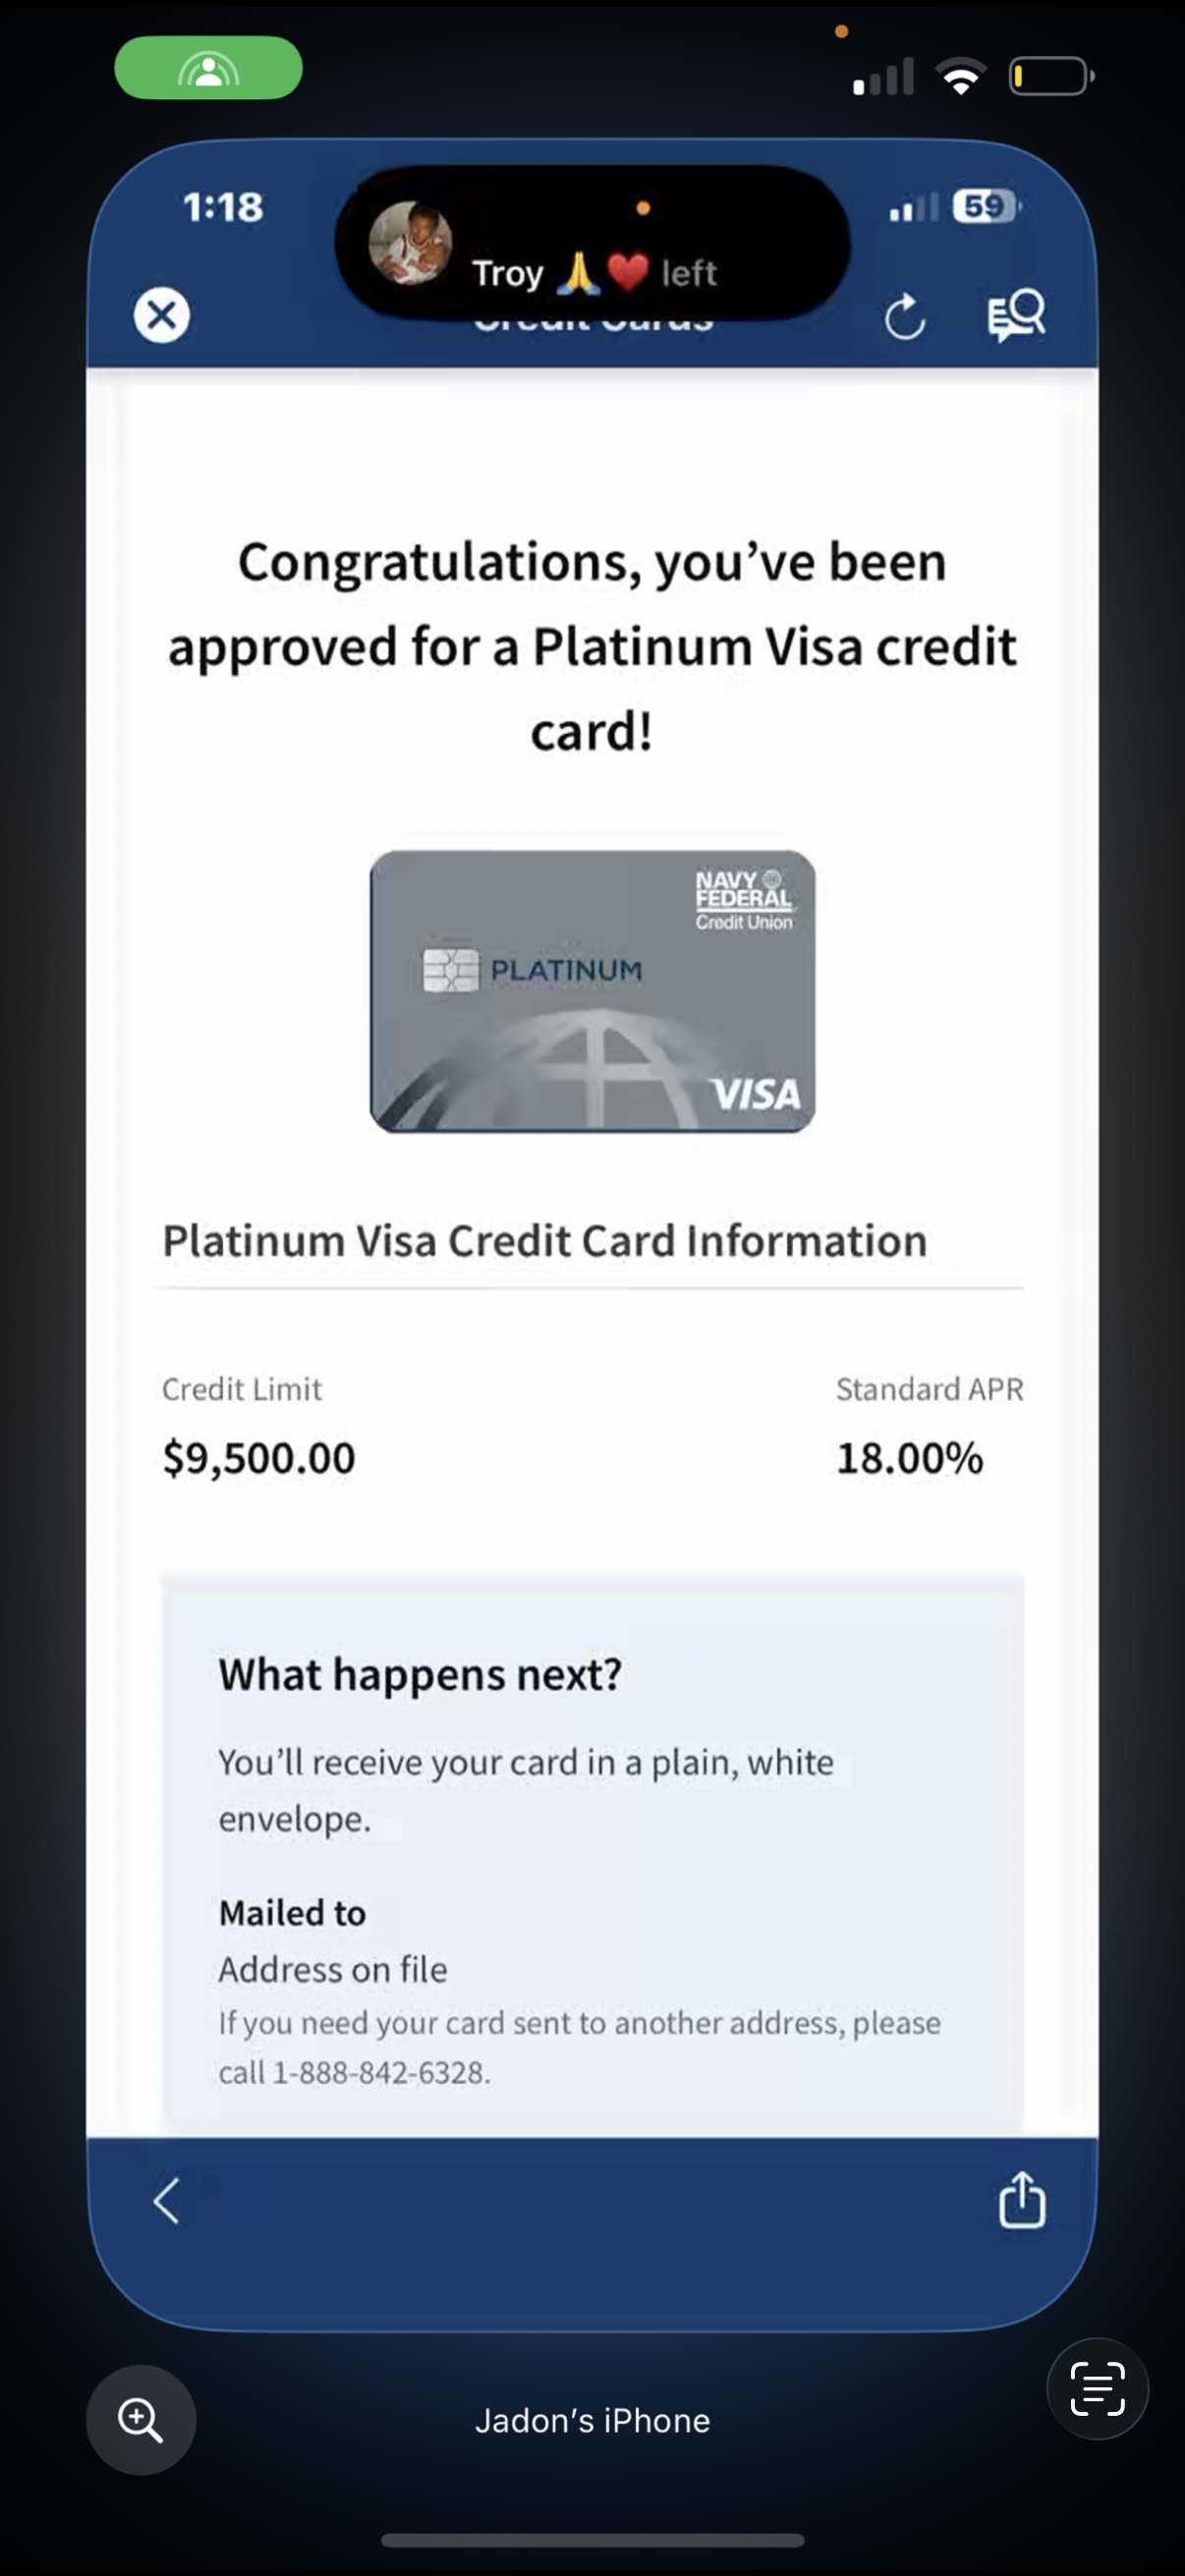
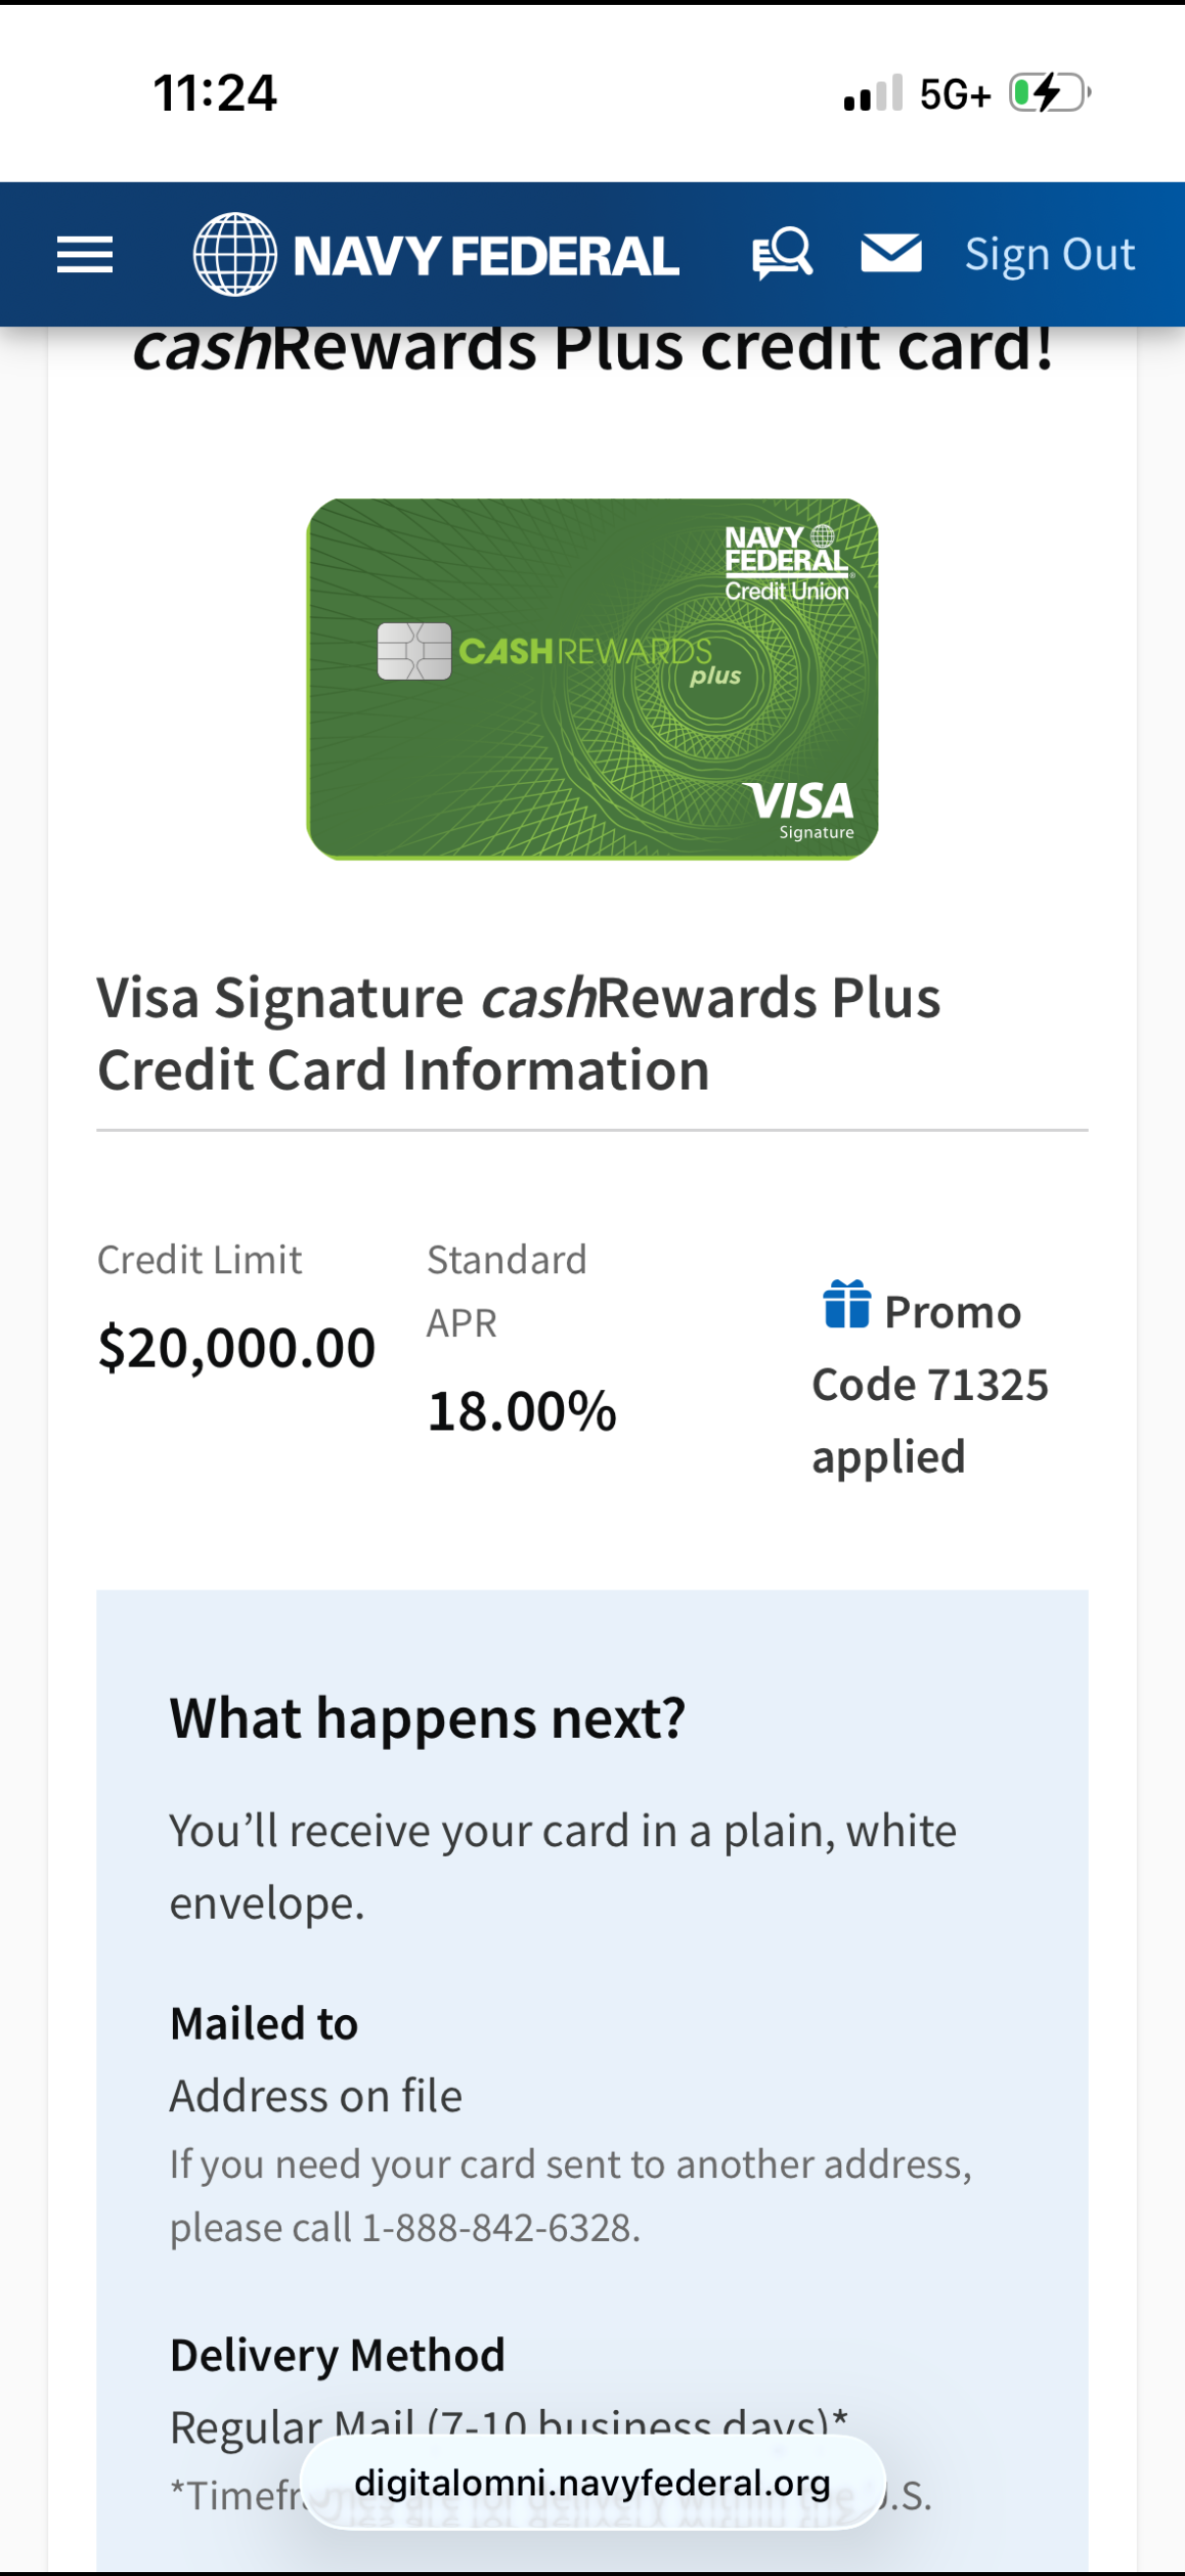
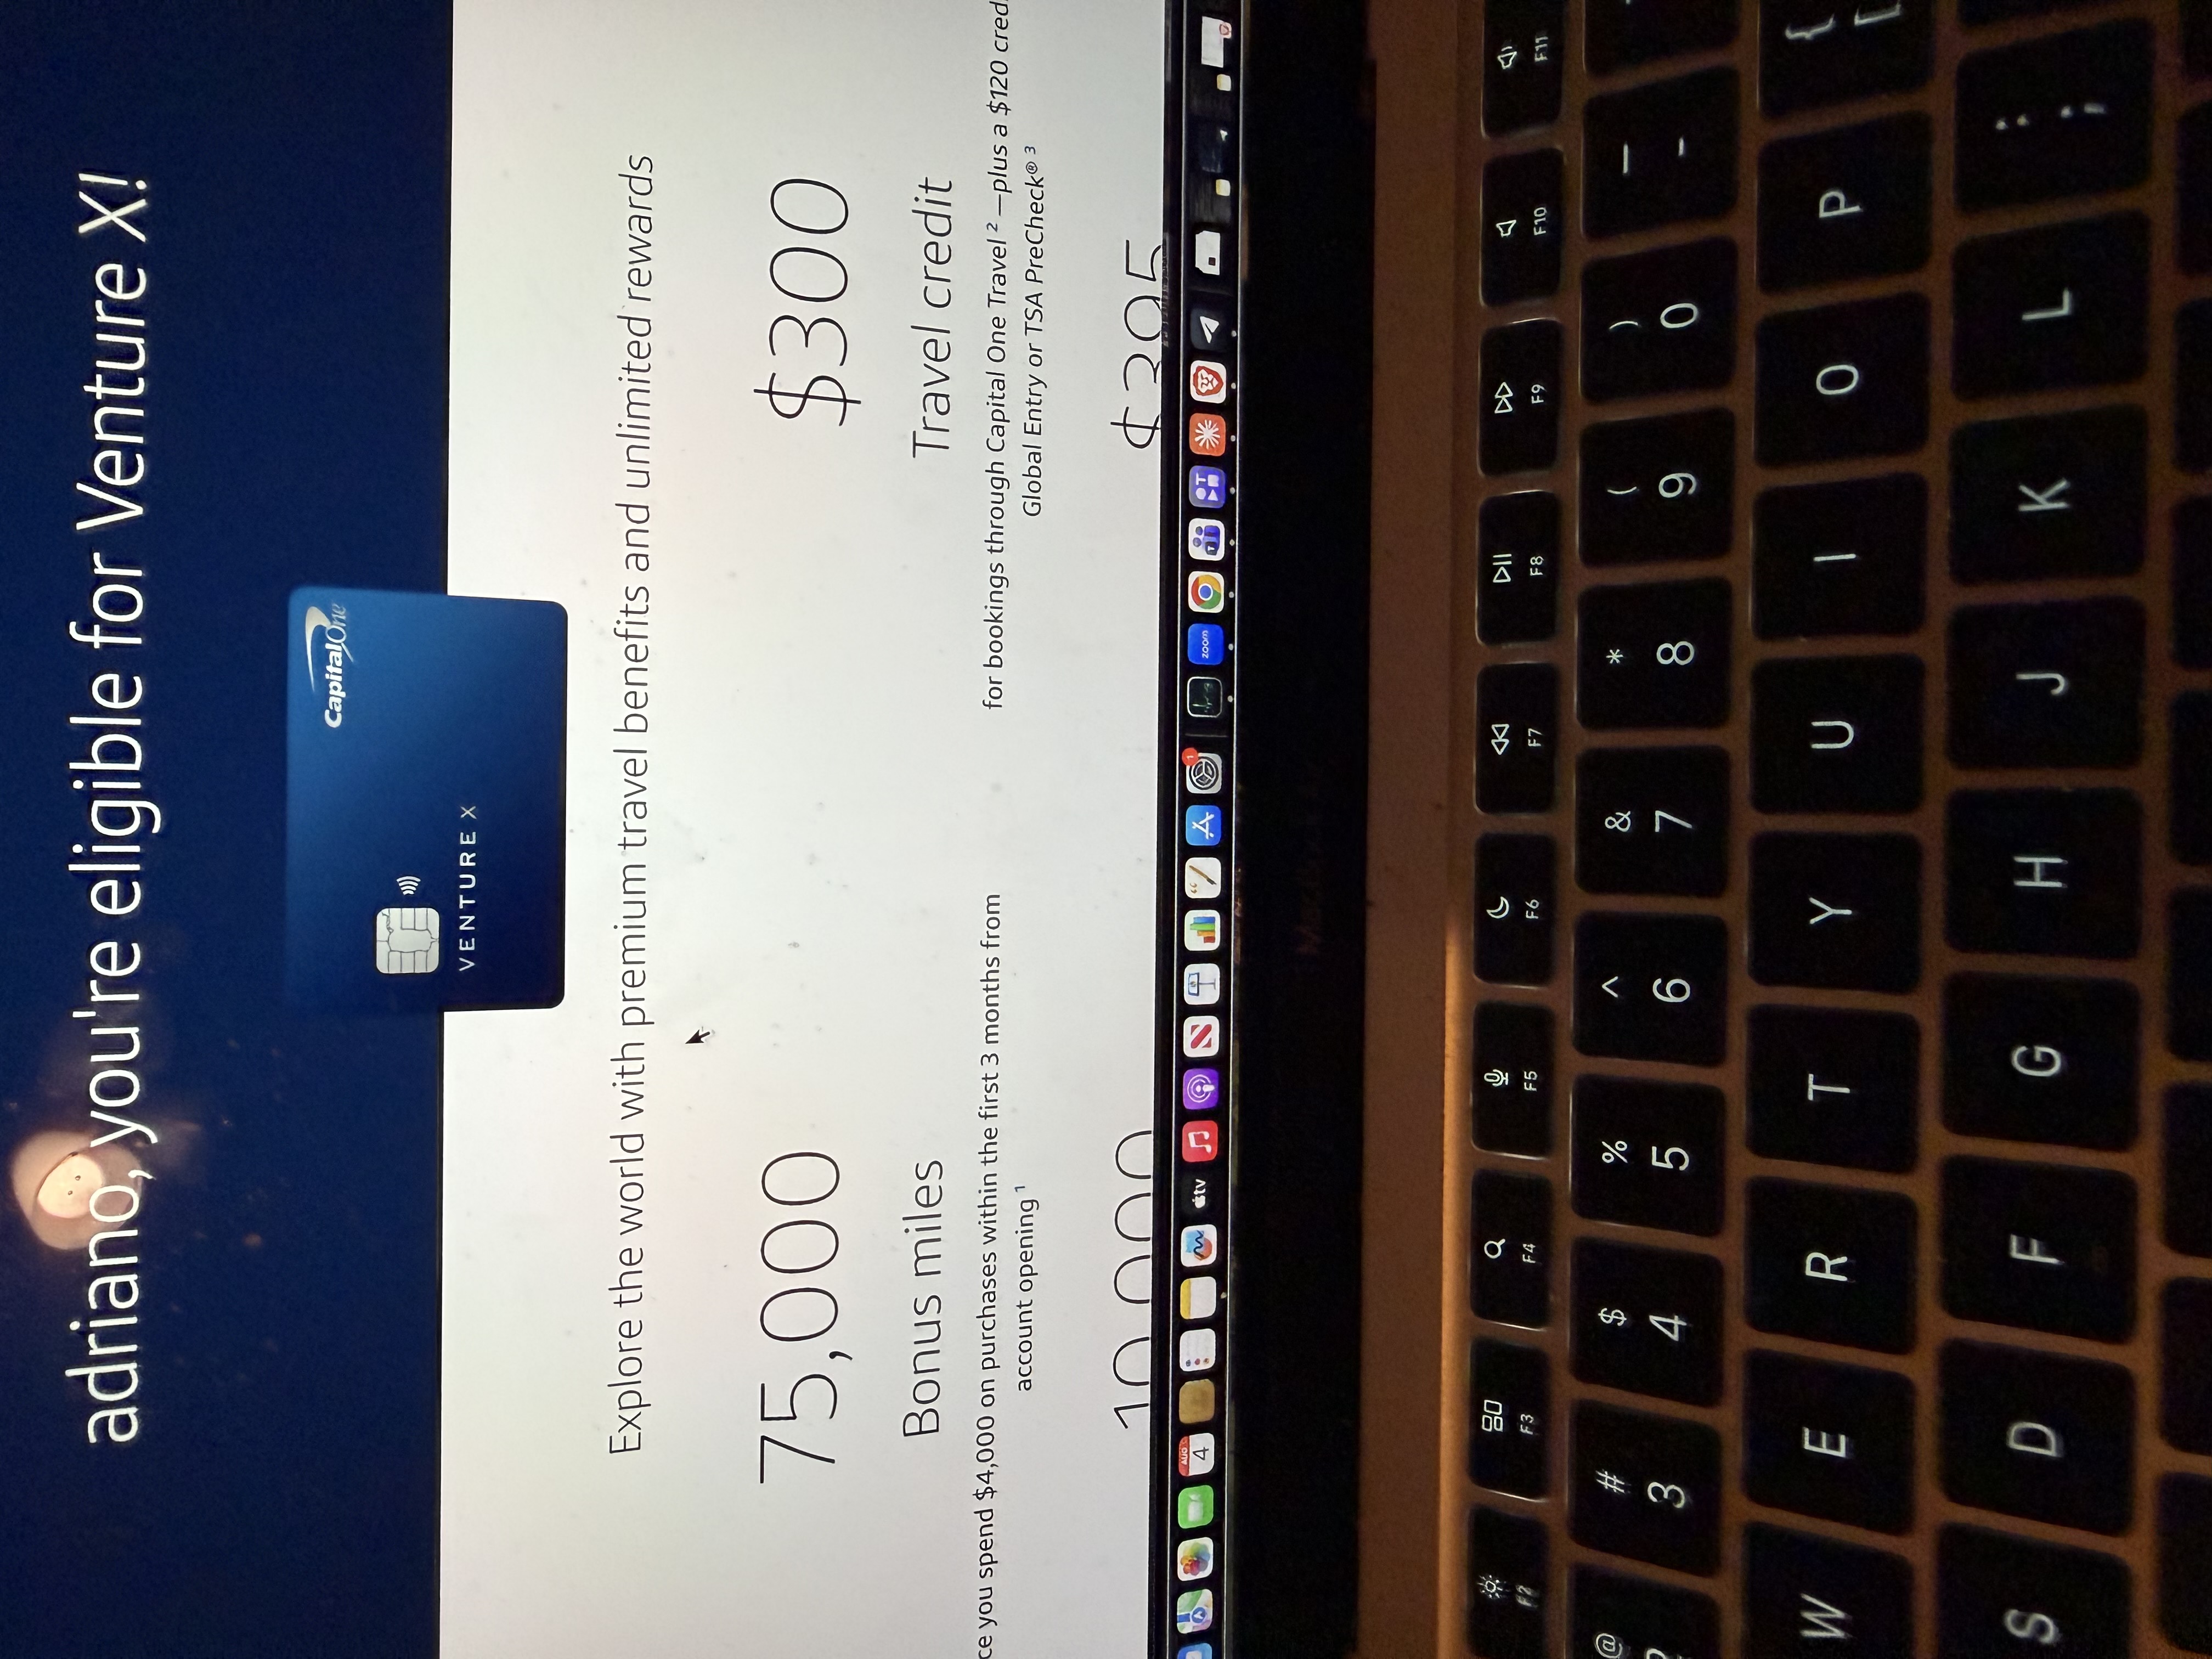
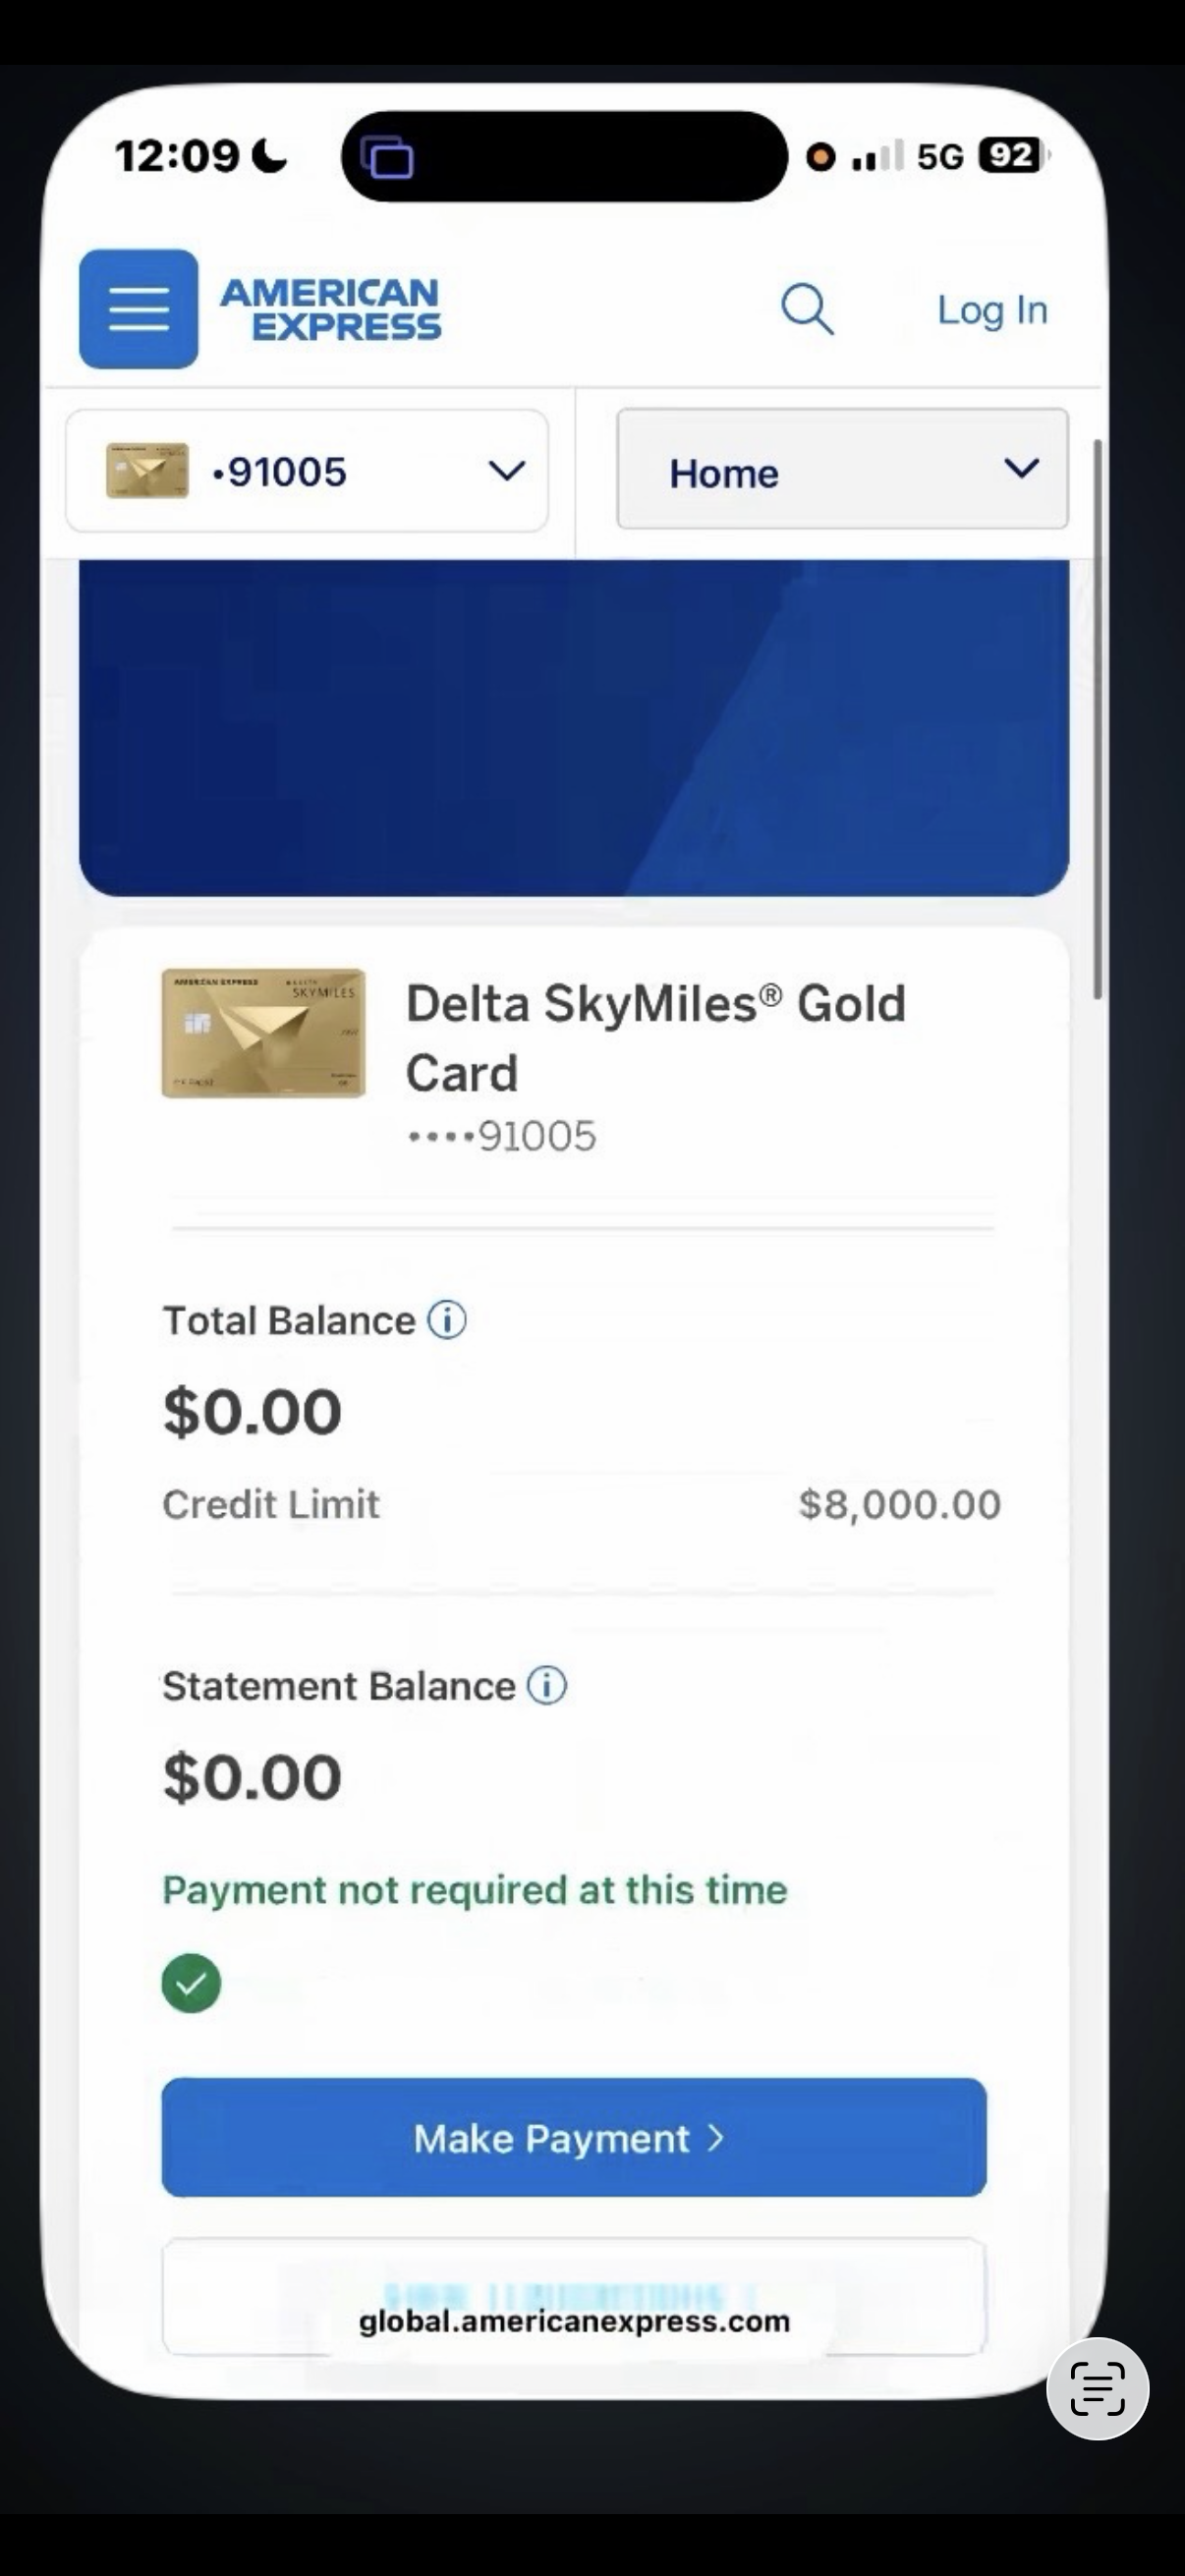
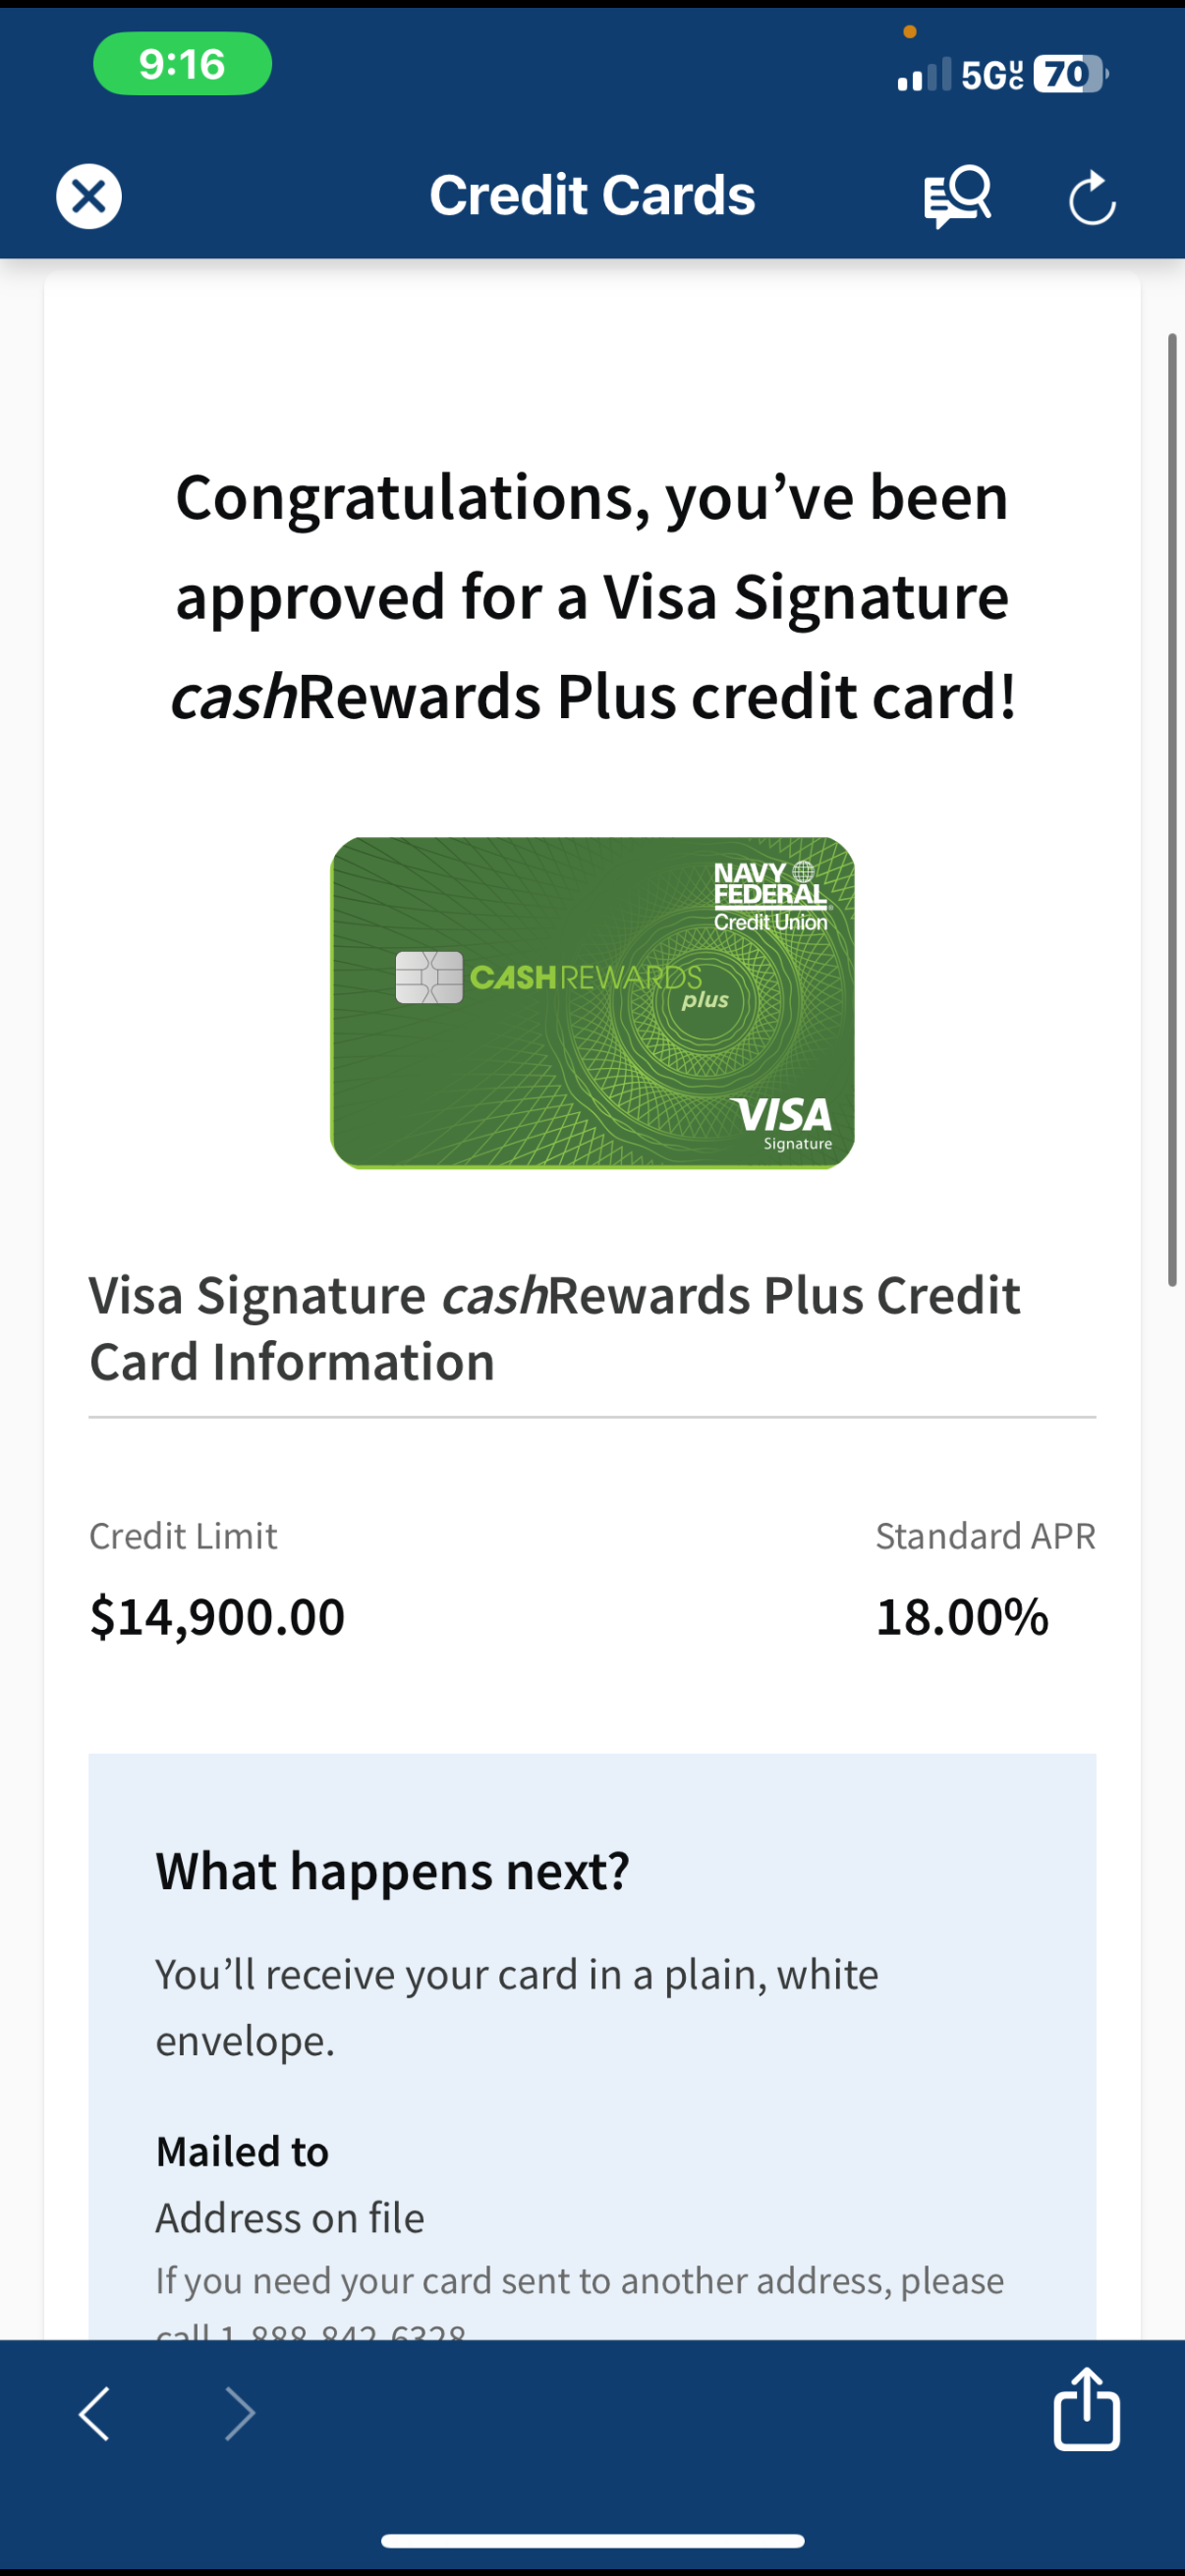
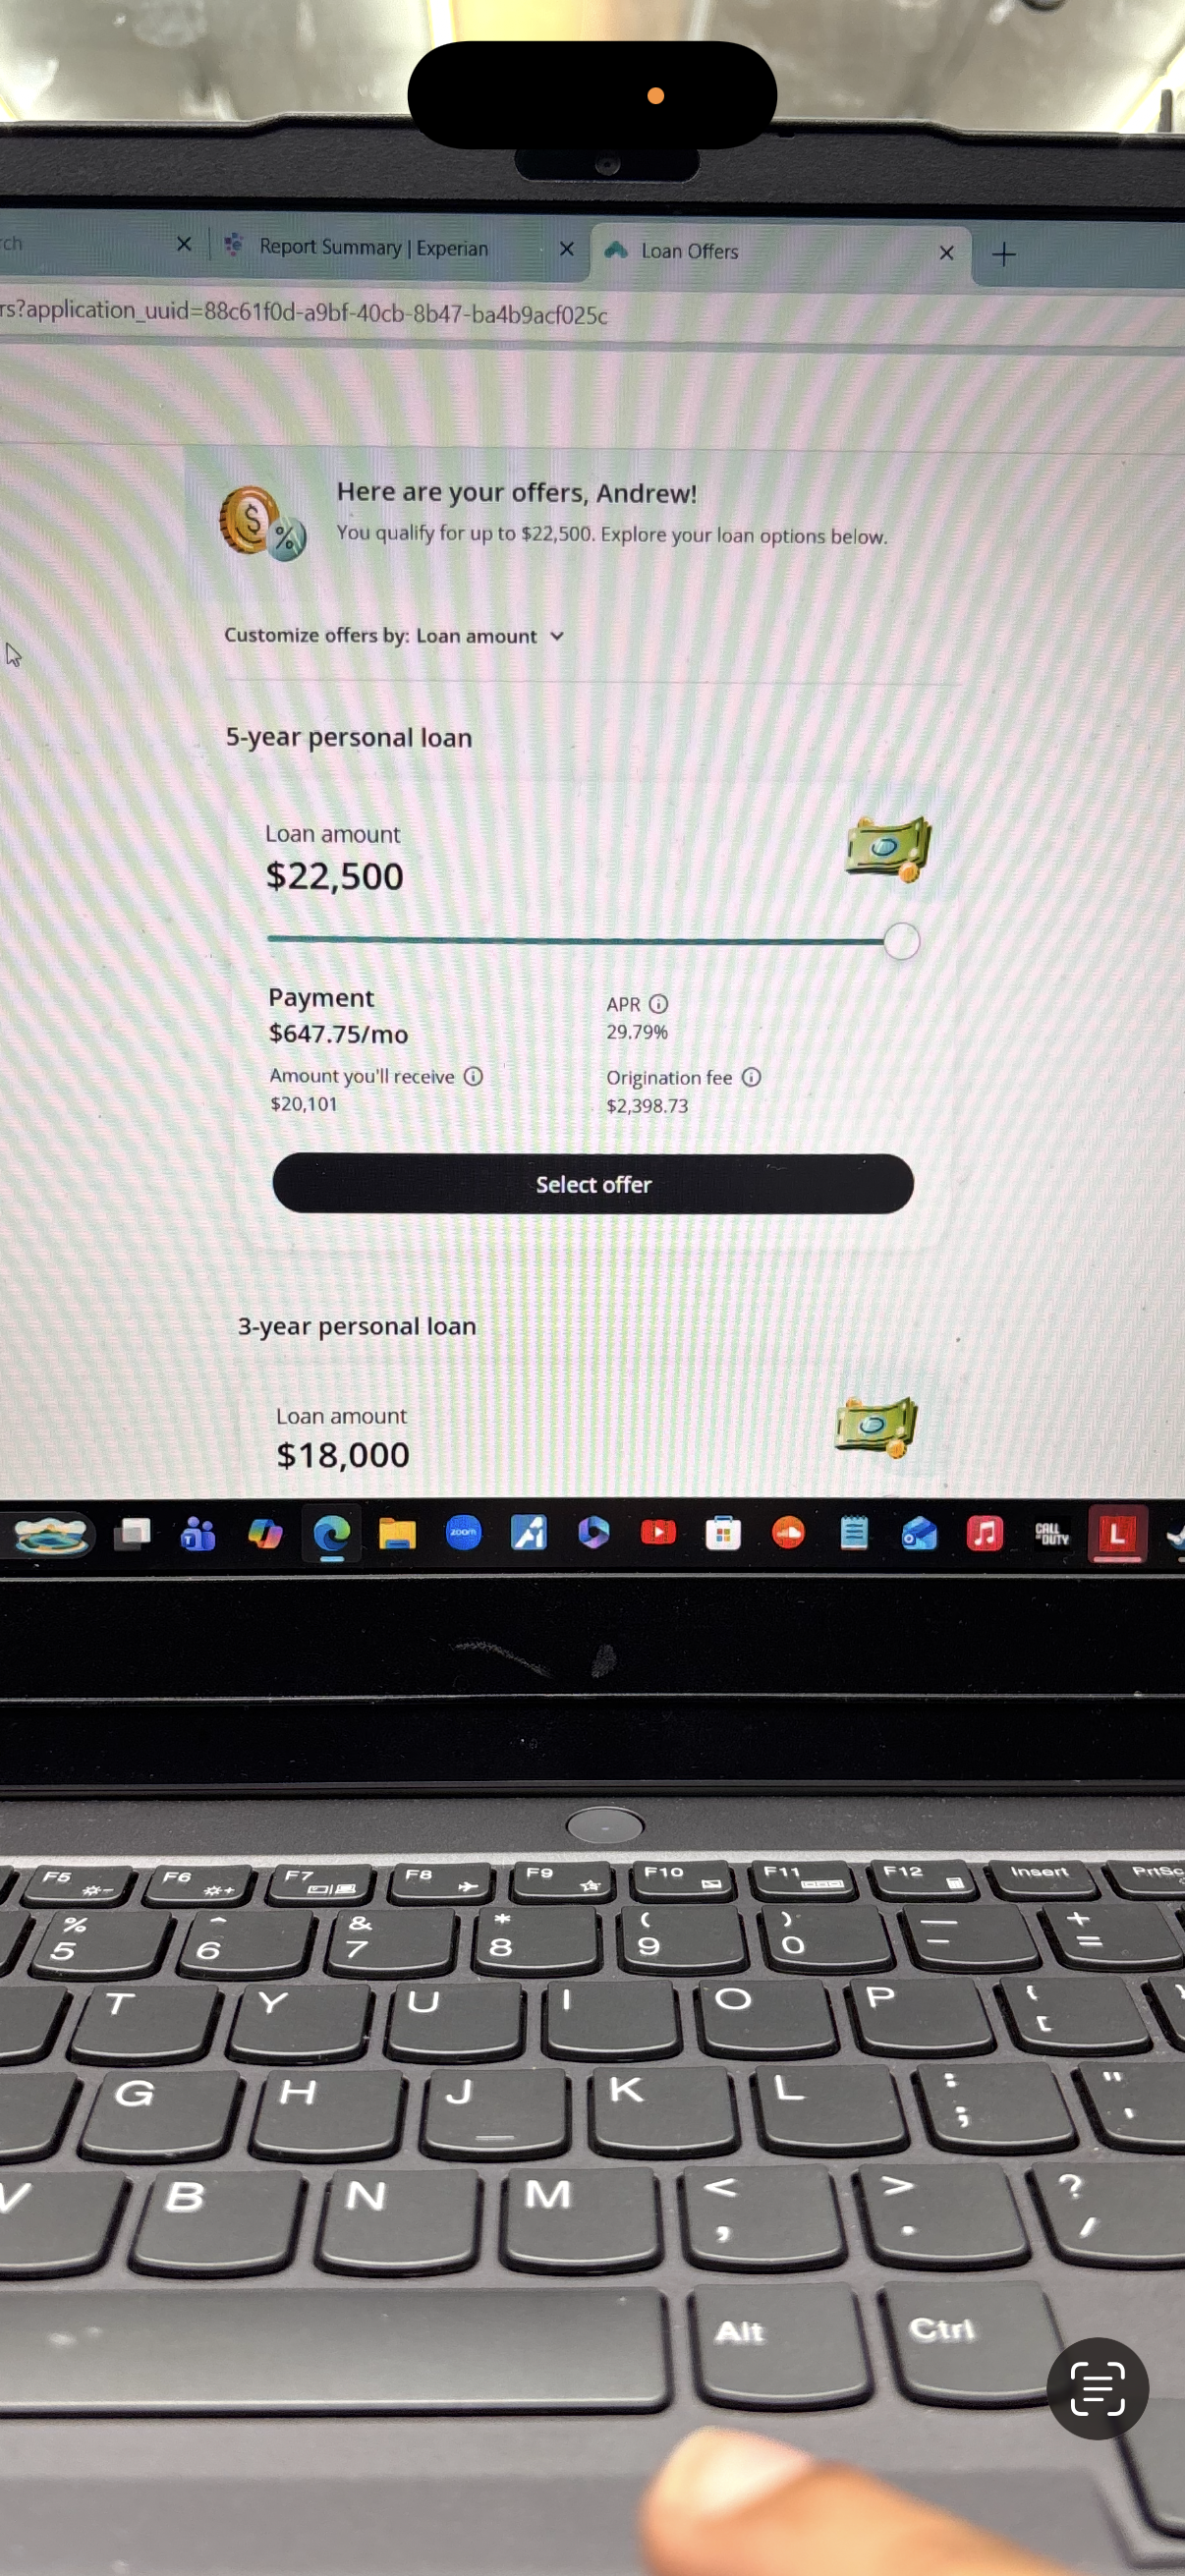
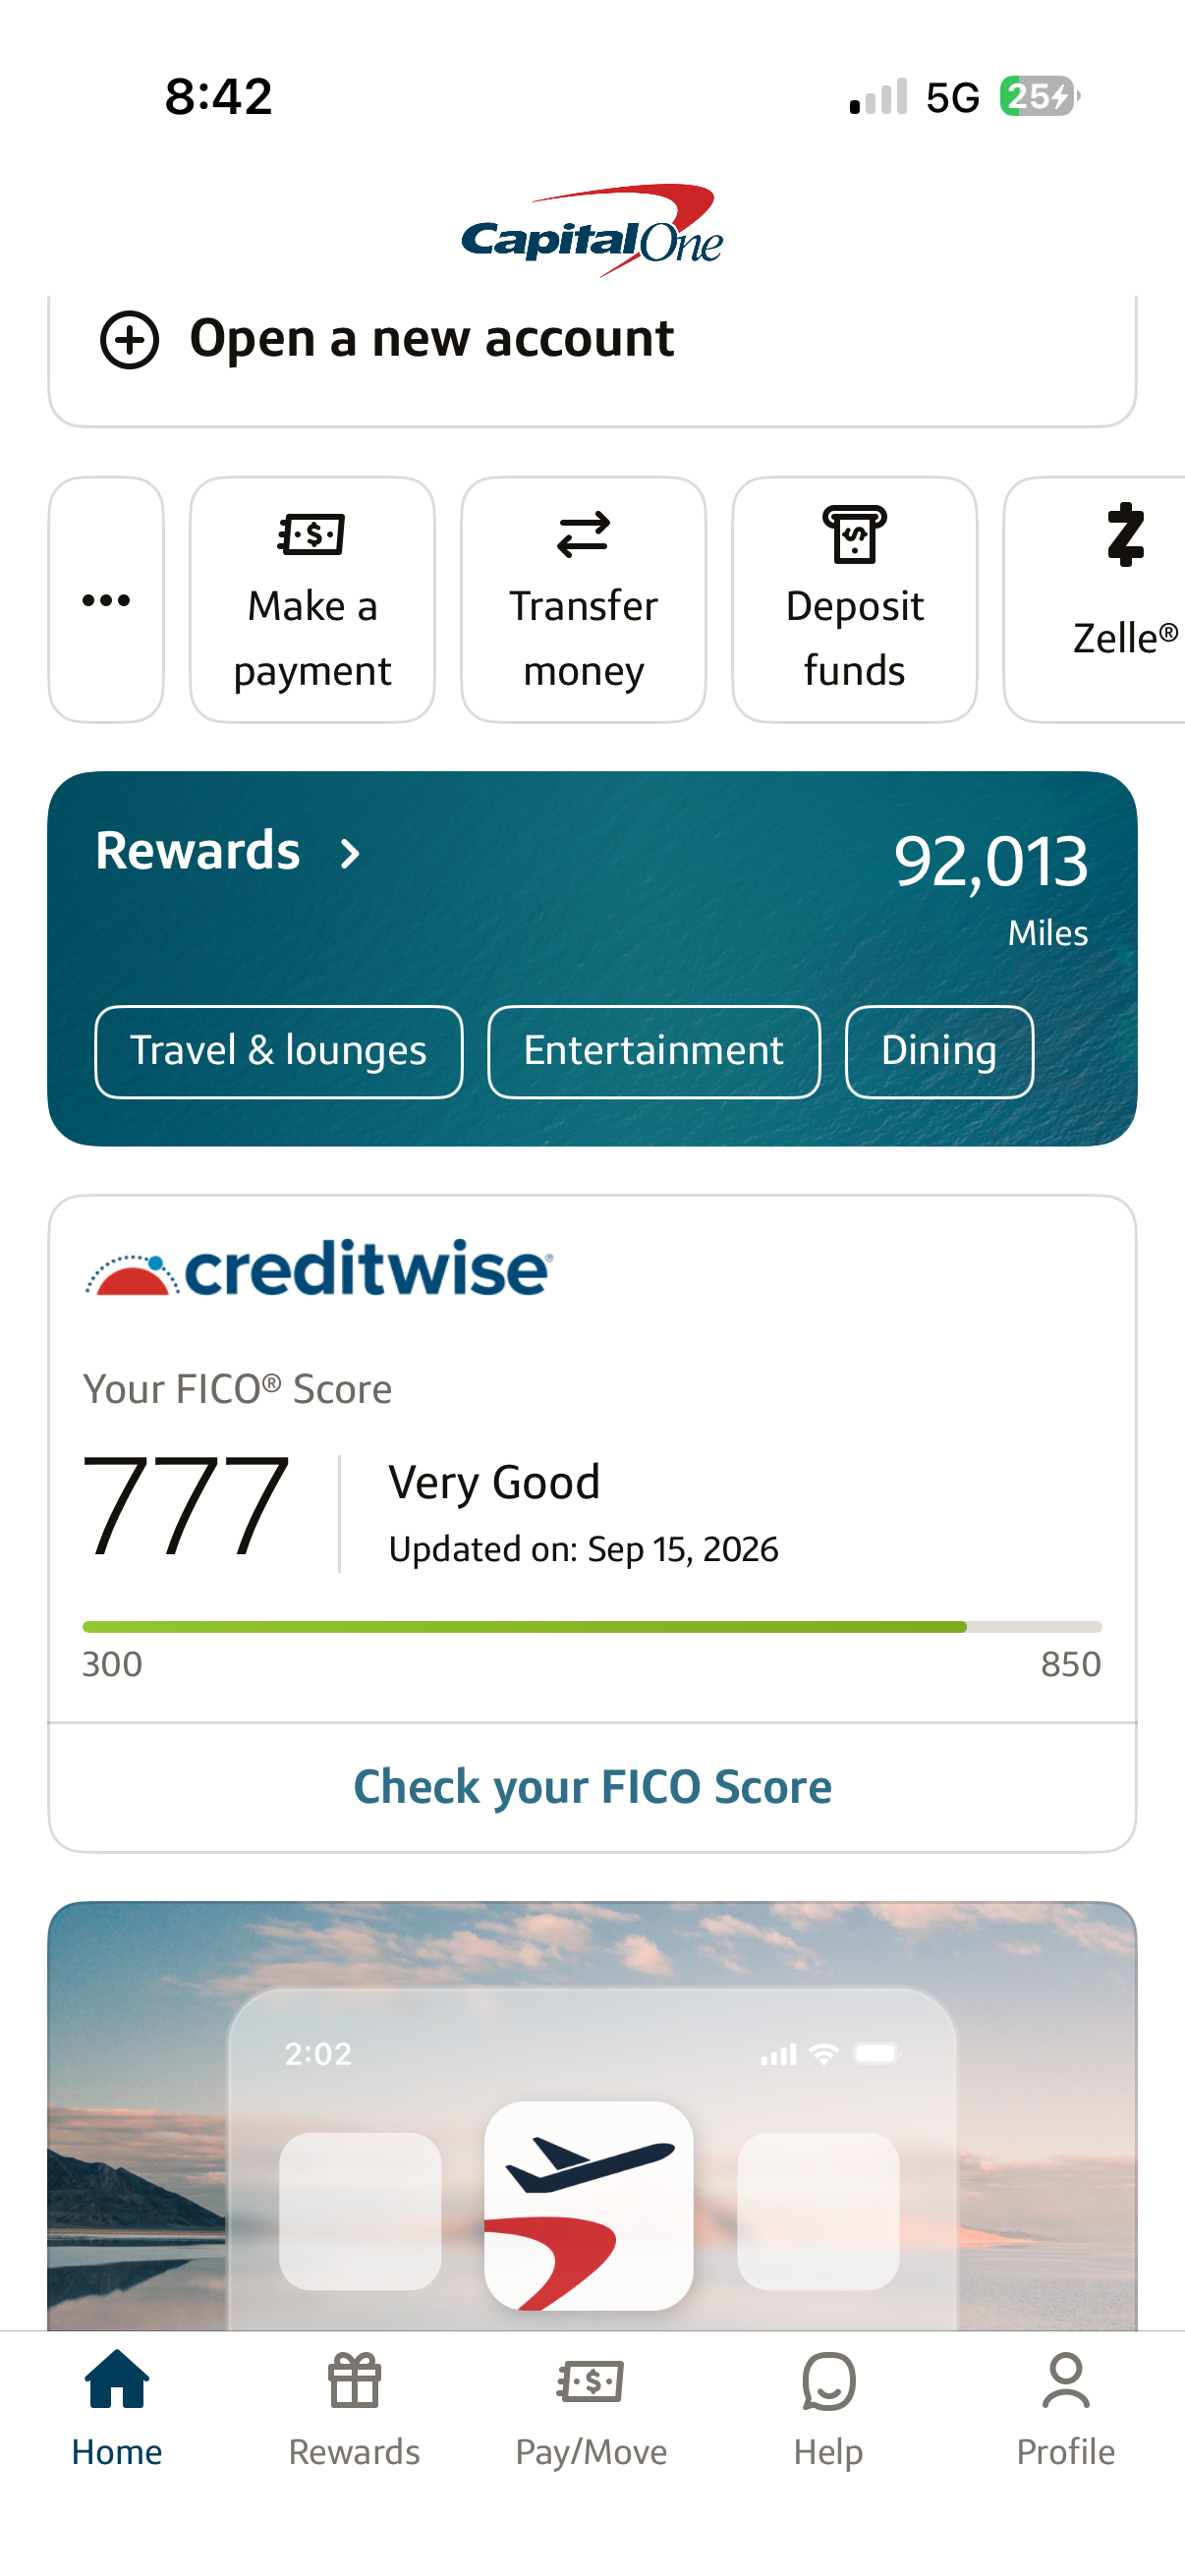
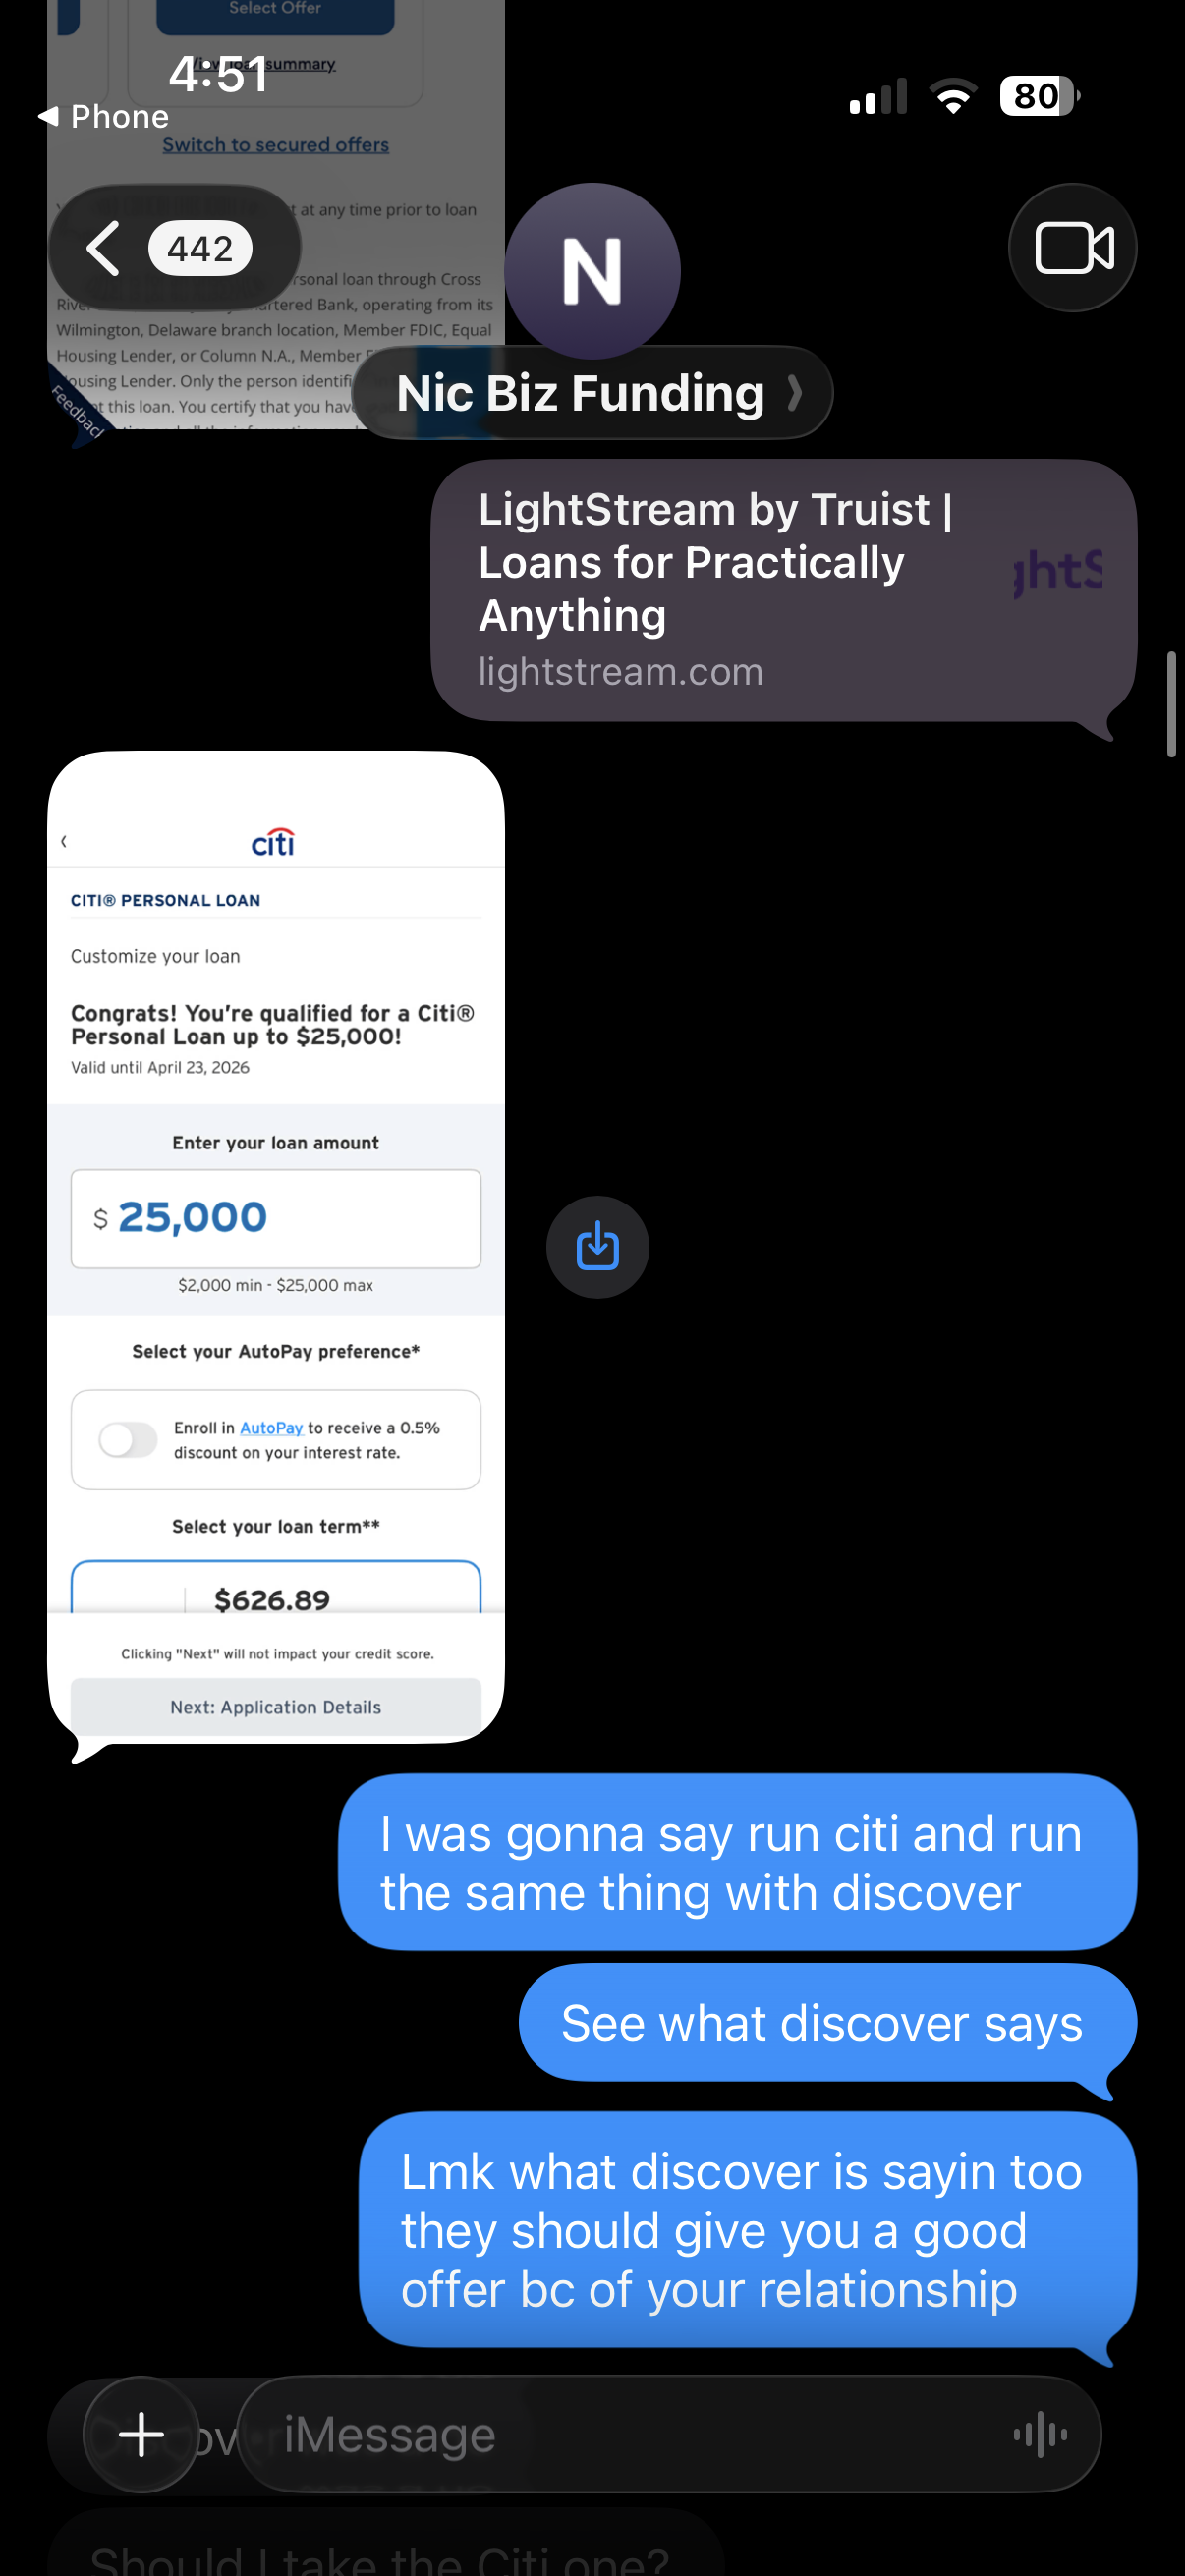
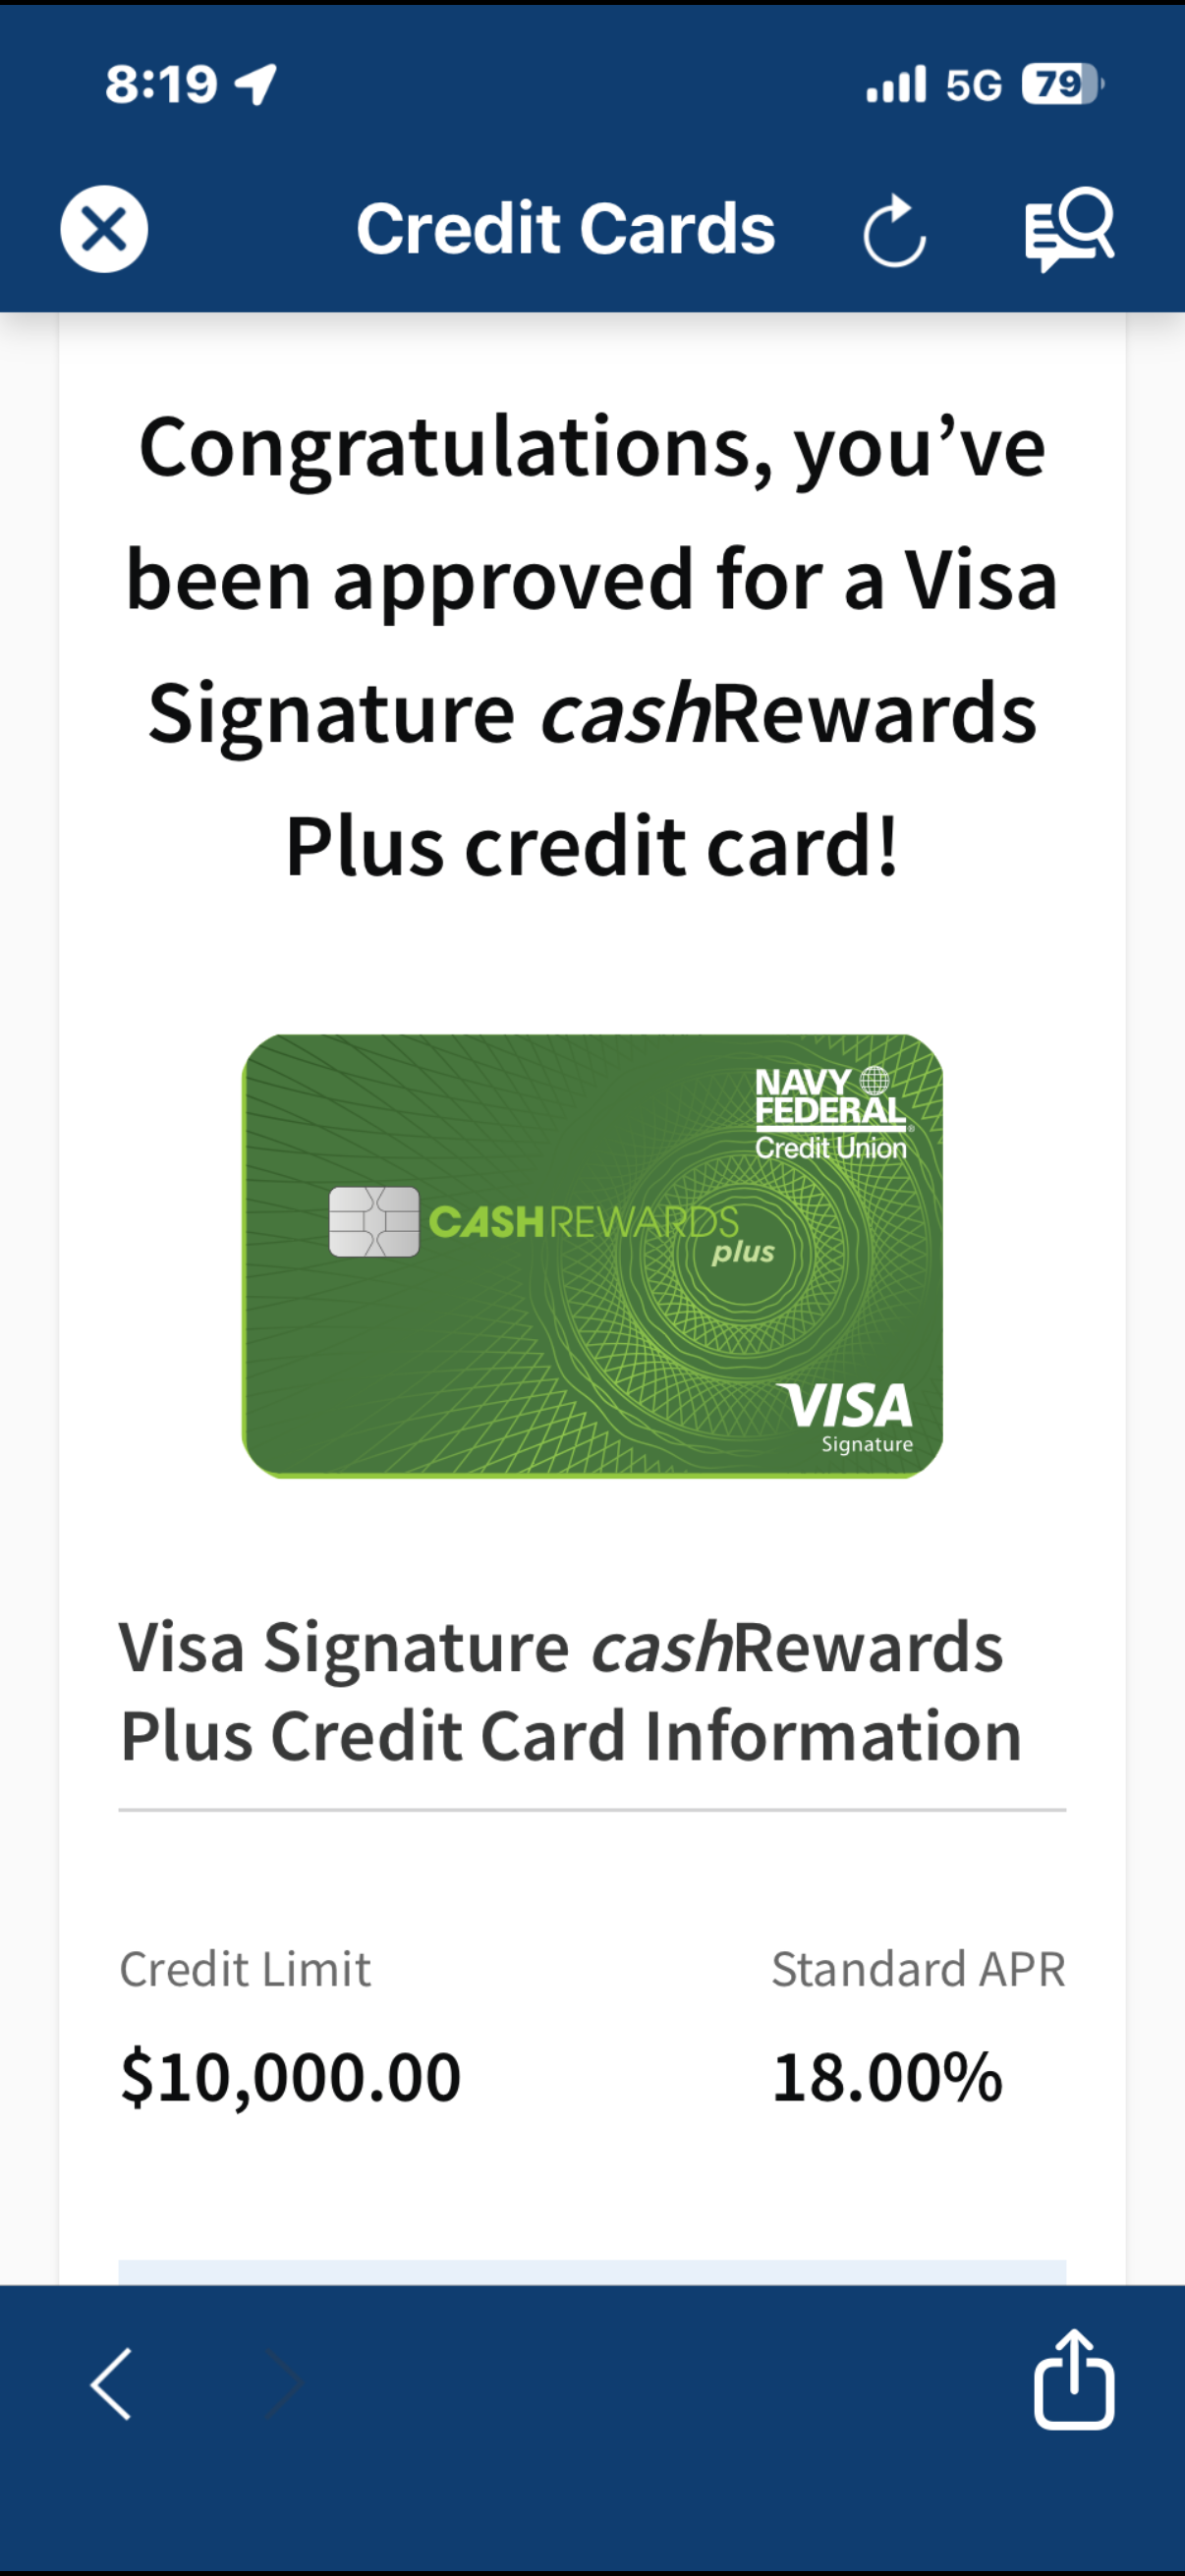
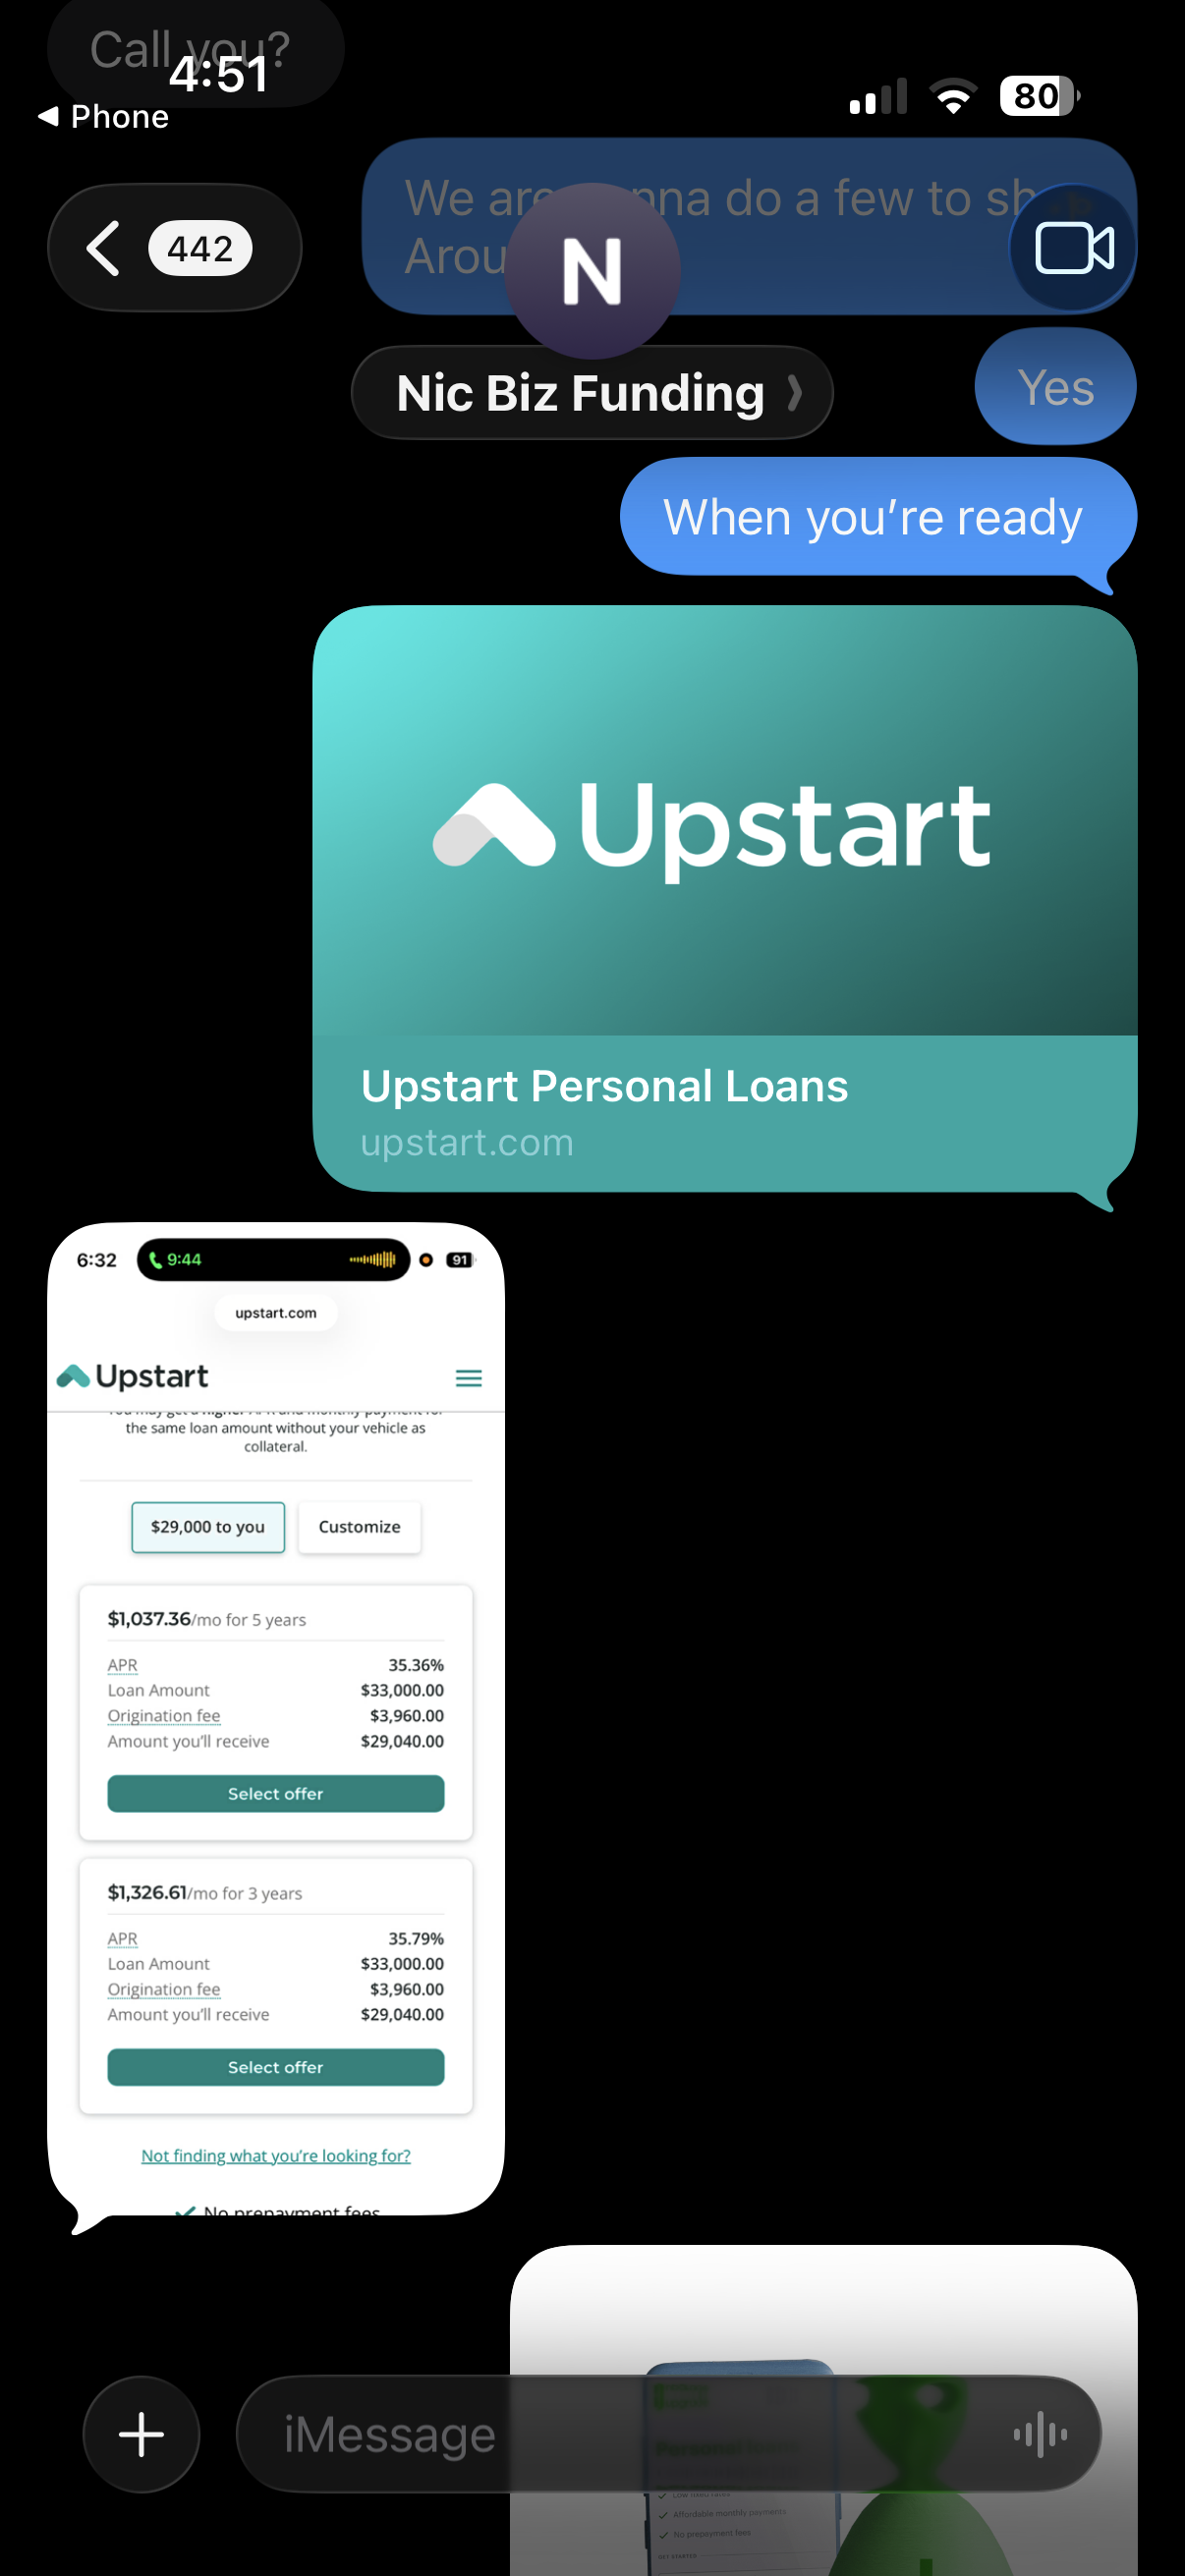
See exactly what is dragging your score down
Free ConsultationThe finance manager walks back out of the office... and this time he is smiling
No 40-minute wait while he "talks to the bank."
He slides the paper across the desk and the rate on it starts with a 5... not a 19.
The apartment application that used to ask for "an additional deposit" comes back approved before lunch.
That mortgage broker who told you to "come back in two years"? You are signing closing papers with him this spring.
And the credit card offers that land in your mailbox stop saying "rebuild" and "secured"... and start saying "pre-approved."
None of that requires a raise, a second job, or seven more years of waiting for old accounts to age off.
It requires a credit report that is actually accurate.
What staying right where you are is costing you
- A car payment $312 a month higher than your neighbor pays for the exact car sitting in their driveway
- Being told "we are going to need a co-signer"... at 38 years old
- Security deposits on your power, phone and internet... like you just moved out of your parents' house
- A mortgage rate gap that quietly drains $67,000+ out of your pocket over 30 years
- The "unfortunately, you do not qualify" email... that shows up after you already told your family about the house
- Paying a collection off in full, and watching your score not move a single point
- Opening your credit app every morning to find the number dropped again... for a reason nobody can explain to you
You did not create this system.
But right now... you are the one paying for it. Every single month.
See exactly what is dragging your score down
Free ConsultationThe three bureaus do not build your credit report... the companies feeding them do
Everyone tells you to fight Experian, Equifax and TransUnion.
So you send the letters. You wait 30 days. And you get back one word... "verified."
Here is what they leave out.
The bureaus do not create the information on your report. They collect it from creditors, collection agencies, and a network of data furnishers and specialty reporting companies most people have never heard of.
These companies buy, sell and trade your financial history every single day.
Debts get sold three and four times over. Dates get changed in the handoff. Balances get re-reported. A $214 medical bill turns into a "new" collection with a brand-new open date... and your score takes the hit all over again.
And the lenders on the other end of all this?
They are fine with it. A lower score is exactly how they justify charging YOU 24% when your neighbor pays 7%.
So the errors stay... because the errors are profitable.
That is why disputing with the bureaus alone goes nowhere. You are arguing with the middleman while the source keeps reporting.
See exactly what is dragging your score down
Free ConsultationYour credit report spreads like a rumor... so we find out who started it
You already know how a rumor works.
One person says something. The next person repeats it with a detail wrong. By the time it reaches you, half of it is made up... but everyone treats it like fact.
Your credit report travels the exact same way.
An account gets reported by a creditor... sold to a collector... picked up by a data furnisher... then passed to all three bureaus. Every handoff is a chance for a wrong date, a wrong balance, a duplicate account, or a debt that was never yours to begin with.
So the first thing we do is pull your full three-bureau report and trace every negative item back to where it came from.
Who originally reported it. Who owns it today. What they are claiming... and whether those details match across Experian, Equifax and TransUnion.
Most clients are shocked by what turns up in that audit.
And every mismatch we find becomes leverage.
See exactly what is dragging your score down
Free ConsultationFederal law says if they cannot prove it... it has to be corrected or deleted
This is the part the credit industry does not advertise.
Under the Fair Credit Reporting Act (FCRA), everything on your report has to be accurate, complete and verifiable. Under the Fair Debt Collection Practices Act (FDCPA), a collector has to be able to validate the debt it is chasing you for. And the Truth in Lending Act (TILA) set the rules for how your accounts had to be disclosed to you in the first place.
So we do not send a generic "this is not mine" letter.
We send formal demands directly to the furnishers and collectors reporting on you, requiring the documentation behind every item. The original signed agreement. The complete payment history. Proof that the balance, the dates and the status are correct.
They generally have 30 days to respond.
And what happens next surprises almost everyone...
A lot of them cannot produce it.
When a company cannot verify what it is reporting, the law requires that item to be corrected or deleted. And when a company willfully ignores the FCRA, the law allows statutory damages of $100 to $1,000 per violation... which is exactly why we document every single response.
Why the last credit repair company you tried did not work
- They mailed the same copy-and-paste dispute template to the bureaus that thousands of other clients got
- You were billed every month for a year, then shown a 14-point bump and told it was "progress"
- Nobody ever went after the companies actually reporting the data... they only argued with the bureaus
We do not stop at round one
Most companies send one dispute, get back "verified," and bill you again next month.
We keep going.
Round after round, furnisher by furnisher, until every inaccurate, incomplete or unverifiable item on your report has been challenged at the source.
That persistence is how Azzurri Credit clients average a 118-point increase.
And you do not lift a finger. We write every letter, track every legal deadline, and text you the moment something comes off.
We also put our money where our mouth is.
Results or money back.
We call it the Furnisher Verification Protocol.
And it is the reason the companies reporting on you are about to have a very busy month.
See exactly what is dragging your score down
Free ConsultationGet your free Azzurri credit audit. It takes 60 seconds to request.
- A full three-bureau audit of every negative item on your report
- A specialist shows you exactly which items can be challenged, and why
- No obligation, and you are never charged for work that has not been done
- Results or money back
From audit to deletions in four steps
Free Credit Audit
We pull your three-bureau report and flag every collection, charge-off, late payment and inquiry dragging your score down.
Source Trace
Every negative item gets traced back to the furnisher, collector or data company actually reporting it, not just the bureaus.
Verification Demands
We send formal FCRA and FDCPA demands requiring documented proof behind every item, and track every legal deadline.
Deletions & Updates
Items that cannot be verified get corrected or deleted. You get a text every time one comes off, round after round.
See exactly what is dragging your score down
Free ConsultationReal reports. Real deletions. Sent in by Azzurri clients.
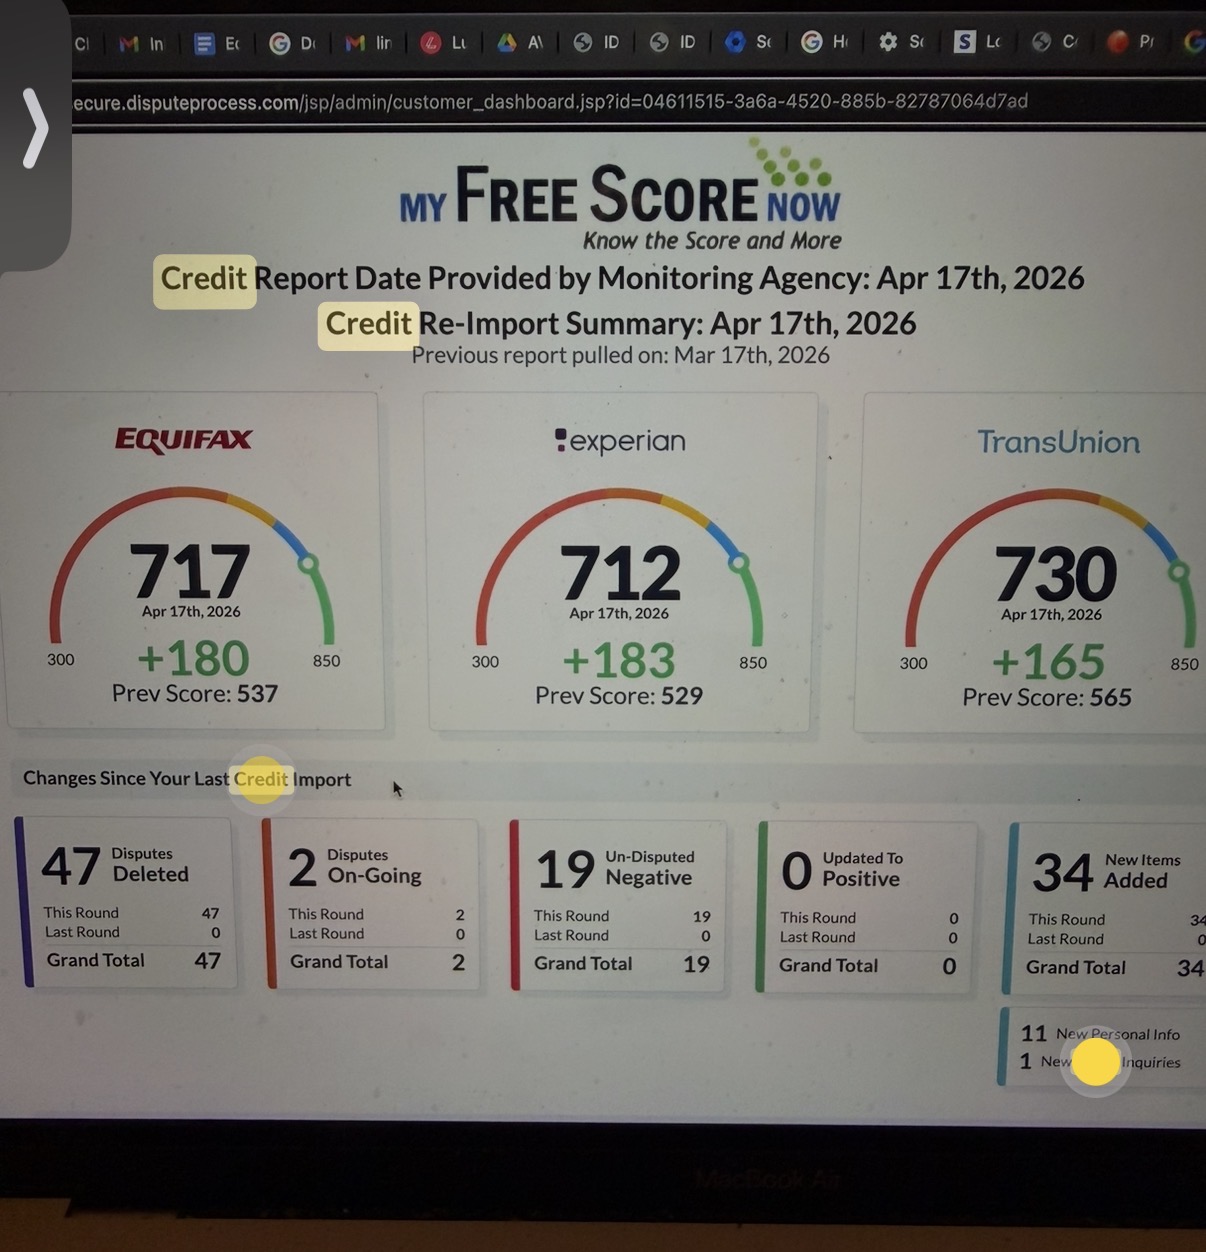
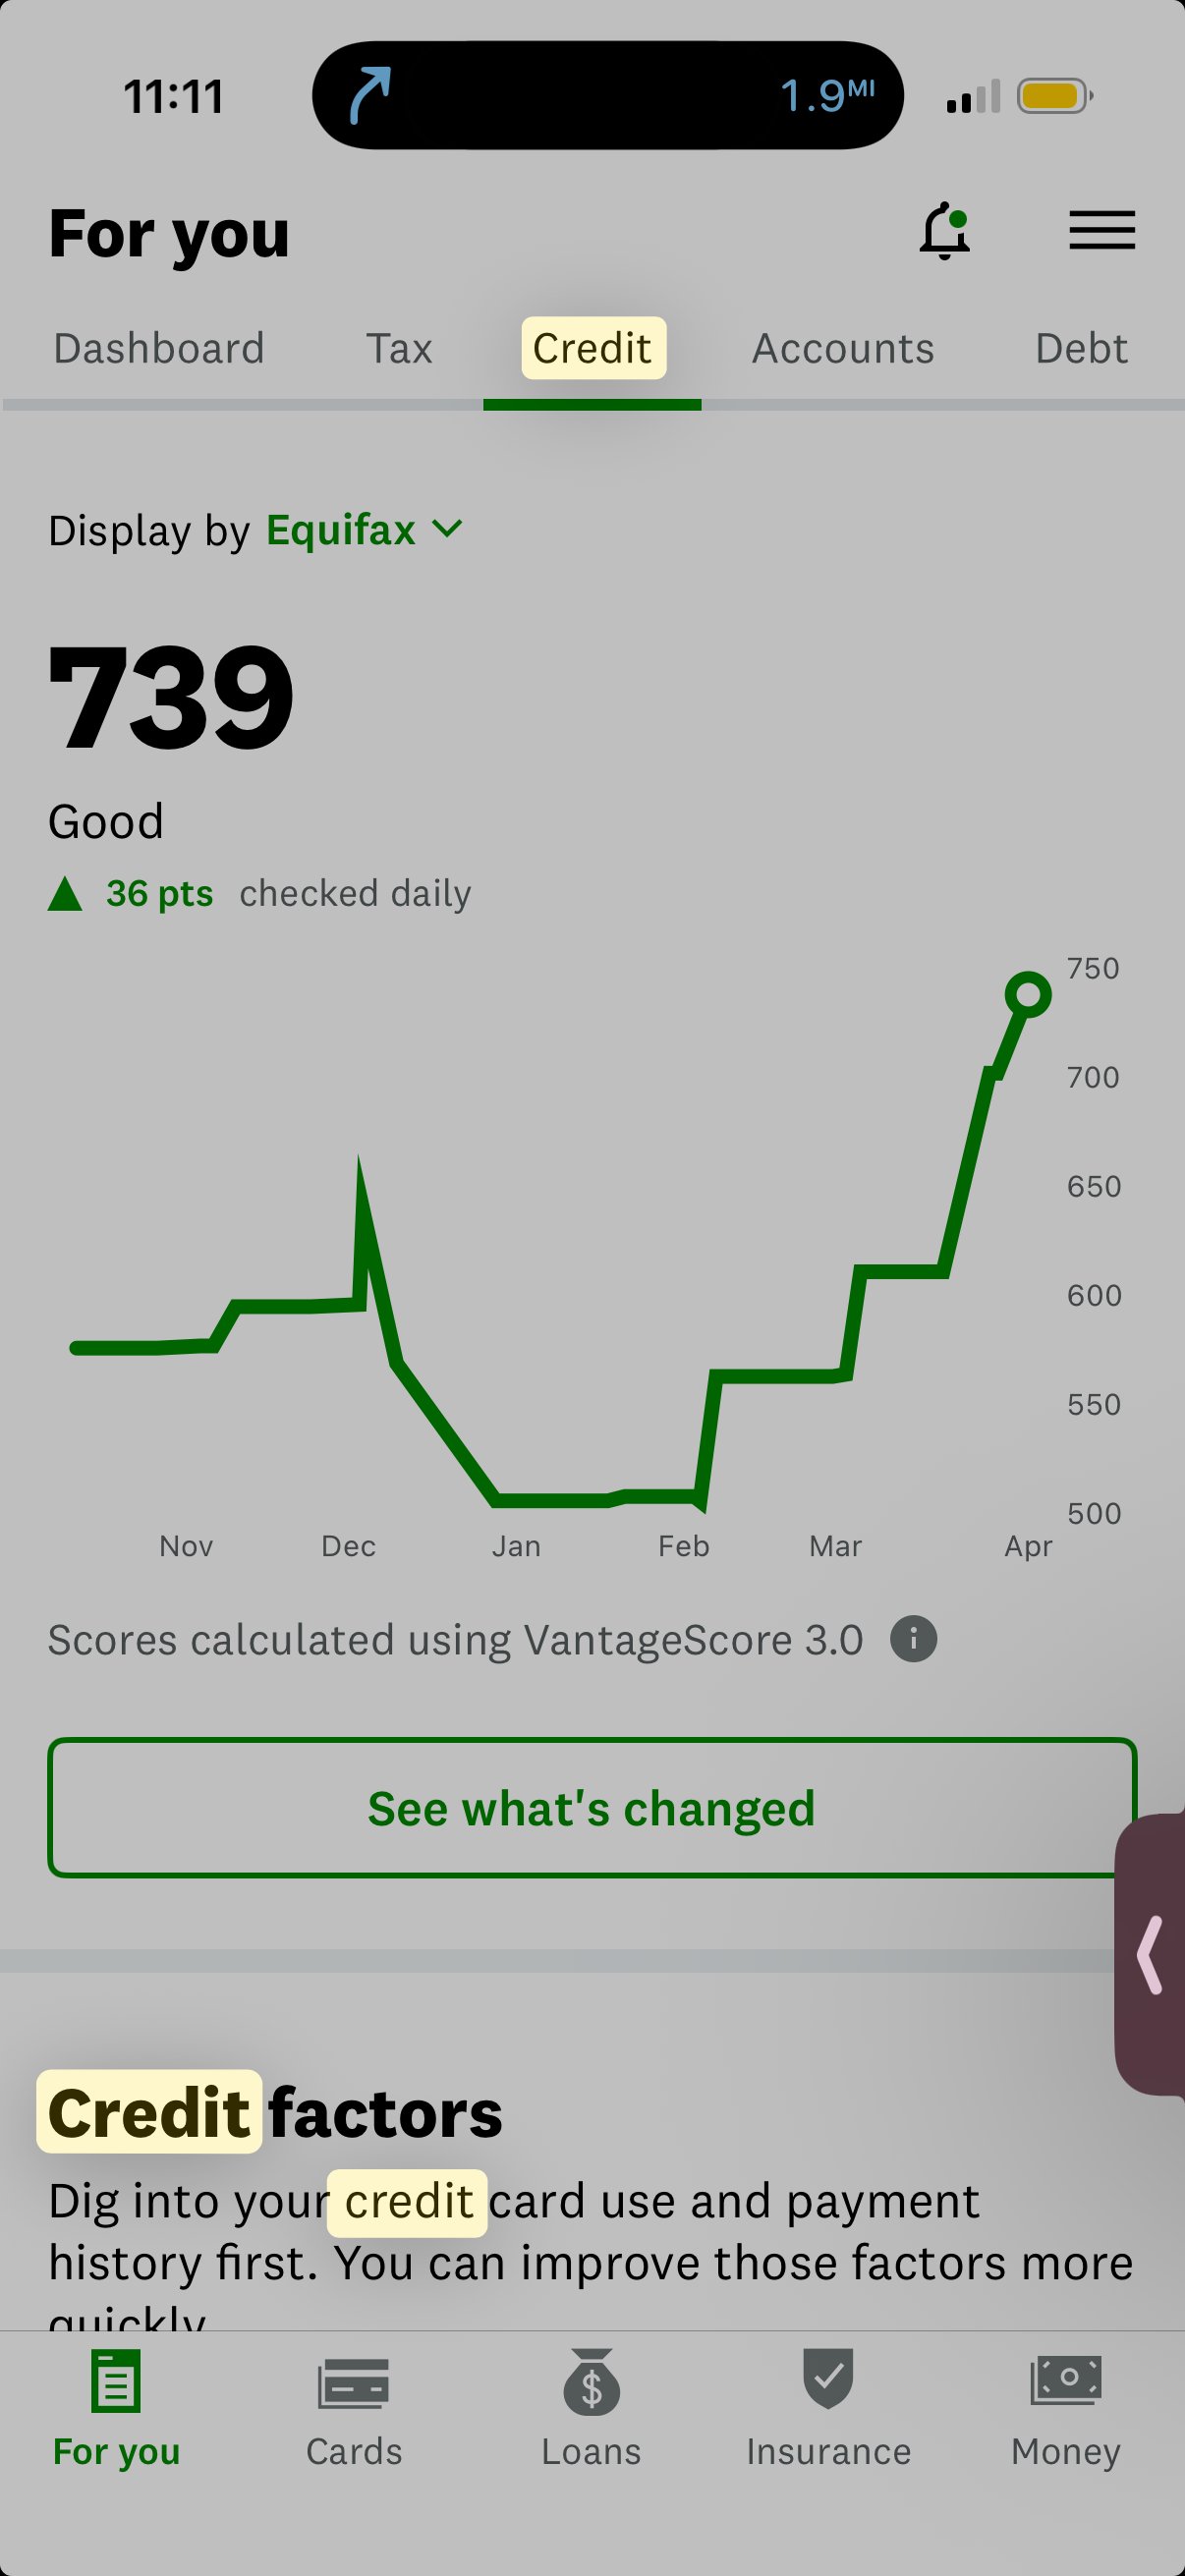
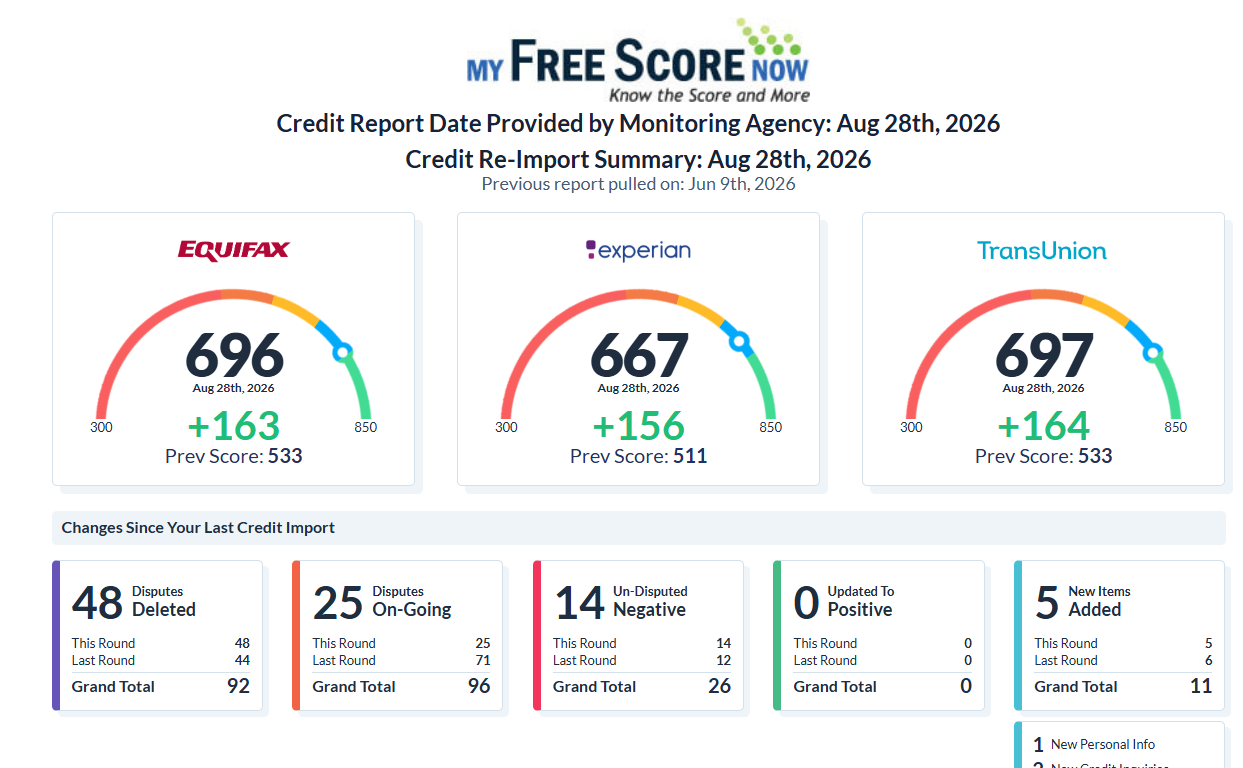
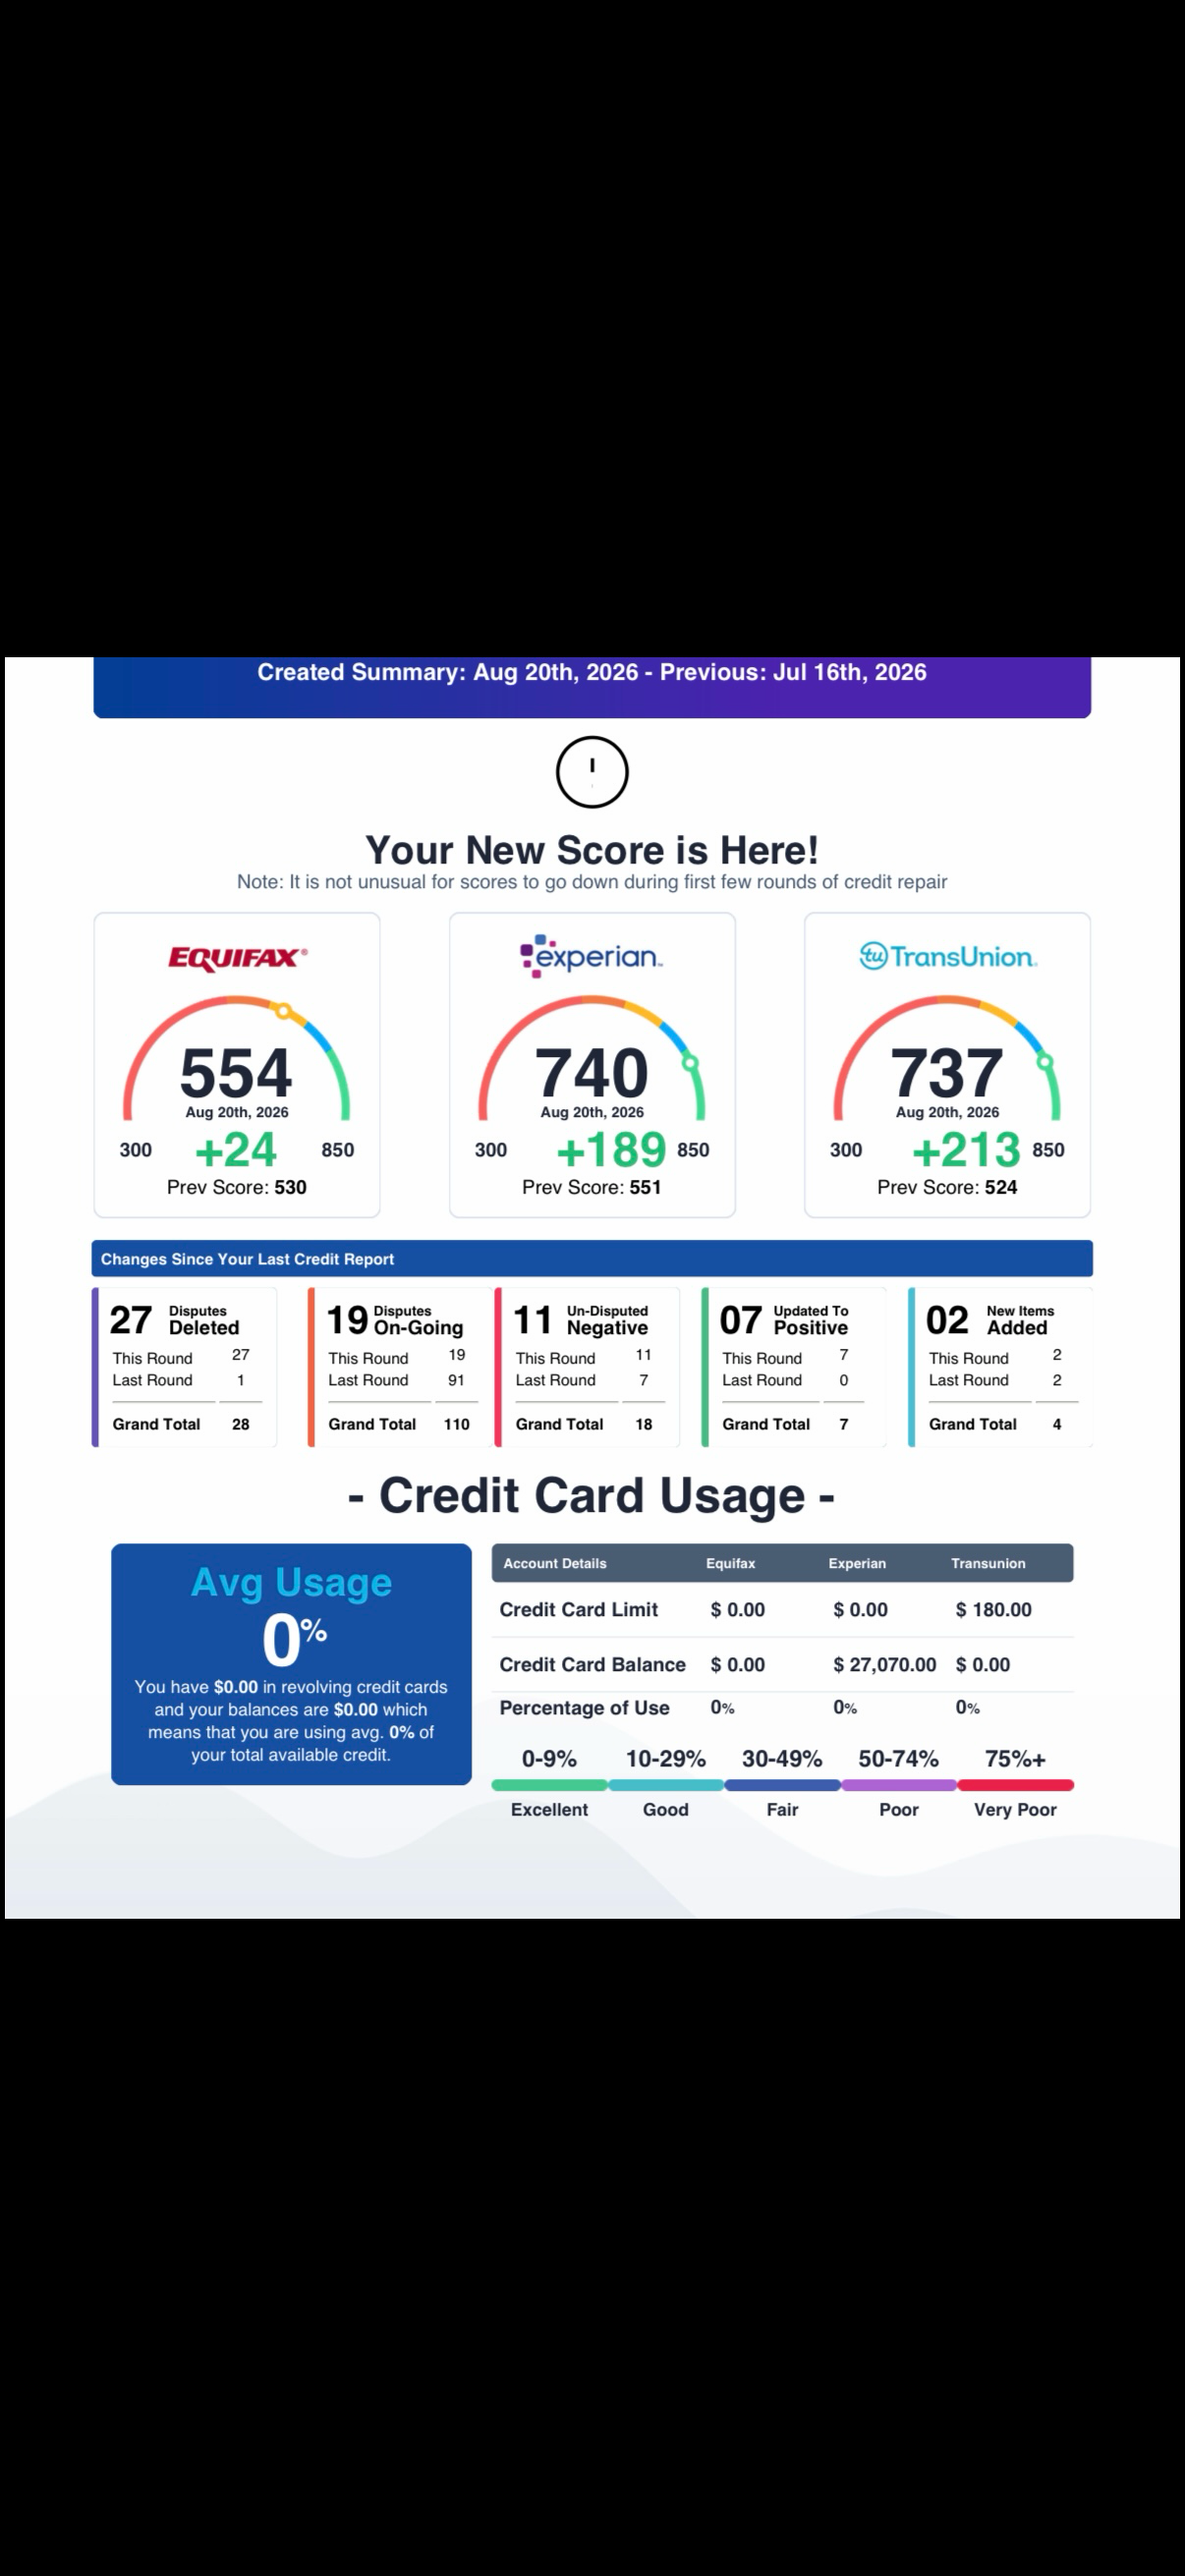
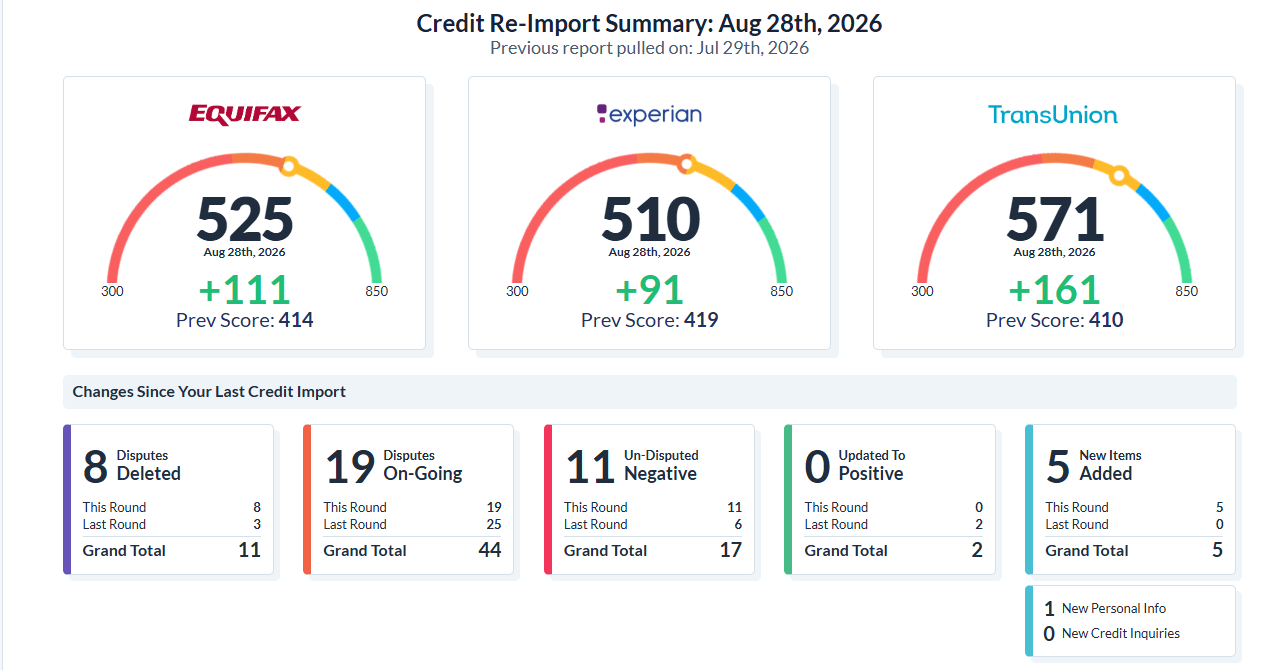
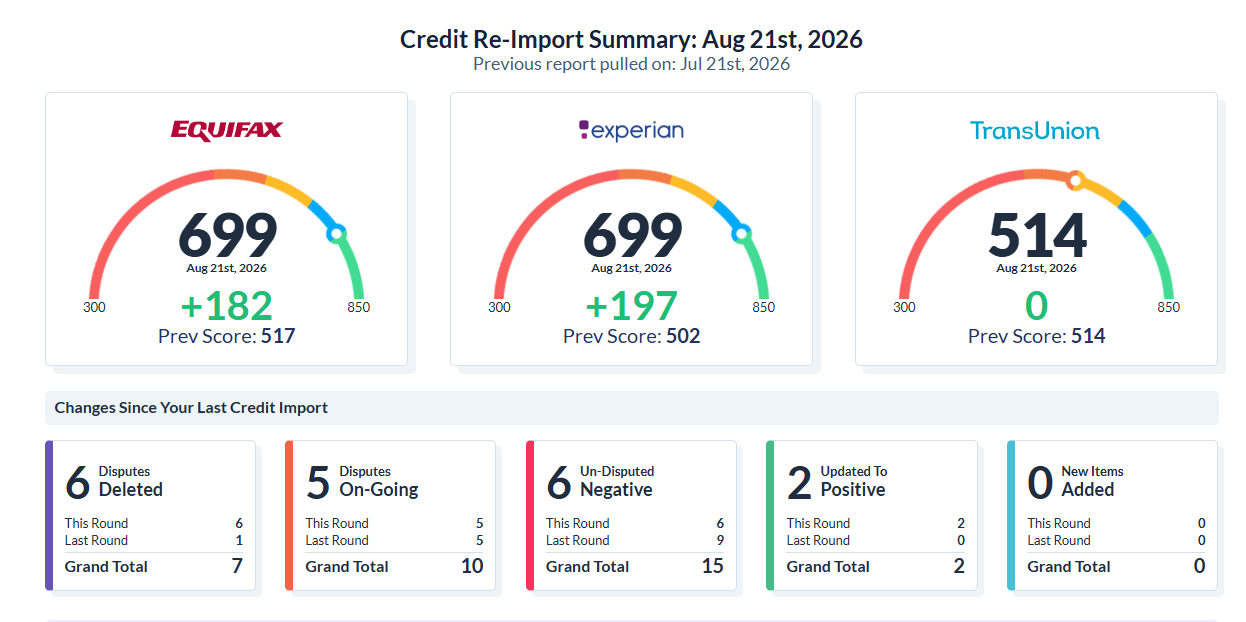
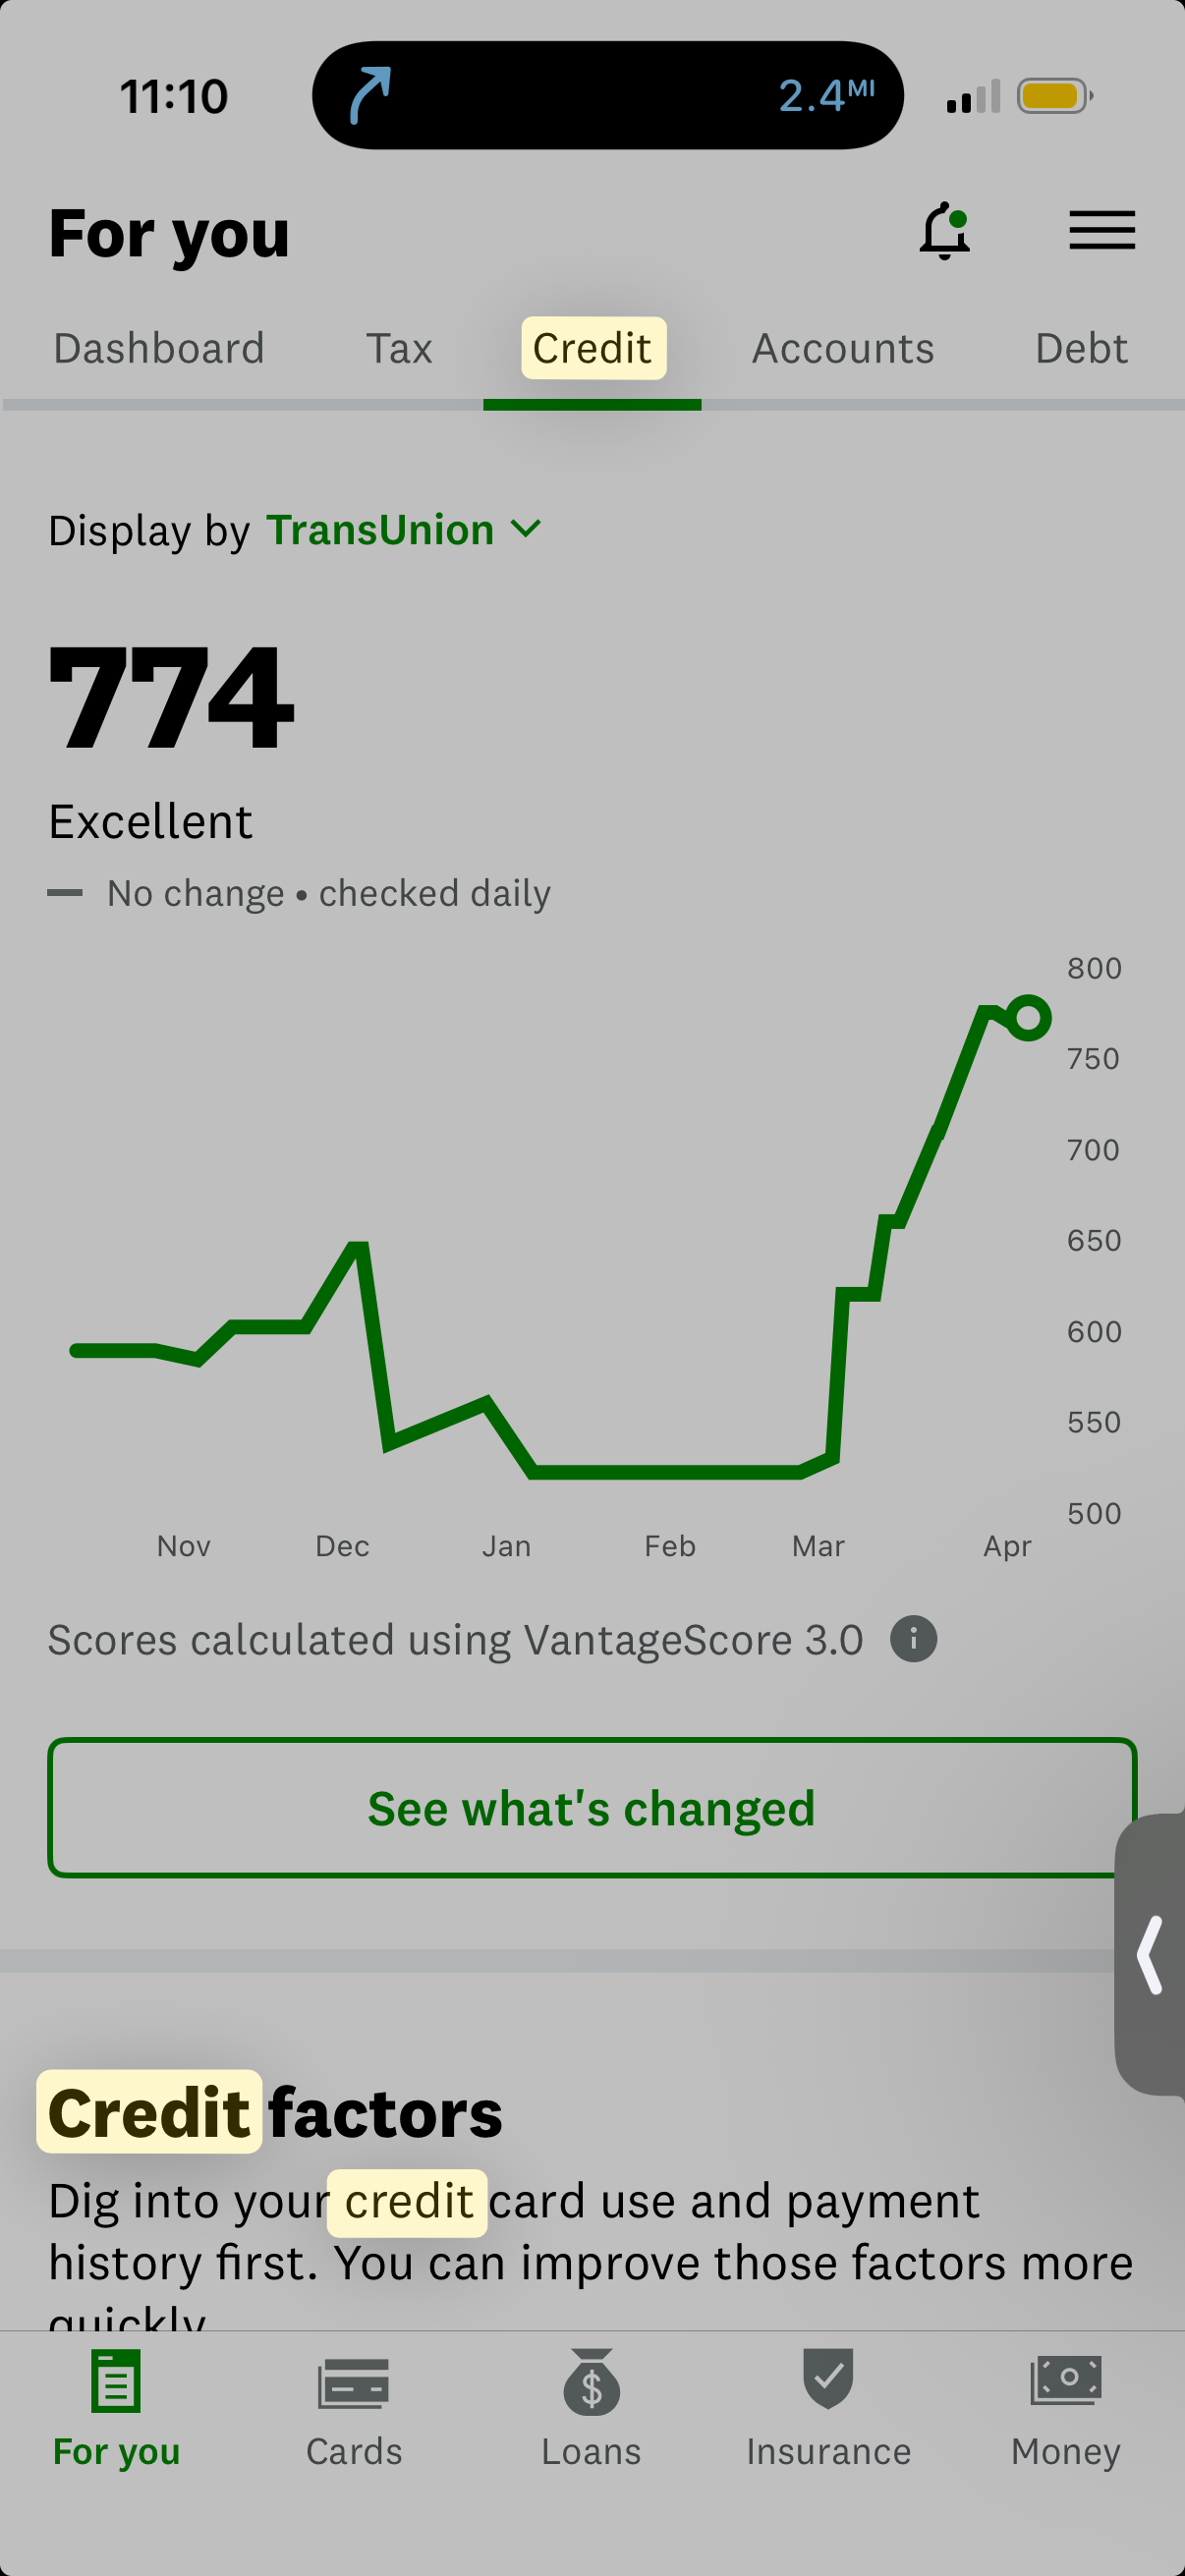
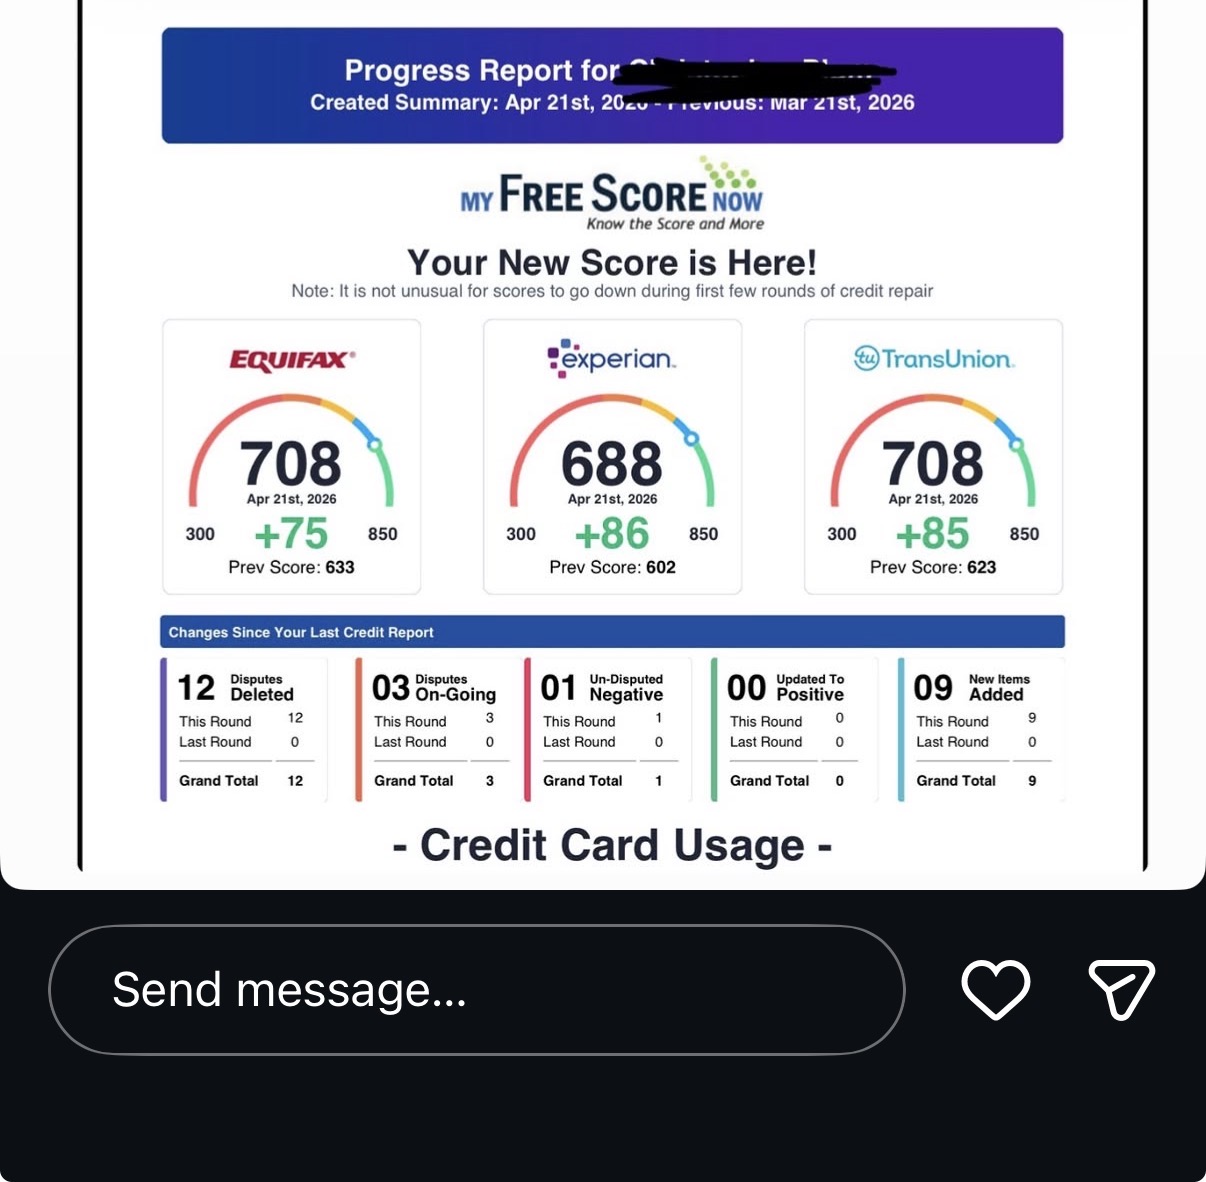
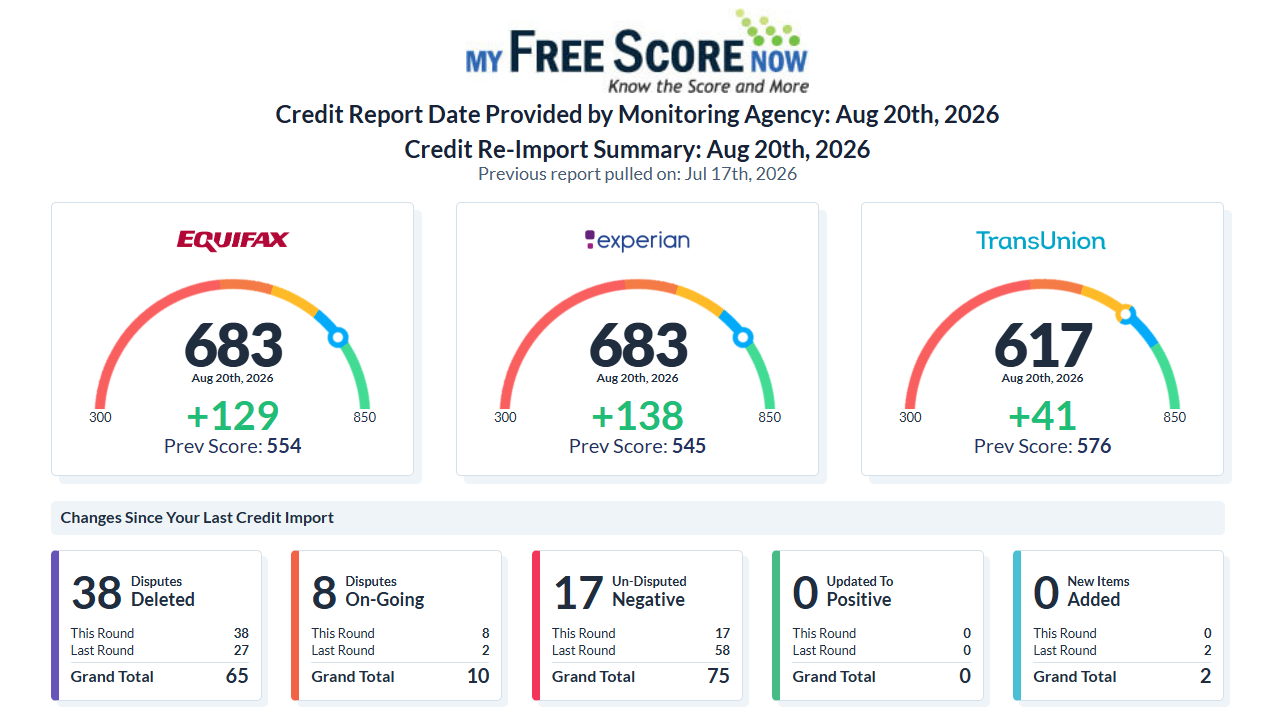
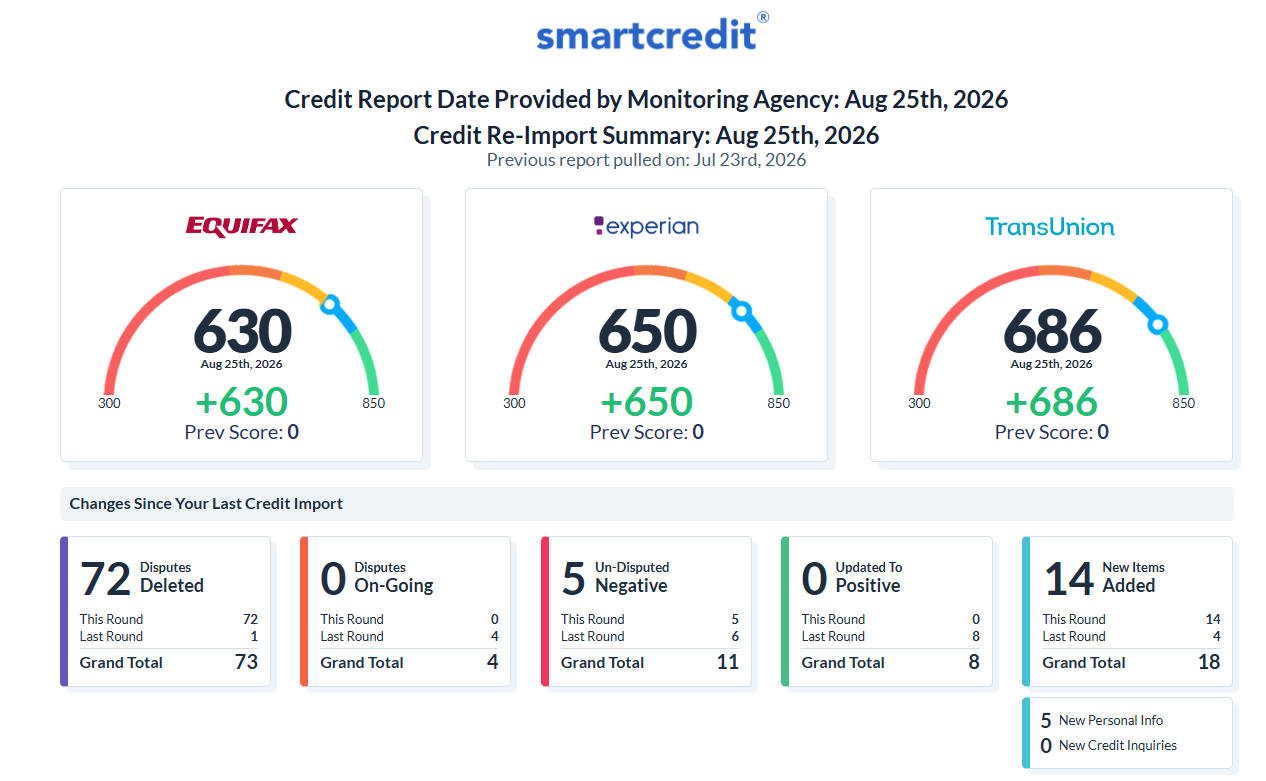
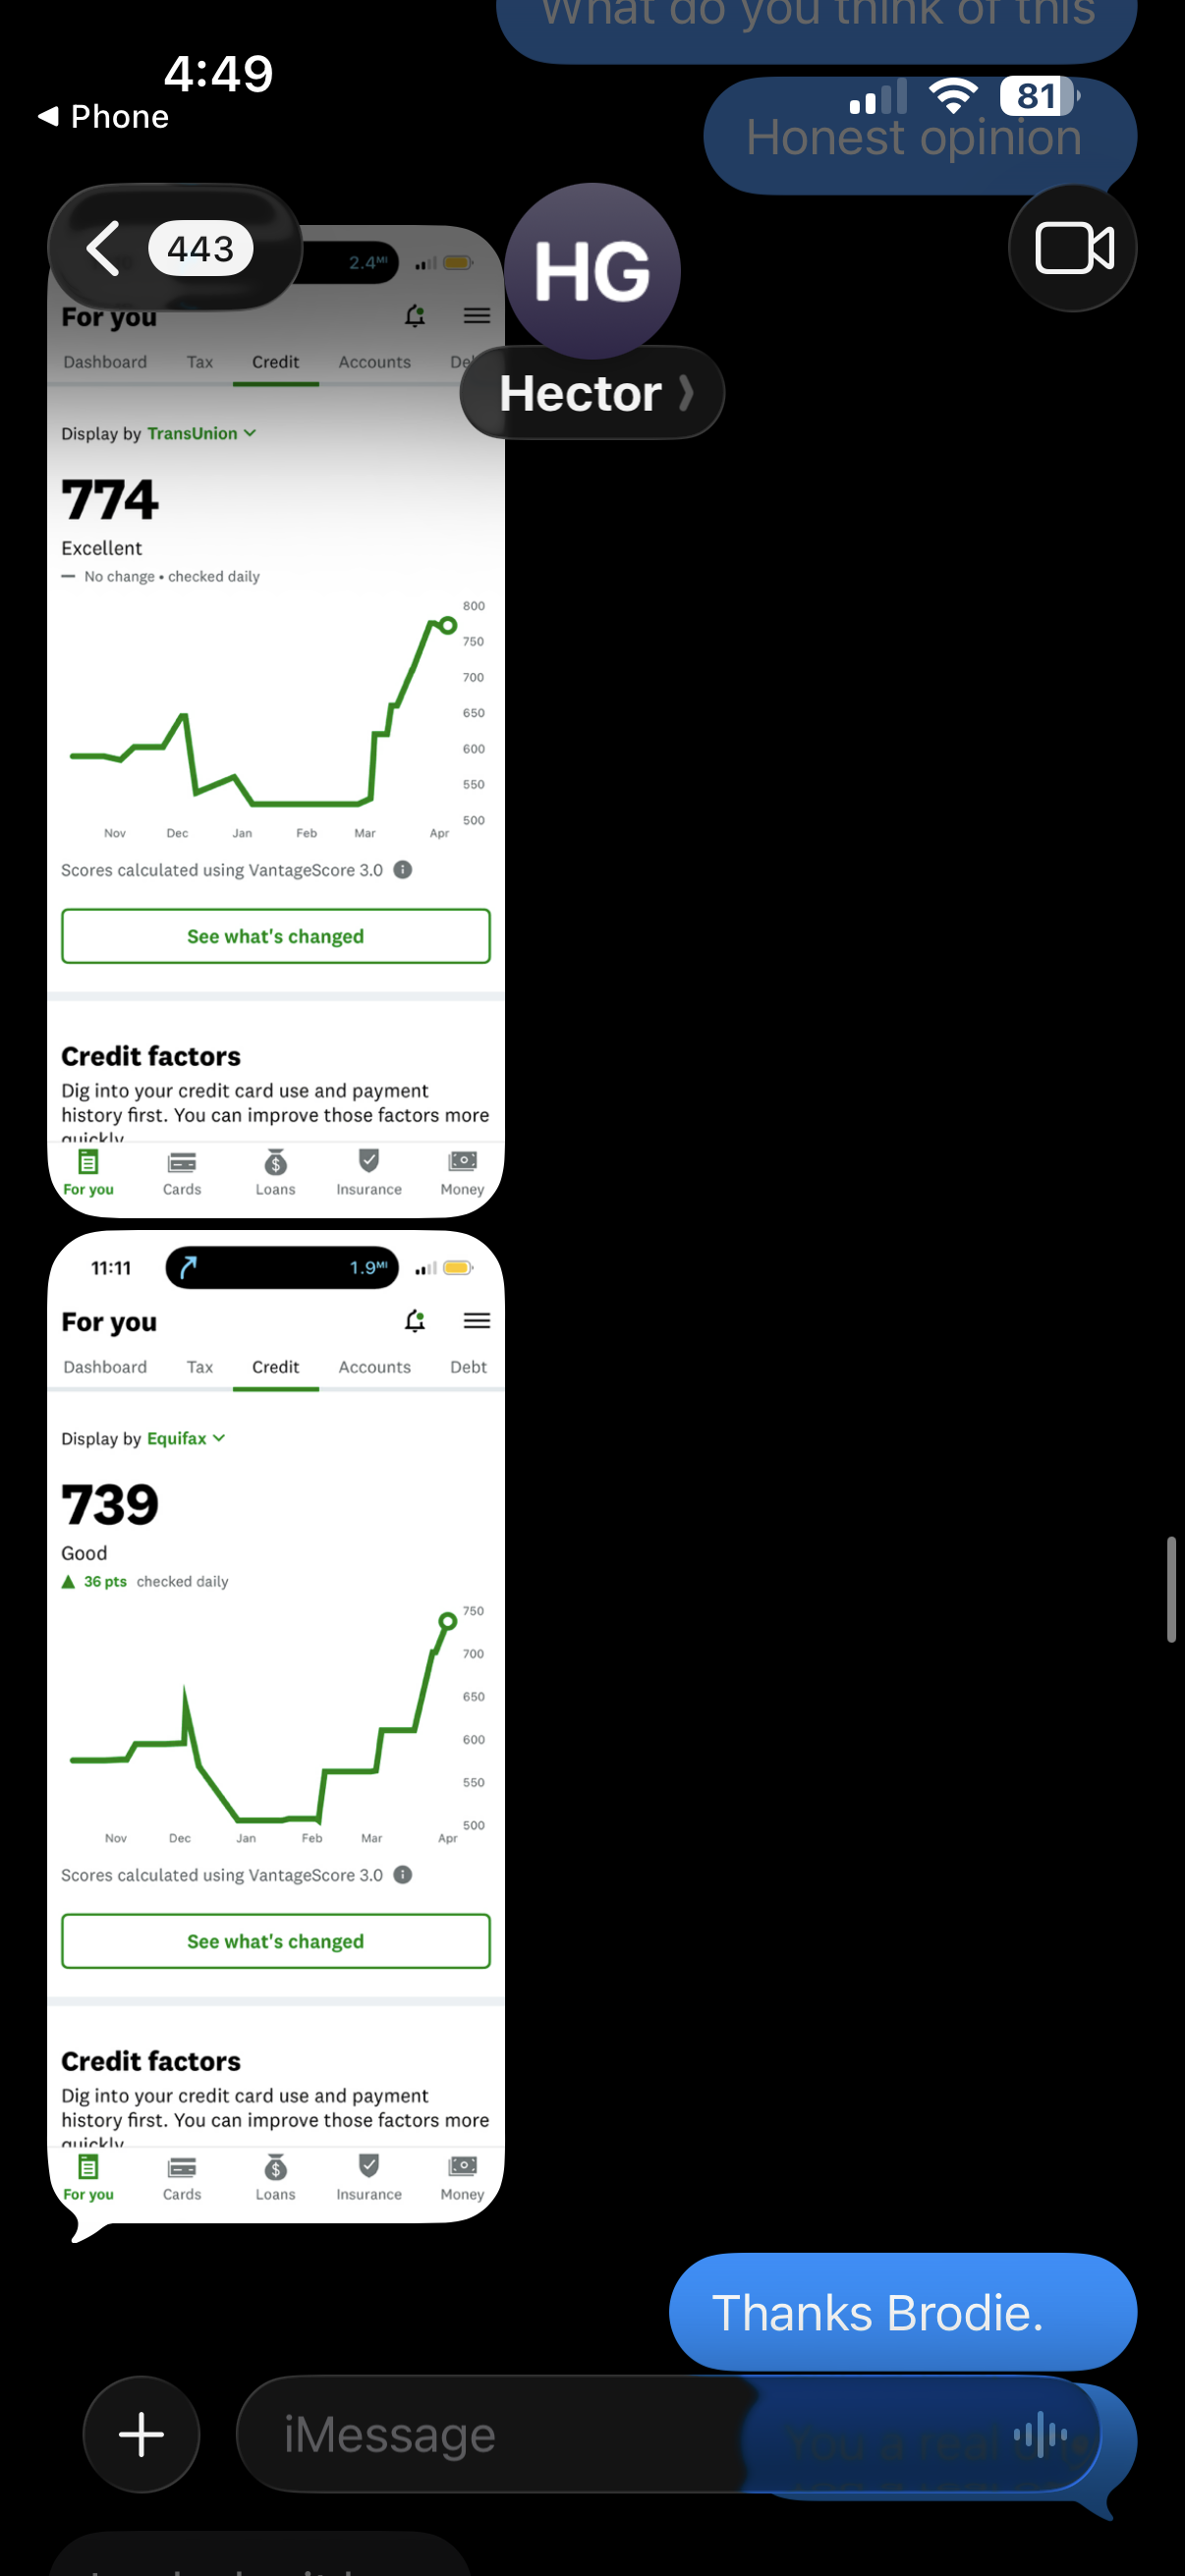
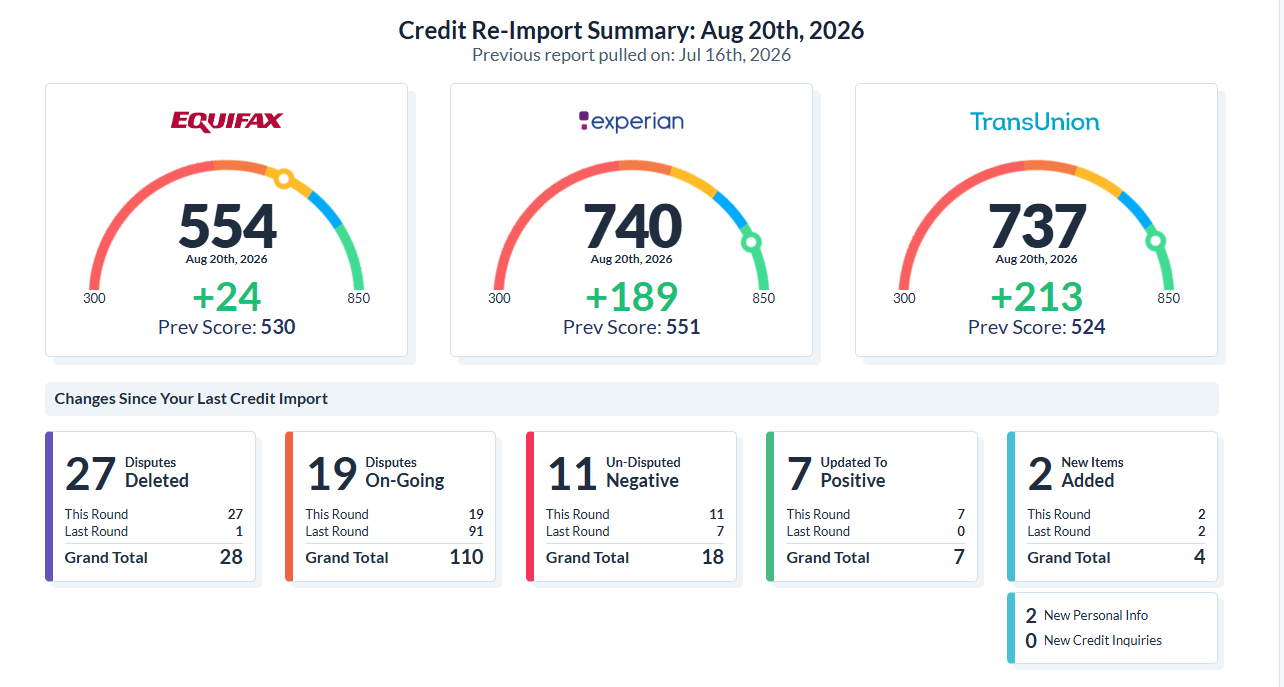
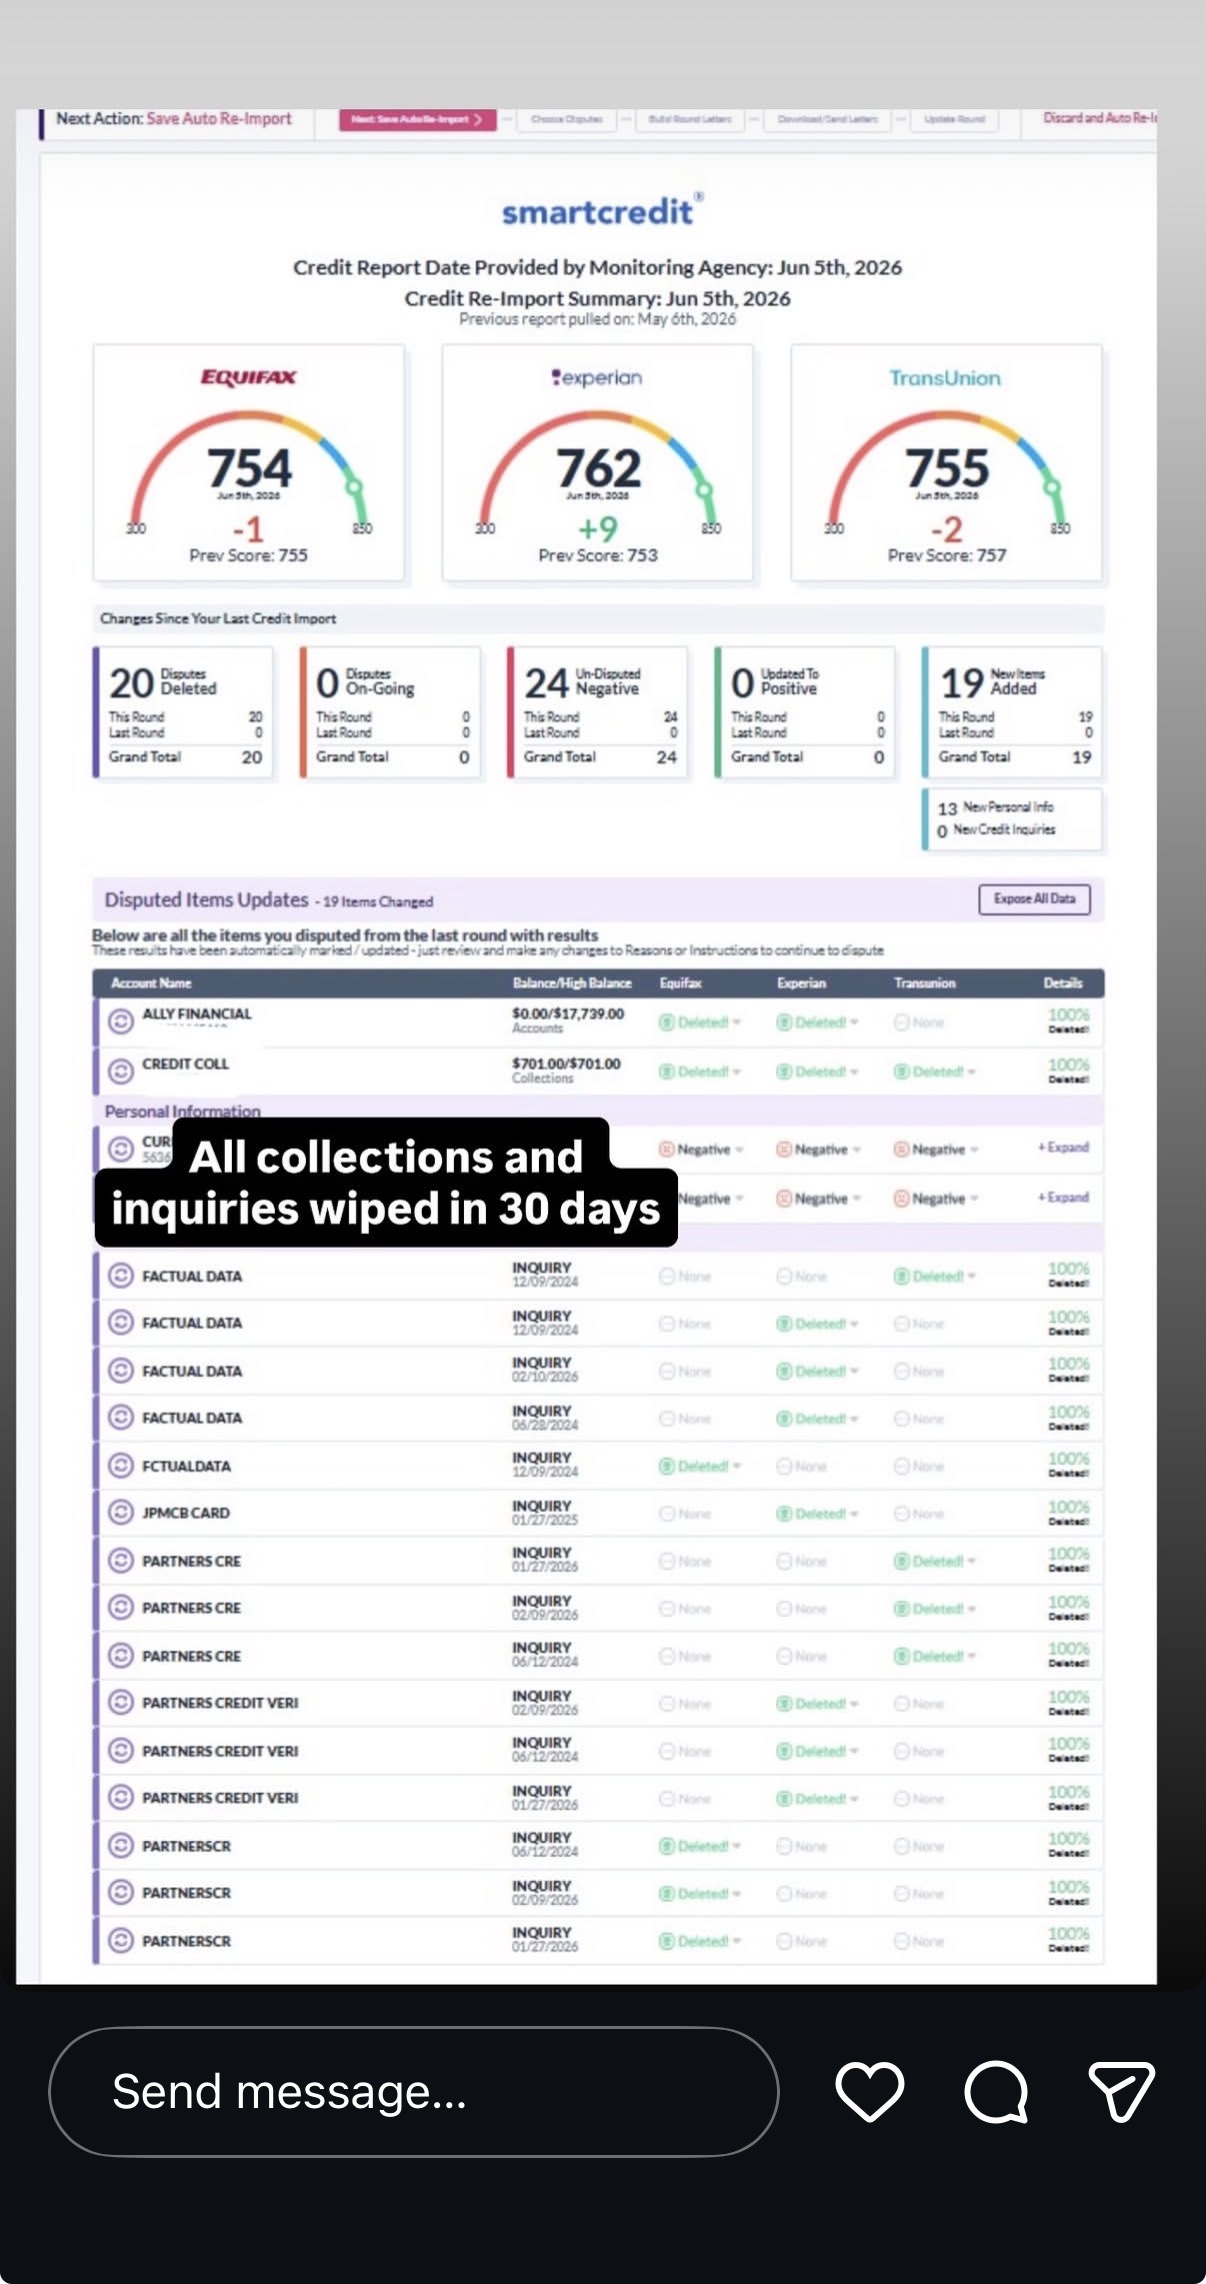
Before you book your audit
Is this legal?
Completely. The Fair Credit Reporting Act gives you the right to dispute any information on your credit report that is inaccurate, incomplete, or unverifiable, and it requires the bureaus and the companies furnishing that data to investigate.
Azzurri Credit operates under the Credit Repair Organizations Act. That means a written contract, a 3-day right to cancel, and no payment for work before that work has been performed.
What if the negative items on my report really are mine?
Accurate, verifiable information is allowed to stay on your report. Nobody can legally promise to remove it, and anyone who does is lying to you.
But "accurate" means every detail. The balance, the dates, the account status, who owns the debt now, and whether it is reporting the same way at all three bureaus. When debts get bought and sold, those details break constantly. If the company reporting an item cannot prove every piece of it, the law requires it to be corrected or deleted.
We never ask you to claim an account is not yours when it is, and we never file false identity theft reports.
How fast will I see results?
Bureaus and furnishers generally have 30 days to respond to a dispute. Many clients see their first items come off within the first 30 to 45 days.
Your full timeline depends on how many items you have and how each company responds. Your specialist will map it out for you on your free audit. Individual results vary.
How is this different from the credit repair company I already tried?
Most credit repair companies send template letters to the three bureaus and wait. When the bureau pings the creditor and gets back "verified," they send the same letter again next month.
We go to the source. We trace each item to the furnisher, collector, or data company reporting it and demand the documentation behind it. And we keep working round after round instead of stopping at the first "verified."
Do I have to do anything?
Almost nothing. After your audit you sign your agreement, connect your credit monitoring, and forward us any mail you receive from the bureaus. We write every letter, track every deadline, and text you each time something comes off.
Will this hurt my credit score?
No. Disputing inaccurate information does not lower your score, and your free audit does not trigger a hard inquiry.
How much does it cost?
It depends on what is on your report, which is exactly why the audit is free. Your specialist will show you what we found and what it costs to fix before you commit to anything.
You are never charged for work that has not been done. Results or money back.